These solutions cover all ten questions, including every printed subpart. The original PDF supplies the adjoints in Question 5, the fourth powers in Question 7 and the complete Question 10. Two qualifications to the printed wording are explained where they arise: unitary diagonalisation in Question 5 and the integration limits in Question 10.
Coordinate surfaces and sketch. Adding and subtracting the defining relations gives and . Since , we have . For , eliminate to obtainThis is a parabolic cylinder parallel to the axis, opening towards negative , with cross-sectional vertex and focus at the origin. Similarly, givesa parabolic cylinder opening towards positive , with vertex and the same focus. The degenerate surface is the half-plane ; gives . Constant gives the horizontal planes .
Thus the requested cross-sections consist of , , , and the two horizontal half-axes. The parabolas of the two families meet orthogonally.
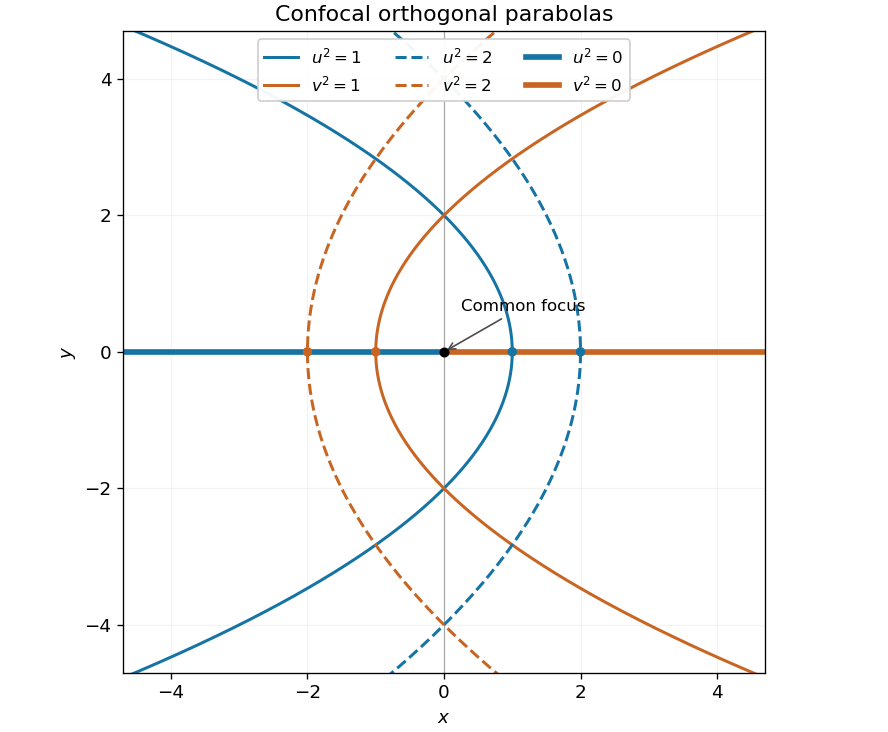

Signed coordinates. Take and choose the sign of to agree with away from . Then the Cartesian coordinates areEvery coordinate triple gives exactly one point. For , and have the same sign. A fixed signed selects the upper or lower half of its parabolic cylinder; the entire cylinder corresponds to fixed . On the cut , the two values represent the same point of the negative half-axis. This boundary identification is unavoidable: there even when , so the sign prescription is understood by approaching from either side of the cut. The interior gives a unique coordinate chart off that half-axis.
Orthogonality and metric. Differentiate the position vector:The pairwise dot products vanish. Their lengths give the scale factors of orthogonal coordinates and hence the Riemannian metric:These are parabolic cylindrical coordinates. The differential calculation is regular for ; the axis is the coordinate singularity where the two planar tangent vectors vanish.
Laplacian. Put . The physical components of the gradient of a -independent scalar field are . Applying the divergence formula cancels the two equal scale factors of orthogonal coordinates inside the derivatives:Therefore, away from the coordinate singularity,
Steady state. In the heat equation, time independence makes the second spatial derivative zero. The two endpoint temperatures therefore determine the linear profileInsulation is along the sides; the endpoint reservoirs can still exchange heat with the rod.
Transient solution. Subtract the steady profile before applying separation of variables: let . Then , and for . Writing givesThe homogeneous Dirichlet boundary conditions exclude and select the eigenfunctions with eigenvalues , . Their orthogonality gives the Fourier sine series coefficientsHere integration by parts uses . ThusEvery summand satisfies the heat equation and the homogeneous endpoint conditions, while the steady profile supplies the prescribed endpoint values. The initial Fourier sine series equals in the open interval. At the initially cold rod and the suddenly imposed hot endpoint are incompatible; the formula describes the prescribed data for and the initial limit at interior points.
Heat absorption. Integrating in kills the even modes. With , the total heat relative to the initial state isConsequently the net rate of heat absorption isFor each , any fixed number of differentiated modes is bounded by a polynomial in times . These bounds have finite sums, proving absolute convergence, uniform convergence on such time intervals and the validity of the integration and differentiation. In particular the displayed rate is finite for every , positive when , and tends to zero as equilibrium is approached. The same answer follows from the heat equation balance ; this subtracts loss at the cold endpoint from input at the hot endpoint.
Transform convention and derivatives. Use the Fourier transform pairFor sufficiently decaying with integrable second derivative, two applications of integration by parts giveThe identity also holds for tempered distributions, which is the setting needed for the Dirac delta function boundary data.
Upper half-plane solution. Take the Fourier transform in only, writing . Laplace's equation becomes . For , discard the exponentially growing solution and use , the Fourier transform of the Dirac delta function. This gives . The value at can be set to its continuous limit one. Pointwise decay of as does not require this individual transformed value to decay: the total integral in remains one while the profile spreads.
The inverse Fourier transform now yields, for ,Evaluate the last integral as the real part of :This is the Poisson kernel for the upper half-plane. Its boundary condition is a distributional convergence, rather than an ordinary value at : for a smooth compactly supported test function ,The dominated convergence theorem applies because is bounded and is integrable. Also , proving the required decay as .
Direct verification. Differentiating the rational expression givesTheir sum is zero throughout , so the solution is a harmonic function there.
Nilpotence and eigenvalues. If with , then . Thus forces for every eigenvalue. Conversely, if all complex eigenvalues, counted with algebraic multiplicity, vanish, the monic characteristic polynomial is . The Cayley-Hamilton theorem then gives . HenceThis is the criterion for a nilpotent matrix.
Symmetric case. Here a symmetric matrix is understood to be real. The spectral theorem gives with orthogonal and real diagonal. The previous result makes every diagonal entry zero, so . Alternatively, choose , so . For every real vector ,It follows that . Repeat until . This uses positivity of the quadratic form . The restriction to real symmetric, or complex Hermitian matrices, matters: a complex matrix satisfying only need not have this positivity.
The parameters and powers. The first two columns of coincide, so for all . The sum of its principal two-by-two determinants, each a minor of a matrix, isTogether with , this givesFor every eigenvalue to vanish both remaining coefficients must be zero. ThereforeDirect multiplication at these values givesIndeed the first row of multiplied by is , and the second row is its negative.
Geometry of repeated application. For any parameters the image of a linear map lies in the span of and , since . Thus it lies in a fixed plane through the origin, independently of the input. When are independent its normal is ; if they coincide, the image is a line and is still contained in a plane.
For , put and . ThenThe columns span this entire plane, so has rank two. The next two steps areThus the image of a linear map contracts from a plane to a line and then to the origin under successive applications. The line from is precisely the kernel of .
The conjugate transpose reverses products and conjugates scalars. Since are Hermitian matrices,Therefore In particular the commutator of two Hermitian matrices is anti-Hermitian, and multiplication by converts it to a Hermitian matrix.
Suppose and . ThenBecause the eigenvalues of are distinct, the eigenspace for is one-dimensional. It follows that , including the possibility . Thus an orthonormal eigenbasis of is also an eigenbasis of . The simplicity of both spectra means their eigenvectors coincide as directions, up to ordering, phases and nonzero scalar multiples.
Conversely, if they share a complete eigenbasis, choose the unitary matrix whose columns are these common normalized eigenvectors. Then and are diagonal, so and . HenceThis is simultaneous diagonalization of the two Hermitian matrices.
The original PDF uses the conjugate transpose , rather than the transpose found in the transcription. The printed diagonalisation criterion is correct when diagonalisation means unitary diagonalization of a normal matrix. Since ,Consequently if and only if . By part (ii), this gives a common unitary matrix andwhich is diagonal. Conversely, if for a diagonal and a unitary matrix , thenThus the precise conclusion isIf arbitrary invertible changes of basis are allowed, the printed assertion is false. For example,satisfy . Both Hermitian matrices have distinct eigenvalues: for and for . The distinct eigenvalues make diagonalizable by similarity, but and differ. This distinguishes ordinary diagonalization from the required unitary version.
As is a unitary matrix, . Let . Its conjugate transpose is , so and every positive integer power are Hermitian matrices and have real eigenvalues.
More explicitly, if with real, then form an eigenbasis andThereforewhere denotes the matrix size, to distinguish it from the power .
Divide the Chebyshev differential equation by . Its coefficients and are analytic at zero, so The finite singular points of a differential equation are .
Insert , . The coefficient of the lowest power is , hence or . The next power gives , and the remaining powers yieldFor , is free andChoosing selects the even power series, with . For , the next-power equation forces andThis selects the odd power series, with . Their different initial values prove linear independence. Although the Frobenius method produces two possible leading exponents, zero is an ordinary point, and a general series already includes both initial constants.
Let for integer . In the even or odd power series whose parity matches , the numerator in the recurrence relation vanishes at the coefficient of . All coefficients of lower powers in that parity are nonzero, and all higher ones vanish. Therefore a polynomial solution exists, of polynomial degree , containingFor nonnegative these are the Chebyshev polynomials . The normalized low-degree cases follow directly from the recurrence relation:Enforcing givesTo see that normalization at one is always possible, set in the Chebyshev differential equation. For , the differential expression becomes . Thus gives on and has value one at . It is a polynomial because the cosine addition formula gives . Negative integer produces the same solution as .
Write a nonterminating parity series as , where or . Its recurrence relation isThe ratio test applied to its nonzero successive terms has limiting absolute ratio . Hence the series converges absolutely for and diverges for , withAt , the limiting ratio is one, so the basic ratio test alone is inconclusive. Retain the next term of the ratio instead:For large the ratio is positive. Taking logarithms and summing gives ; the remainders have a finite sum. Thus eventually. Comparison with the convergent p-series proves absolute convergence at both endpoints as well:The radius of convergence one is the distance from the expansion point to the nearest singular points of a differential equation, . Convergence of function values at those points does not make the solutions analytic there; endpoint derivatives can diverge. The terminating Chebyshev polynomial is an exception with infinite radius of convergence. For example, at the other solution is , whose endpoint values are finite while its first derivative diverges.
Multiply the differential equation by and compare the coefficients of and with . The required integrating factor satisfies . Thus one may takeThen , the desired Sturm-Liouville form, with the same homogeneous Dirichlet boundary conditions. A common positive constant multiplying is immaterial. For the usual regular Sturm-Liouville problem one also assumes real sufficiently regular coefficients and , ensuring .
Mixed endpoint spectrum. For , integration against and integration by parts, using , gives for every nonzero real eigenfunction. Thus and the first condition makes . The second requires , so , . Sincethe normalized eigenfunctions and eigenvalues areThe orthogonality also follows by applying integration by parts to two different eigenfunctions of the same self-adjoint differential operator.
Forced expansion. Let and write , . The Fourier coefficients of the forcing arebecause the boundary cosine vanishes and . Applying to the eigenfunction expansion gives . Since is not an eigenvalue,The coefficients are , so the series and its first two differentiated series converge absolutely and uniformly on the interval. Each term satisfies the two endpoint conditions, and equals the mixed-endpoint Fourier series of . The forcing coefficients are , giving uniform convergence of that series as well. Uniqueness follows because the homogeneous problem has a nonzero solution only at one of the excluded eigenvalues.
Odd fourth-power sum. Set . Direct integration of , with the same endpoint conditions, givesAt , the eigenfunction expansion instead gives . Equating the two values yieldsAbsolute and uniform convergence justify evaluation at the endpoint.
Use reduction of order by setting . Then and , so the differential expression simplifies toIn the homogeneous case is constant. Hence , and a basis of the solution space isTheir Wronskian is on , proving linear independence. No nonzero homogeneous solution satisfies both endpoint conditions: sets , and then sets .
Choose the homogeneous solutions , which vanishes at , and , which vanishes at . Their Wronskian in the order is . For a source point , seek the Green's function asIt is continuous at ; otherwise its second distributional derivative would contain a derivative of the Dirac delta function, which the source does not contain. Integrating the differential equation across the source, using continuity and the leading coefficient one, gives the jump conditionContinuity and this derivative jump requireSolving with the Wronskian gives and . ThereforeThe two values at are identical. The derivative jump is explicitlyBoth endpoint values vanish and the differential expression is zero off the diagonal, completing the verification of the Green's function.
By superposition, . Split the integral at : the portion uses the first branch of the Green's function, and the portion uses the second. This yieldsFor , put . The two integrals areSubstitution and cancellation giveIndeed . For a direct differential check,and thereforeThe homogeneous uniqueness shown in part (a) makes this the unique solution.
For the real Sturm-Liouville operator , two integrations by parts give the Lagrange identity for a Sturm-Liouville operator:Set . Both vanish at the endpoints, so the boundary term is zero. Since ,ConsequentlyThis is self-adjointness with the homogeneous Dirichlet boundary conditions, and expresses the Fredholm solvability condition at the eigenvalue . In this unweighted integral already contains its factor of ; adding another weight would be incorrect.
Assume the regular real Sturm-Liouville problem, with , ordered eigenvalues , and real orthonormal eigenfunctions in the weighted inner productThe Rayleigh quotient for an admissible trial function isThe second expression follows by integration by parts. It is the quantity used in the Rayleigh-Ritz method.
For , orthonormality eliminates every cross-term in the denominator:Applying to the eigenfunction expansion and using the same orthogonality in the numerator givesHence, whenever the trial function has finite energy,Put and . The exact error and its expansion areIn particular, under a common small scaling with fixed finite sums and ,The fourth-order remainder includes mixed products , not just individual fourth powers.
Error comparison and sign. Since , the relative weighted norm error of the supplied trial function isFor , the relative eigenvalue error is . Thus the Rayleigh quotient has a second-order error for a first-order error in the trial eigenfunction, provided the energy-weighted coefficient sum is controlled. Small weighted norm error alone does not control arbitrarily high-frequency contamination, because can grow without bound. If , an absolute error must replace the undefined relative one.
Finally every summand of is nonnegative. Thuswith strict inequality whenever some . This is the upper-bound property of the Rayleigh-Ritz variational principle for the lowest eigenvalue.
Let be a stationary function and perturb it to , where is smooth and . These perturbations preserve the prescribed endpoint values. Differentiate the functional at :By integration by parts,The boundary term vanishes. The remaining integral must vanish for every such , so the fundamental lemma of the calculus of variations gives the Euler-Lagrange equationIt is a necessary stationarity condition; deciding whether the stationary path is a minimum requires additional information.
Length functional. On the unit sphere, write the position vector in spherical coordinates asIts two coordinate tangent vectors satisfy , and . Consequently the induced Riemannian metric is . On a segment for which increases and ,Segments where is not monotone require another parameter or a subdivision. Endpoint turning points can be handled by a limit.
First integral. With , there is no explicit dependence. The Euler-Lagrange equation therefore says thatis constant. For , put and solve:The radicand must be nonnegative along the chosen segment. The printed expression with both limits fixed at describes a longitude difference between endpoints; a formula for needs the variable upper limit and the additive constant shown here. The case gives a meridian with constant longitude. The equator is also a stationary route, although it cannot be parameterized using changing .
Integration and geometric meaning. Put , so andFor a nonconstant segment , and writing , the integral becomesRearranging, and absorbing phase and sign into two constants, givesMultiplying by shows that the corresponding Cartesian coordinates satisfy . Thus every such stationary route lies in a plane through the sphere's center: it is a great circle, the geodesic of the sphere. The meridians and equator are the limiting or separately parameterized cases of the same description.
Rome to Singapore. Use exactly the approximate coordinates supplied in the question: at departure and at arrival. Inserting them into the preceding relation determinesIndeed the right side is one at Rome and zero at Singapore. This corresponds to , . In latitude , the route is : it starts at north with an initially eastward heading and then curves southward to the equator. The first-integral expression in has an integrable endpoint singularity at departure, where has a turning point; the longitude parameter is regular there.
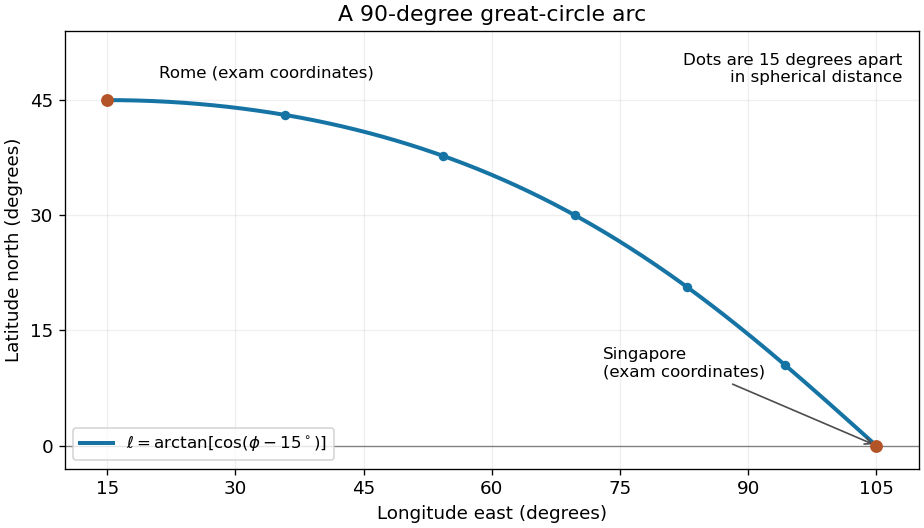
Shortest spherical route for the approximate Rome and Singapore coordinates in the question
. Latitude versus longitude for the derived great circle, with endpoints at 45 degrees north and 15 degrees east, and zero degrees north and 105 degrees east. The quarter-circle parameter increases uniformly in spherical distance. Details.
For an explicit regular arc-length parametrization, let and . Their dot product is . HenceBoth and equal one. The shorter great circle arc is the global shortest path: for any unit-speed curve from , its central angle satisfies by the Cauchy-Schwarz inequality, since the tangential projection of has length . Integrating gives length at least the endpoint angle , which this route attains. For a sphere of radius , the corresponding shortest distance is .
Original examination paper. The solutions below cover all ten questions, including every lettered and numbered part. The original PDF is authoritative for notation and matrices.
Apply the Laplacian in polar coordinates twice to the proposed separated function. For any real exponent ,so the biharmonic equation becomesIts four distinct roots are . The separated polar solutions of the biharmonic equation therefore give the complete radial family in this angular sector,Equivalently, its radial equation is a fourth-order Cauchy-Euler equation; four distinct powers supply four linearly independent solutions, so no logarithmic terms are required.
Interior. Continuity with value zero at the origin removes both and . The latter depends on the approach direction even though it is bounded. The two boundary conditions at unit radius then give and . ConsequentlyThis extends smoothly through the origin: and are polynomials. Its radial derivative at is .
Exterior. The condition on the radial derivative at infinity excludes the and terms. A nonzero is permitted, since the required decay concerns the radial derivative. Now and , givingIndeed , and its value at unit radius is zero. These are particular interior and exterior solutions for the biharmonic streamfunction; no condition requiring itself to vanish at infinity was imposed.
Integral identity and representation. Define and take to be the outward unit normal. The product rule givesThe terms cancel. Integrating and applying the divergence theorem proves the Helmholtz equation version of Green's second identity:
Choose the Dirichlet Green function with the sign conventionwhere is the three-dimensional Dirac delta. Substitute , use , and evaluate the Dirac delta integral. The boundary term containing vanishes and on , leavingHenceThe choice of sign in the Green function equation matters: it fixes both the source normalization and these signs. For a bounded region this construction presumes that the chosen is not a Dirichlet eigenvalue of ; at such an eigenvalue a Green inverse for arbitrary data does not exist.
Infinite space. Put . Away from the source, spherical symmetry reduces the Helmholtz equation toFor its general radial solution isIntegrate over a ball of radius about the source. The divergence theorem yieldsSince , the volume term is and the flux tends to . Therefore , while remains free:The term extends regularly through the source and solves the homogeneous Helmholtz equation, so it cannot change the unit Dirac delta normalization. A condition at infinity is needed to select it. For example, with time dependence , the outgoing Green function for the three-dimensional Helmholtz equation is , corresponding to .
Zero wavenumber. For fixed finite , as , andThis is the decaying Green function of the Laplacian. Directly at , the general radial solution is ; source normalization fixes , and decay at infinity removes . If the free parameter depends on as , the limit instead includes that arbitrary homogeneous constant. Thus the usual Laplace limit holds for a fixed parameter, or after a suitable condition at infinity has been selected.
Branches and cuts. For the square root of z squared minus one, a branch point is a point around which analytic continuation along an arbitrarily small closed loop can change the value of a chosen branch of a multivalued function. Near , the square root behaves as ; near it is a nonzero analytic factor times . One circuit around either point reverses its sign. Thus the finite branch points are . Infinity is not a branch point: in the expression is , which has two single-valued meromorphic choices near zero.
A single branch cut can join to ; its shortest choice is the real segment . Any surviving loop then surrounds either both branch points or neither, so it produces no sign change. Alternatively, use two branch cuts, and , each joining a branch point to infinity. On the resulting slit region one can choose a consistent branch of a multivalued function.
For the finite cut, fix at infinity, equivalently for . To give its actual values on both sides, putFor , the selected square root isHere ; when , . Squaring verifies the formula because . Its real part has the sign of , its imaginary part has the sign of , and it matches the chosen value at infinity. In particular, the two boundary values on the branch cut areOutside the cut, . Reversing the global branch of a multivalued function reverses every displayed value.
Differential equation. Write with this finite cut, and orient counterclockwise with one circuit around it. Since is fixed and avoids the branch points, differentiation under the integral sign givesOn the contour . ThereforeThe last contour integral vanishes because the expression in brackets returns to its original value after circling both branch points. This proves , including at ; division by is unnecessary.
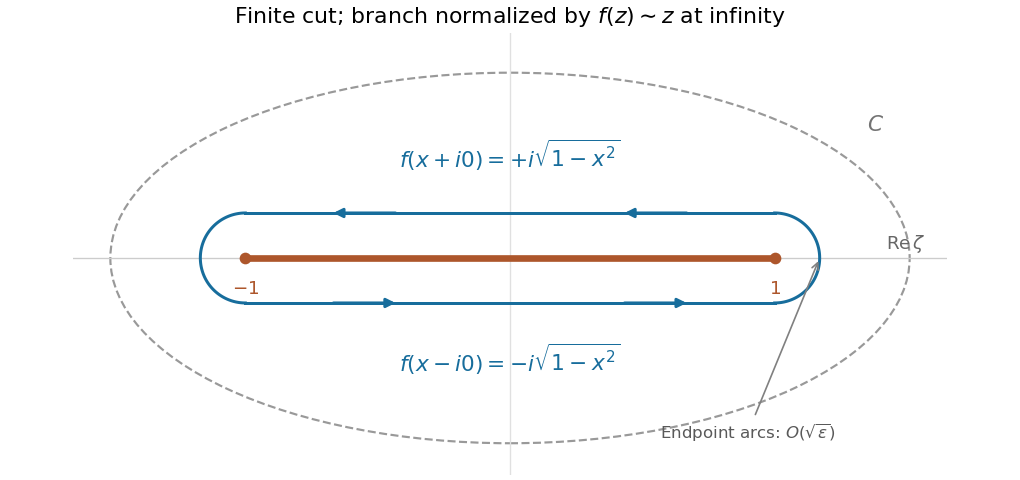
Shrinking a counterclockwise contour around the finite square-root cut
. The upper lip runs from 1 to -1, and the lower lip returns from -1 to 1. The endpoint arcs have vanishing integrals. The values shown use the branch that behaves as z at infinity. Details.
Value at zero. Near either endpoint , the integrand at zero is . A small arc of radius has length and hence contributes . The upper lip runs from to , and the lower lip from to . ThusUsing evaluates the final integral as , and soThe same deformation gives . The sign of reverses if either the global square-root choice or the contour orientation is reversed; the differential equation is unaffected.
Definitions. In a punctured neighborhood of , let the Laurent series be . The point is a pole of order if and every coefficient with index less than vanishes. Its residue is . A simple pole has .
Poles for . Denote the bracket in the denominator by . Factoring givesPut , so . The finite poles are , all simple; the numerator is nonzero at each. At zero,At a nonzero simple root of , the residue formula givesFor , ; for , . Substitution yieldsThe two zeros of a function at do not cause additional poles: there and the numerator vanishes.
The case . Simplify before using any formulas that divide by :Thus its only finite pole isAs , the two inner poles merge with zero while the outer two escape to infinity. If one also considers the Riemann sphere, at has a simple pole at infinity because ; the requested unit-circle calculation only uses finite poles.
Unit-circle integral. Set . ThenAt the two angles where the tangent is undefined, the real integrand has continuous limiting value zero. Thus the substitution is valid for the improper integral, or after that continuous extension. No pole lies on for any allowed .
For , the sum of the enclosed residues isThe residue theorem therefore givesAt the enclosed residue is , giving , exactly the same formula. The direct simplification provides an independent check of that endpoint.
For a piecewise continuous function of exponential order on , its unilateral Laplace transform isThe Bromwich inversion formula, at a point of continuity, isThe Bromwich contour is a straight vertical line, traversed upwards, with to the right of the abscissa of convergence and hence of all singularities of the transform. Under the usual piecewise smoothness assumptions, at a jump the symmetric inversion limit gives the mean of the two one-sided values.
In the transform in the question, put . Then andThus the restricted Mellin transform on the unit interval is the Laplace transform of . Apply the Bromwich inversion formula with , where , to obtainHere lies in the convergence half-plane of . At a discontinuity this formula has the same mean-value interpretation. The real natural logarithm defines unambiguously.
Choose . The inverse integrand is . Because , the exponential factor decays towards the left. Closing the Bromwich contour to the left and using the residue theorem picks up just the simple pole at , with residue . HenceIts defining integral checks both the answer and its convergence condition:
Now the inverse integrand can be writtenFor , the exponent has a positive real time parameter. Close the Bromwich contour to the left; the residue at is . For , close to the right, where there are no poles. The reversed orientation there still gives zero. ConsequentlyThe same result follows from the Laplace transform time-shift rule: corresponds to , where is the Heaviside step function.
The original transform cannot fix a value at the single point . The Bromwich inversion formula chooses the average of the limiting values and zero, giving under that convention. Indeed,regardless of the assigned value at the jump.
For Cartesian tensors, let be the orthogonal matrix taking old vector components to new ones, . A rank- tensor transforms by one copy of on each index:Repeated indices are summed according to Einstein notation. In general coordinates a contravariant tensor index instead carries the corresponding Jacobian matrix , and a covariant tensor index carries its inverse; in orthonormal bases of Cartesian axes their component laws coincide with the displayed form.
An isotropic tensor has identical components after every proper orthogonal transformation, so for every with and . Requiring reflection invariance as well is a stronger convention for odd tensor ranks. The Kronecker delta is invariant under all orthogonal transformations, while the Levi-Civita symbol is invariant under proper rotations and acquires a determinant sign under reflections.
First separate the symmetric tensor and antisymmetric tensor parts:The trace of the antisymmetric part vanishes. In three dimensions, remove one third of the trace from the symmetric part, and identify the remaining antisymmetric part with an axial vector. The scalar, symmetric-traceless and axial tensor decomposition isHere and . The contraction of two Levi-Civita symbols verifies the reconstruction:ThereforeThe pieces contain , and independent components respectively, accounting for all nine entries. Taking the trace, then the traceless symmetric part, then the antisymmetric part shows that the decomposition is unique.
Contract the given isotropic fourth-rank tensor with the strain array. The stress tensor isWrite , where is symmetric and traceless. Then and . Substitution givesBy uniqueness of the scalar, symmetric-traceless and axial tensor decomposition,This is isotropic elasticity on tensor components: the three tensor sectors do not mix. If the strain is symmetric, , hence and . No equality between and is needed for that conclusion.
A normal mode is a fixed displacement pattern whose components share a common harmonic time dependence in the equations for small oscillations. Its normal frequency is the associated oscillation frequency; below, denotes the angular frequency, so the frequency in cycles per unit time is . A normal coordinate is the amplitude of one such pattern, chosen so that the linear equations decouple. For mass matrix and stiffness matrix , the patterns solve . Zero eigenvalues describe free rigid motions rather than periodic restoring oscillations.
Use the equilibrium coordinates specified in the paper; their distances from the origin are one and their mutual separation is . Let be the small displacements. Each initially unstretched spring has, to first order, extension equal to the relative displacement projected along its original bond. Choose the three oriented extensionsThe kinetic energy is exact in these displacement coordinates, while the potential energy needed for small oscillations is its quadratic part:The factor in the equilibrium bond length cancels when forming the unit bond directions. Applying the Euler-Lagrange equation, or differentiating for the force on each mass, givesThe total force vanishes componentwise, as expected for three masses coupled only by internal spring forces.
Order coordinates as . For either uniform displacement, or , every relative displacement and every extension vanishes. These normal modes have zero normal frequency and represent two independent planar translations.
For , substitution givesThus too. A small rigid rotation through angle moves equilibrium position by . With the specified positions this displacement is , identifying the third vector as infinitesimal rigid rotation. HenceA zero-frequency normal coordinate obeys , so . This permits a constant displacement or a uniform velocity at the level of the linearized equations. In particular, the rotational pattern preserves lengths to first order; finite-angle rotation follows a curved path outside a single linear displacement pattern.
For the normal modes of an equilateral spring triangle, the complement of the three rigid motions has dimension three. One convenient mutually orthogonal basis isThese vectors are also orthogonal to , and each has squared length . Their geometry comes from applying symmetric linear deformations to the equilibrium triangle: is uniform expansion, stretches one axis while compressing the other, and is the second independent shear pattern. Their extensions areInsert each row into the force equations. For example, gives and , with the same proportionality in every component. The other two rows similarly give force times their displacement vector. Thusand the remaining normal modes and normal frequencies areAny orthogonal pair spanning the same two-dimensional shear subspace is equally valid, because its eigenvalue is repeated. The six displayed vectors are nonzero and mutually orthogonal, so they supply all six independent normal modes without solving a characteristic polynomial.
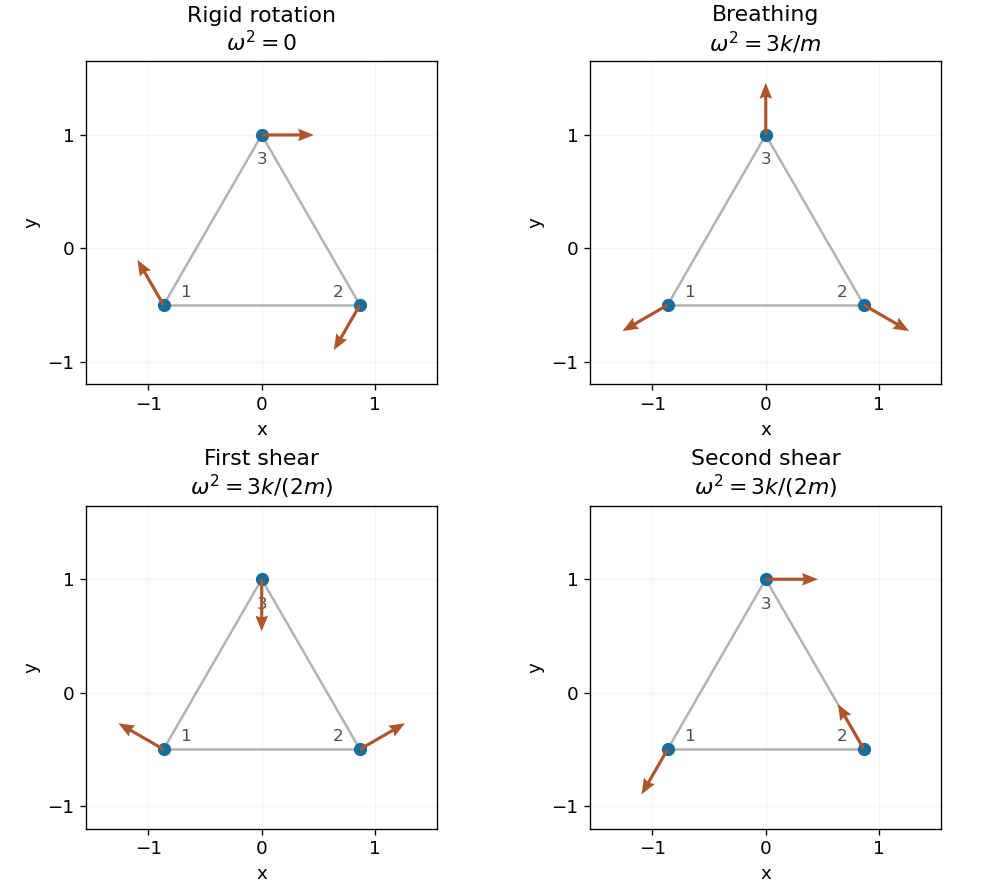

For explicit normal coordinates, normalize by and by , and write . Since all masses are equal,Positive-frequency coordinates have ; the three rigid coordinates have the linear form found above.
Cosets and counting. A left coset of a subgroup in a group is . The left cosets partition and each has elements. Lagrange's theorem states that for a finite group, ; in particular, the subgroup order divides the group order.
The matrix group. Work throughout in the finite field , so every nonzero entry has a multiplicative inverse. Denote a matrix by , with . Ordinary matrix multiplication, interpreted using modular arithmetic, givesIts diagonal entries remain nonzero, proving closure. Associativity is inherited from matrix multiplication, is the identity element, andThis lies in the same set and multiplication checks the inverse in either order. Thus these matrices form a group. There are four choices each for and and five for , giving .
The subgroup. Write . ThenIt contains the identity , is closed, and has inverse . Interchanging the two factors leaves the product unchanged because multiplication in is commutative. Therefore is an abelian subgroup, withEquivalently is isomorphic to by , which also explains its abelian property. Its order divides , verifying Lagrange's theorem.
There are five distinct left cosets. Representatives can be taken as , : indeedEvery matrix lies in exactly the coset specified by this unique .
Elements whose square is the identity. Squaring givesThus and . For equal signs, in , so . For opposite signs, and all five values work. The complete set is thereforeIt contains elements, including the identity; the other eleven are involutions. Since does not divide , Lagrange's theorem proves that this set is not a subgroup.
Conjugacy classes. For , its conjugacy class isEvery element belongs to its own conjugacy class, by taking . To prove uniqueness, suppose belongs to both and . ThenFor every , this makes a conjugate of as well. Hence , and reversing the argument gives the other inclusion. Two conjugacy classes that meet are therefore equal, proving that the classes partition .
Centre. An element has a singleton conjugacy class precisely when for every , equivalently for every . Thus the definition in the paper agrees with the usual centre of a group:The identity lies in . If , then for any , , so . Also implies , so . This proves it is a subgroup. Any two of its elements commute because either one commutes with every element of . Consequently .
Square symmetry. Use the paper's notation for the eight-element dihedral group of a square. Let be a quarter-turn and a reflection, so and . A rotation commutes with exactly when , or modulo four. This selects and . No reflection commutes with , becauseand . Therefore
Definitions and labels. A complex group representation on a vector space is a group homomorphism , so and . It is an irreducible representation if and its only invariant subspaces are and .
Read permutation matrices by their action on column basis vectors. The labels in the original PDF areIn particular, the original PDF gives the last row of as ; the provided TeX transcription's is incorrect and would not give an invertible permutation matrix.
Multiplication and conjugacy. Matrix products act on columns with the right factor first. For example , , and . The complete multiplication table, with row factor multiplied by column factor, isConjugating a permutation relabels its cycles. Thus the conjugacy classes areof sizes one, two and three. These are respectively the identity, the three-cycles and the transpositions in the symmetric group on three letters.
Dimensions. The sum of squares of irreducible representation dimensions equals the group order, which here is six. A three-dimensional irreducible representation would already contribute nine, so the displayed representation is reducible. There are three inequivalent complex irreducible representations, one for each conjugacy class, including the trivial representation of dimension one. If their dimensions are , then , whose positive integer solution is . HenceOne can also see reducibility directly: every permutation matrix fixes .
Characters. The character of a representation is the trace of its representing matrix, constant on each conjugacy class. The given permutation representation has character equal to the number of fixed basis vectors:in class order . A trivial representation has character . For the second one-dimensional character, a transposition has value because its square is the identity. The two three-cycles are conjugate and inverse, so their common value obeys both and , forcing . Character orthogonality with the trivial character then requires , giving . This determines the sign representation without constructing its matrices.
Write the two-dimensional character as . Character orthogonality with the first two rows givesso , . Its squared norm is , as required. The complete character table is thereforeThe last row belongs to the standard representation of the symmetric group.
To decompose the given representation, use the character inner productIts multiplicities areThusConcretely the invariant line is spanned by and its invariant complement is . Their characters are exactly the first and third rows, agreeing with the decomposition obtained entirely from character orthogonality.
Articles by others on the same topic
There are currently no matching articles.