The integral is finite because a continuous function on a compact closed interval is bounded. Nonnegativity is immediate, and absolute homogeneity of a norm follows from . The pointwise triangle inequality givesFor positive definiteness, if , continuity gives a relative interval of positive length on which . Its integral is positive, including when is an endpoint. Thus implies , and this is a norm on the given vector space.
For the given sequence,The last bound tends to zero as both indices tend to infinity, proving the Cauchy sequence property. Moreover, the sequence converges to the zero function in this norm:There is no conflict with the nonzero endpoint values: convergence in this norm does not imply pointwise convergence.
Write the cone as , with the distance from its axis and . Its Euclidean metric givesConsequently a differentiable path expressed as has arc lengthFor , the Euler-Lagrange equation has the Beltrami identity because has no explicit dependence:For a nonradial minimizing path, . Rearranging and integrating givesThe endpoint conditions determine and on the selected angular branch.
To verify that this stationary path really minimizes arc length, use the local isometry from a circular cone to the plane. Set and ; then is the plane metric. The displayed path is a straight line , so its segment realizes the plane distance. Choose endpoint angular lifts with ; then , and the joining segment avoids the apex. Its length isOther lifts with developed angular difference less than give at least this distance; an angular change of at least has infimum at least , attained only if passage through the apex is allowed. This proves the global choice above. Endpoints on a common generator have the radial segment as shortest path, which is the limiting case omitted by the parametrization. If an endpoint is the apex, its shortest path is a generator. Thus shortest paths are straight segments after developing the cone.
Fix any . The Cauchy estimate on the circle applies for every because is an entire function. It givesTherefore . Since was arbitrary and is connected, is constant. This is the sublinear case of the polynomial growth theorem for entire functions.
The composition is an entire function, andBy Liouville's theorem, is constant. Since the exponential function never vanishes,Thus is constant. Notice that constancy of an exponential alone need not be inverted by choosing a global logarithm; differentiating supplies the conclusion directly.
Let be the isometry. Since , it preserves norms, and the polarization identity applied to distances gives . For an orthonormal basis , the vectors are again an orthonormal basis, andExpanding in that basis proves . Hence is a linear map represented by an orthogonal matrix .
A reflection in a hyperplane with nonzero normal is . If , choose . Because , substitution shows . If they agree, no reflection is needed. The resulting orthogonal transformation fixes and preserves its orthogonal complement. Apply the same construction there to fix ; the second normal is perpendicular to , so the first vector remains fixed. Finally the restriction to the remaining line is either the identity or negation; in the latter case a third reflection, normal to , fixes it. Reversing these steps writes as a product of at most three reflections, each in a plane through the origin. This proves the three-dimensional case of the Cartan–Dieudonné theorem.
Three reflections are sometimes necessary. The map is the product of the three coordinate-plane reflections. Its determinant is , excluding zero or two reflections. A single plane reflection fixes a two-dimensional vector subspace, whereas fixes only zero, excluding one. Thus the bound is sharp.
Player A maximizes the payoff, while B minimizes it. The fourth row is strictly worse for A than the first in every column, so remove by dominated strategy elimination. On the remaining rows, column is strictly better for B than , so remove . Now is strictly worse than in the two remaining columns. The reduced zero-sum game has payoff matrixwith rows and columns .
If A uses mixed strategy , the expected payoffs against these columns are and . The first increases and the second decreases, so their minimum is maximized where they are equal: . ThusFor an optimality certificate, B uses mixed strategy , making A's first two row payoffs and . Equality gives . Against this B strategy the four row payoffs are , while against the displayed A strategy the three column payoffs are . Therefore A guarantees and B holds A to , verifying the value of a zero-sum game and the original, unreduced mixed strategy.
The Lagrange basis polynomials satisfy : for , the product has a zero factor, whereas for every factor is one. The polynomialhas degree of a polynomial at most and has distinct roots of a polynomial. The root bound for a polynomial implies . Hence the interpolation identity holds for every polynomial of degree at most .
At a simple root of a polynomial of , differentiating the product gives . Consequently the Lagrange basis polynomials can be writtenDivide the polynomial interpolation identity from part (a) by , at points outside the nodes. This gives the partial fraction decompositionEvery denominator of is simple, and the rational function is proper because , so no polynomial part is missing.
If , the two endomorphisms commute. The distinct real eigenvalues of have one-dimensional real eigenspaces, since their direct sum is the -dimensional vector space. Take a nonzero real eigenvector . Its eigenspace is invariant under , so for a real scalar . Squaring givesThe simple-spectrum hypothesis is essential: the real -degree rotation matrix squares to in dimension two, whose negative eigenvalue has a two-dimensional eigenspace.
With polar unit vectors and , the second term is . It is tangent to circles, independent of , and has zero divergence and zero vorticity away from the axis. Its singular axis carries a line vortex; adding the constant velocity field gives a uniform flow plus that line vortex.
The counterclockwise circulation around a positively oriented loop is . For a radius- circle, the uniform flow contributes zero and the line vortex contributesAny loop winding once around the axis has the same circulation, by Stokes theorem in the nonsingular intervening region.
On , , , and . ThusIn fact this equality holds for every for the stated field, since the remaining vector integral is .
This is the advective part of the momentum flux. To obtain the force, include pressure. For steady irrotational flow, the Bernoulli equation givesThe constant terms integrate to zero against ; the remaining pressure contribution is . The total outward momentum flux plus pressure term is therefore , the force of the obstacle on the fluid. The opposite force, of fluid on the obstacle per unit span, isThis is the Kutta–Joukowski theorem, with positive defined counterclockwise: positive and give force in the negative direction. For an actual two-dimensional aerofoil, faster-decaying far-field terms do not change this limit. The displayed advective integral supplies half the lift; pressure supplies the other half.
The discriminant of a binary quadratic form is ; it is unchanged by a unimodular matrix change of integral variables and satisfies or . For such a , the discriminant criterion for prime representation by a binary quadratic form says that some integral binary quadratic form of discriminant of a binary quadratic form represents an odd prime exactly when is a square modulo , including zero. Equivalently,These versions agree: a square root modulo can be chosen even when and odd when , by adding if needed, and then the Chinese remainder theorem applies.
For completeness, if , then is primitive, since any common divisor would have its square divide . Complete to a basis of with determinant one using Bézout's identity. The transformed binary quadratic form has leading coefficient and discriminant of a binary quadratic form . Conversely, a suitable makes an integral binary quadratic form representing at .
For , the discriminant of a binary quadratic form is . The prime is represented. If is represented, reducing modulo gives , which also excludes . To prove sufficiency for , quadratic reciprocity givesThe criterion constructs a positive definite binary quadratic form of discriminant of a binary quadratic form . It is primitive: a common divisor of its coefficients would divide , and if that divisor were , then would divide , impossible for .
We must still establish that this form is equivalent to , rather than merely some form of the same discriminant of a binary quadratic form. In a positive definite integral binary quadratic form, replace by to arrange . If , apply and repeat. Each such exchange strictly decreases the positive integer leading coefficient, so this reduction algorithm for a positive definite binary quadratic form terminates with . Then , so . With , parity forces , giving . With , the only integral choices are , and these are not primitive. Thus every primitive positive definite binary quadratic form of discriminant of a binary quadratic form is equivalent to , and preserves its represented integers. Therefore
The specified Compton scattering formula requires the electron to be initially at rest in the frame where the wavelengths and angle are measured. This initial-rest assumption is implicit in the printed request; it is not valid for arbitrary initial electron momentum. Use four-momentum with Minkowski metric signature : initially , while and are null. Conservation gives , and the outgoing electron satisfies the same mass-shell condition . HenceAfter dividing by and substituting the photon energy relation,The scale is the electron Compton wavelength. For a moving initial electron, the earlier invariant identity remains valid, but includes its initial velocity and the wavelength shift is different.
The contraction mapping theorem states that a contraction mapping of a nonempty complete metric space into itself has a unique fixed point. More explicitly, if with , iteration from any converges to that fixed point.
To prove this, put . Induction gives , so for the triangle inequality givesThus is a Cauchy sequence, and completeness supplies a limit . A contraction mapping is continuous, so . Two fixed points satisfy , forcing equality of the points. Passing to the limit in the bound also gives the useful error estimate .
For the function space, take nonempty; otherwise the supremum in the printed definition is undefined without a convention. Boundedness of makes the uniform metric finite. Nonnegativity and symmetry follow from ; means at every . Taking suprema in proves the triangle inequality. Hence is a metric.
Suppose is a Cauchy sequence for this uniform metric. At each , , so completeness of supplies a value . Given , choose with for all . Fix and let pointwise; then for every . Thus . The uniform limit theorem makes this limit continuous, so . This proves the completeness of the continuous-map space in the uniform metric.
Finally fix with contraction constant , and write and . Using the fixed point equations,Therefore the fixed-point stability in the uniform metric estimate isChoosing proves continuity of at every . The estimate uses the constant of the fixed map only; it does not require a common contraction constant for all nearby .
Assume the impulse point is in the interior, . Expand the displacement in the fixed-end Fourier sine seriesOrthogonality gives the initial velocity coefficient by applying the Dirac delta to the sine function:Substitution in the wave equation yields . For , its roots are , where . The two initial conditions determineHence the normalized velocity-impulse Green function for a damped string isFor a mode with critical damping, use the limit in place of the time factor. For , put and use . These choices solve the same modal ordinary differential equation and initial conditions, so the formula covers arbitrary . The impulse initial velocity is a distribution, so initial differentiation of the series is interpreted distributionally.
The printed formula requires correction: the factor depending on must lie inside the sum, and sine-mode normalization requires , rather than . The printed slash after the final sine is also stray. Direct differentiation at verifies the corrected normalization: the initial sine coefficients are exactly those of .
A mode has dimensionless damping ratio , and characteristic rootsIf , the normal mode oscillates at with exponentially decaying envelope . As , the solution approaches the undamped wave equation response.
If , the roots are real and negative, withThe mode has a fast transient and a slow nonoscillatory relaxation. After the fast transient, neglecting gives the diffusion equation for these long-wavelength modes. At , the repeated root produces : this is critical damping.
Thus the critical parameter is for each mode, and the fundamental threshold isWhen every mode is oscillatory. For any fixed, finite , sufficiently large still gives oscillatory modes, so large damping of the lowest modes does not mean that every mode of the full string is overdamped.
The complex Taylor series theorem states that if is holomorphic in , thenThe power series converges absolutely there and uniformly on each smaller closed disc; its coefficients are unique. For , the Cauchy integral formula also gives . This is the analytic, rather than finite real-variable, form of Taylor theorem relevant here.
Let , whose power series coefficients are . Suppose some coefficient is nonzero, and let be the least such index. Inside the common convergence disc,The parenthesized analytic function tends to as , so it does not vanish in some neighborhood. Hence has no zeros sufficiently near except possibly itself. This contradicts with and . Thus all coefficients agree:This also proves the local isolation of zeros of a nonzero analytic function.
Put . Choose a disc about contained in the domain . Part (a) gives a convergent Taylor series there, and the accumulating zeros together with part (b) force all its coefficients to vanish. Thus near .
To propagate this to the entire domain, defineThe set is nonempty by the preceding local argument. Each derivative is continuous, so is closed relative to as the intersection of their zero sets. If , its Taylor series is zero on a disc about , and all derivatives vanish throughout that disc; hence is open relative to . Connectedness forces . Therefore throughout , proving the identity theorem for holomorphic functions rather than merely invoking it.
Take the analytic functionIt vanishes at for every positive integer , but , so it is not identically zero. The identity theorem does not apply at the accumulation point , because that point lies outside the domain.
Let have the stated zeros but not be identically zero. The origin is an isolated singularity. If it were a removable singularity, the extended holomorphic function would have zeros accumulating at an interior point. The proof in part (c) would force the extension, and then on its domain, to be identically zero.
If the origin were a pole of order , then would have a holomorphic extension with . Continuity would make nonzero on a small disc, so would have no zeros in its punctured disc, again a contradiction. The classification of isolated singularities leaves only an essential singularity at the origin. This argument applies to every function in part (d), not just the particular sine example.
Work first on the unit sphere. A spherical lune of angle has area : its fraction of sphere area is . The three great circles extending the sides of a nondegenerate spherical triangle divide the sphere into four antipodal pairs of triangular regions. Call the desired region , of area , and its three adjacent regions , of areas . These four regions contain one region from each antipodal pair, so . The lune at each vertex consists of and one of these adjacent regions. Therefore, if the three interior angles are ,which proves the spherical excess formula, the spherical-triangle form of the Gauss-Bonnet theorem:For a sphere of radius , multiply this area by .
Triangulate a convex spherical -gon by diagonals from a vertex. There are spherical triangles, and their angles add to the polygon's interior angle sum. Thus its unit-sphere area isFor a nondegenerate convex regular polygon in an open hemisphere, area is positive and each angle is less than , giving . Every angle in this interval occurs. Indeed place vertices at equal longitude spacings and colatitude about a pole, and join consecutive vertices by shorter great circle arcs. The polygon is convex and regular. Split a central isosceles spherical triangle along the perpendicular to its edge. The resulting right spherical triangle has angles , , , and hypotenuse . The angular spherical law of cosines yieldsso . As increases from to , increases continuously through exactlyThe endpoints are degenerate limits, not strict convex polygons.
For the spherical triangle reflection group, positive area requires . Each angle is less than , so the integer denominators are at least two. Arrange . If the sum is at most one, hence . If the sum is again at most one; thus either and any works, or and . These triangles exist, for example as the reflection chambers of a regular dihedral configuration, tetrahedron, cube, and dodecahedron, respectively.
To count group elements using the assumed tessellation, first label the original triangle's three vertices by their types and propagate these labels through side reflections. Around a type- vertex there are sectors; the associated alternating reflections make a full turn and return the labels unchanged. The same holds at the other types. Every closed path in the dual tessellation is generated by these circuits around vertices, since the sphere is simply connected. Thus the labels are globally consistent, including when two angle denominators coincide. Every generated isometry preserves these labels. An element stabilizing a triangle therefore fixes its three vertices and is the identity. Consequently group elements correspond bijectively to triangles, and area givesThe possibilities, including permutations of the entries, are
Here is an explicit dodecahedron construction for the last case, avoiding an assumption about which vertices of the tessellation to join. Put , and take the convex hull of the twenty pointswith independent signs. They all have squared radius three. The supporting plane contains the five verticesin cyclic order. Consecutive distances are , and nonconsecutive distances are , so this is a regular pentagon. Changing the two signs in its normal and cyclically permuting coordinates gives twelve supporting planes, all with a congruent pentagon. Each listed vertex lies on three of these faces; the sixty face-edge incidences pair into thirty edges. The faces form a closed convex polyhedral surface with , hence exhaust the boundary of the convex hull. This constructs a regular dodecahedron.
Choose the spherical directions of a face center , the midpoint of its edge between , and that edge's endpoint . Normalize these to the unit sphere. The three side planes of triangle are , , and with . Their reflections are coordinate sign changes in the first two cases andin the third, since . Substitution in the twenty listed vertices, using , shows that all three reflections permute the vertex set. The side-plane angles give interior angles at , at , and at because and . Thus this triangle is congruent to , and its side-generated group is , conjugated by the aligning isometry.
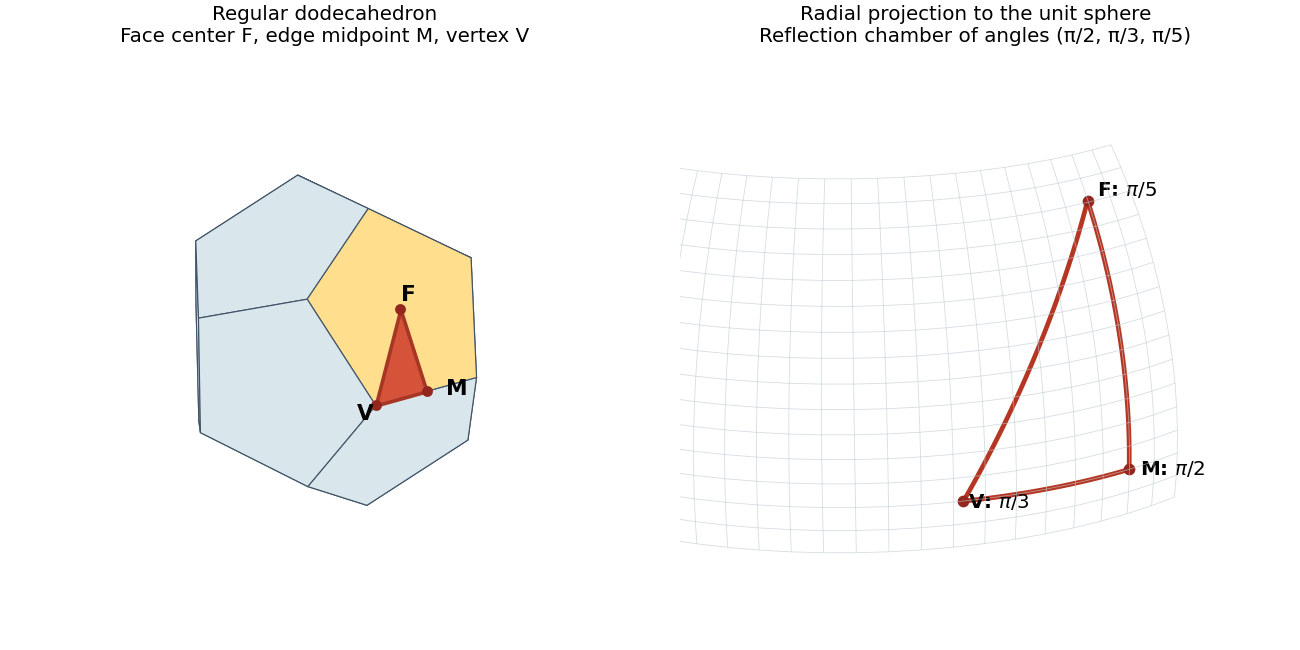

It already has elements. Conversely, a symmetry of the dodecahedron is determined by the image of one face, one vertex on that face, and the orientation along its boundary: there are at most choices. An isometry fixing these choices fixes that face pointwise and must preserve the polyhedron's interior side, hence is the identity. Therefore the complete symmetry group of the constructed dodecahedron is , including orientation-reversing symmetries.
A balanced transportation problem chooses nonnegative shipments minimizing , subject to and , where the total supply equals total demand. For multipliers , its Lagrangian isTaking its infimum over produces the linear programming duality problem of maximizing subject to . These are the transportation dual potentials.
The transportation simplex algorithm starts with a feasible transportation spanning tree of basic entries, obtainable by filling the north-west available cell with the smaller remaining supply or demand. Set on basic cells; this determines all potentials up to adding a constant to all and subtracting it from all . If all nonbasic reduced costs are nonnegative, feasibility and the dual bound prove optimality. Otherwise let a negative-cost cell enter. It closes a unique cycle in the basic tree. Alternate additions and subtractions around that cycle and choose the largest amount preserving nonnegativity, namely the minimum shipment on the subtraction cells. A cell that reaches zero leaves the basis. The cost changes by the entering reduced cost times the pivot amount. Zero basic cells and an anti-cycling rule can handle degeneracy; all pivots below are nondegenerate.
The north-west initial shipment matrix isWith , its transportation dual potentials are and . The most negative reduced cost is . The cycle is ; the pivot amount is . HenceNow and . Enter , of reduced cost , on cycle . The amount is , givingThe new potentials are and . Enter , of reduced cost , on cycle . The amount is . ThusTo certify optimality in the original transportation problem, take and . Their entire reduced-cost matrix isThey satisfy dual feasibility, and their value is , equal to the shipment cost. The minimum transportation cost is therefore , with no unproved optimality assertion from the iterations alone.
Repeated differentiation of the Gaussian function gives , where and . Induction shows has degree of a polynomial and leading coefficient : the differentiated term has lower degree, while multiplication by raises it by one. Thus the Hermite polynomial has degree and leading coefficient .
For , apply integration by parts times to the Rodrigues expression:All boundary terms vanish because each derivative of is a polynomial times that exponential, and such products tend to zero at either infinity. The same result for follows by symmetry of the inner product. The diagonal value is positive; indeed givesThis proves the requested orthogonality as well as its normalization.
Differentiating the Rodrigues representation directly gives the identityWe prove simultaneously by induction that for . It holds for , . Suppose it holds at . Differentiating the preceding identity and using the same identity at givesThe induction is complete. Substituting the derivative identity into the first formula proves the Hermite polynomial three-term recurrence relationThe initial step supplies the recurrence at without needing to define .
Use the Leibniz definition of the determinant:For the permuted-column matrix, . Reindex the sum by . The sign of a permutation is multiplicative, so . It follows directly thatFor the matrix transpose, the products in its determinant are . Set to obtain , and use . This proves . These facts also show that equal columns, or equal rows by transposition, force the determinant to be zero: exchanging the equal pair leaves the matrix unchanged but changes the determinant's sign.
Let be the matrix obtained by deleting row and column , with the empty determinant taken as one for . Define the cofactor and the adjugate matrix by . Grouping the Leibniz sum according to the column chosen in row gives the cofactor expansion : deleting that row and its chosen column leaves a permutation of entries, with sign factor . ThereforeWhen this is . When it is the cofactor expansion along row of the matrix formed by replacing that row with row ; its remaining minors are unchanged, and its two equal rows give determinant zero. The column version proves the other product in the same way. Thus the adjugate identity is
For the real matrices , let . The determinant definition makes this a real polynomial of degree of a polynomial at most . Since is invertible, the allowed converse implies , so is not the zero polynomial. It has at most real roots of a polynomial. Choose a real outside those roots; the adjugate argument proves that is invertible.
Finally write the given complex similarity transformation as . The relation , with real, yields and by comparing real and imaginary parts. Choose the preceding and put . Then , soThis proves real similarity from complex similarity by constructing a real intertwiner, rather than requiring or separately to be invertible.
For an inviscid flow that is an incompressible flow and an irrotational flow, write . The Euler equations for an inviscid fluid, without gravity, integrate spatially to the Unsteady Bernoulli equationA time-dependent addition to can absorb .
In the ideal uniform tube-plug model, let be the axial speed toward the outlet. Incompressibility and fixed cross-section make the speed the same at both ends. With , the kinetic terms cancel when the Unsteady Bernoulli equation is subtracted between entrance and exit, givingConservation of volume in the spherical balloon gives , or . Differentiating and eliminating yieldsThis is the constant-tension balloon discharge equation; entrance losses and a reservoir-to-tube kinetic-head correction are excluded by this ideal plug model.
Multiplication by turns the equation intoThe printed time formula additionally assumes the water is initially at rest, , although only is explicitly specified in the question. Under that assumption . On the shrinking branch,Set and . The integral becomes , hencePutting , or , gives the ideal emptying timeFor an independently prescribed initial rate , the first integral instead has , so radius alone does not determine that emptying time. This explicitly identifies the extra initial datum needed for the displayed answer.
For any idempotent linear map , each vector decomposes asIf , write ; then . Thus the kernel of a linear map and image of a linear map give a direct sum.
For the self-adjoint map in the question, and satisfy . Hence the direct sum is an orthogonal decomposition:
For a normal operator , the adjoint operator identity and givePositive definiteness implies . Also , since orthogonality to every means for every . In finite dimension this gives .
The idempotent linear map decomposes as in part (a), now orthogonally, and acts as zero on its kernel and identity on its image. Writing and in these orthogonal summands,Thus is self-adjoint, and together with idempotence this proves is an orthogonal projection.
The finite-dimensional inner product space has the orthogonal decomposition . Define for , . This is a linear map with image , satisfies , and is self-adjoint by taking inner products between decomposed vectors. Hence it is an orthogonal projection.
Any other orthogonal projection with image has kernel by part (a); it is identity on by idempotence and zero on its kernel. Its values are therefore forced to agree with , proving uniqueness.
Take any positive definite inner product on and define the inner product adapted to an idempotent linear mapIt is symmetric and bilinear. If its quadratic value at is zero, positive definiteness of the original inner product forces both and , hence . Thus it is positive definite.
Using and givesThe map is therefore self-adjoint for this new inner product and remains idempotent, so it is an orthogonal projection for the explicitly constructed inner product. Geometrically the construction makes its complementary kernel and image orthogonal.
The time-independent Schrödinger equation is , with attractive Coulomb potential , where . Separating uses the spherical harmonic angular eigenvalue of the unit-sphere Laplacian. The radial kinetic contribution is , the angular kinetic contribution is the centrifugal term , and the remaining term is the attractive potential energy. The right side is the energy eigenvalue times the radial wavefunction. Here the stated neglects nuclear recoil; including it replaces the electron mass by the reduced mass.
For , substitution of the ground-state exponential givesIts coefficient must vanish and its constant coefficient determines the energy, soHere is the Bohr radius.
For , direct differentiation yieldsCancel the nonzero exponential in the radial Schrödinger equation and compare coefficients of , the constant term, and . They give, respectively,ConsequentlyThe positive decay constants ensure normalizability; the second radial wavefunction has one positive-radius node at , as appropriate to the first radial excitation.
If the entire energy gap is carried by one photon, neglecting atomic recoil, conservation of energy gives the requested frequencyThere is a physical qualification: these are the and states, so the usual single-photon electric-dipole transition is forbidden by the electric-dipole selection rules for hydrogen. Explicitly, both angular factors are , and , so every component of vanishes. The leading isolated-atom decay is instead two-photon emission, for which and individual frequencies are not fixed. This metastability and the two-photon channel are documented in NIST's hydrogen spectral-data compilation. Thus the boxed answer is the energy-gap frequency under the printed single-photon assumption, rather than an assertion of an allowed electric-dipole line.
Articles by others on the same topic
There are currently no matching articles.