Two square matrices are similar when for some invertible matrix . A Jordan normal form is a block-diagonal matrix whose blocks have one eigenvalue on the diagonal, ones on the superdiagonal, and zeros elsewhere; over an algebraically closed field every matrix is similar to such a form, unique up to reordering its Jordan blocks.
Both displayed matrices have characteristic polynomialHowever,so their eigenspace dimensions are respectively two and one. Thus has Jordan form , whereas has Jordan form . By uniqueness of Jordan normal form,
For an oriented smooth embedded surface, the Gauss map sends each point to its chosen unit normal. This surface is the ring torus with major radius two and minor radius one. Its outward Gauss map isOn the cross-section, the normal points radially away from the center of each generating circle, which gives this formula for and then rotational symmetry gives it for all .
The upper hemisphere condition is , hence . For this torus, the Gaussian curvature and area element areTherefore the positive outer and negative inner contributions cancel:
The boundary arcs meet at and . The Möbius transformationsends these points to and infinity, sends the real boundary segment to the positive real axis, and sends the circular boundary arc to the ray of argument . Hence it maps onto the sectorThe power maps this sector conformally onto the lower half-plane. Finally, the Cayley map maps the lower half-plane onto the unit disc. Thus a requested conformal equivalence is
An operator is Hermitian whenon its domain. Hermitian operators represent quantum observables because their expectation values and eigenvalues are real. In a normalized state,
Positivity of the norm of for every real givesThe middle expectation is real because is Hermitian. The discriminant of this quadratic is nonpositive, soApply this to the centered operators and , whose commutator is still . This yields the Robertson uncertainty principleNoncommuting observables therefore cannot both have arbitrarily sharply concentrated measurement distributions in the same state.
Gaussian elimination gives the LU decompositionThe prescribed diagonal entries of are visible, and direct multiplication gives .
First solve by forward substitution:Then solve by backward substitution, obtainingDirect substitution verifies .
The likelihood contributes precision and precision-weighted mean , while the prior contributes precision and precision-weighted mean . By normal-normal conjugacy with known observation variance, the posterior isThus the posterior mean isWhen , its expectation under true parameter is and its variance is . Hence its frequentist mean squared error is
Write the absolute-value constraint asIntroduce slacks . In the simplex algorithm, let enter and leave, then let enter and leave. The final dictionary isThus
For sufficiently small perturbations, the same two constraints remain active:Solving givesand therefore the perturbed optimal value is
The rank of a matrix is the dimension of its column space, equivalently the dimension of the image of a linear map represented by the matrix. For , the rank-nullity theorem givesAn injective endomorphism of a finite-dimensional vector space is surjective, hence invertible. By the adjugate matrix identity is invertible when ; conversely, multiplicativity of the determinant shows that an invertible has nonzero determinant. Therefore
Let be the matrix unit with its only nonzero entry at . The following matrices are all nonsingular:Indeed, is an elementary shear when , while is diagonal with one diagonal entry equal to two. Their linear span contains every except initially , because , and it then containsThus spans the -dimensional space and, having members, is a basis. This also covers , when .
Now let be a nonsingular zero-one matrix. If it had fewer than zero entries, at least two rows would contain no zero at all. Those two rows would both be the all-one row, contradicting linear independence. Hence every such matrix has at mostones. The bound is attained. Let be the all-one matrix and setwhere there are initial diagonal ones. If and , the first row equations give , while the last gives . Hence every , so is nonsingular and has exactly ones. Therefore
The structure theorem for finitely generated modules over a principal ideal domain applies because every Euclidean domain is a principal ideal domain. It says that a finitely generated -module is isomorphic towhere the nonzero nonunits are unique up to multiplication by units. They are the invariant factors.
For , multiplication by is the linear map . Since is finite-dimensional over , is a finitely generated torsion module over the polynomial ring , so it has no free summand. Choosing each invariant factor to be monic givesThe basis of each cyclic summand makes multiplication by a companion matrix. Concatenating these bases therefore puts in rational canonical form.
On , a polynomial annihilates multiplication by exactly when it is divisible by . It follows that the minimal polynomial and characteristic polynomial areThe second identity follows blockwise from the characteristic polynomial of a companion matrix. Since every divides , the product annihilates every cyclic summand. Thus , which is the Cayley-Hamilton theorem.
For the displayed matrix, the given generators of are the columns ofElementary row and column operations over give the Smith normal formConsequently the nonunit invariant factors areand, as a check,
A function is differentiable at if there is a linear map such thatThe map , which is unique, is the derivative .
The inverse function theorem states that if is continuously differentiable near and is invertible, then restricts to a bijection between neighbourhoods of and ; its local inverse is continuously differentiable, with derivativeIn the normalized case and , continuity of gives a closed ball on whichFor small , define . The mean value inequality makes a contraction mapping with constant . If , thenso maps the ball into itself. The contraction mapping theorem gives a unique fixed point , and the fixed-point equation is precisely . Moreover,so . Thus is a continuous local inverse.
For the polynomial map in the question,The derivative is invertible, so the inverse function theorem supplies some and a continuously differentiable such thatThere can be no inverse on all of , becauseso is not injective.
The curve is symmetric in both coordinate axes and under interchange of and . Its shape, including its eight inflection points, is:
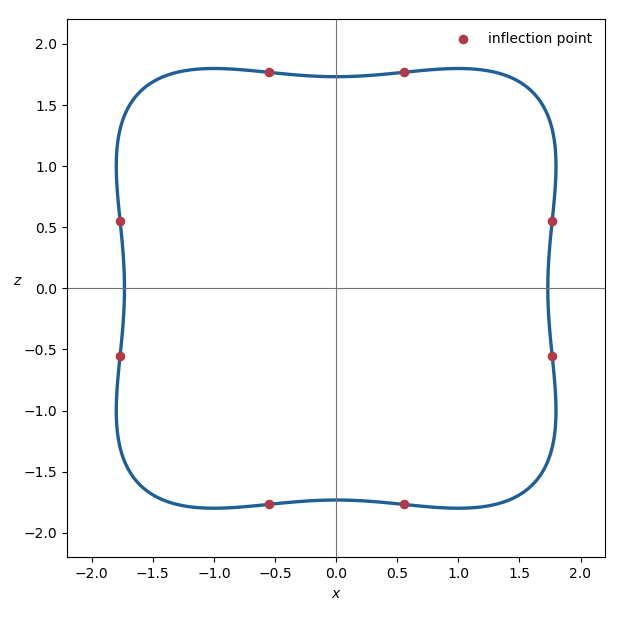
Writing , the surface of revolution has equationLetIts gradient isIf this vanished, then and , but at such a point , not five. Hence zero is a regular value, and the regular level set theorem shows that is a smooth embedded surface.
For a surface of revolution, the two principal curvatures are the curvature of the meridian and the normal curvature of a parallel. Along ,so the normal is vertical in the meridian plane and the parallel principal curvature vanishes. Therefore the Gaussian curvature, the product of the principal curvatures, is zero there.
These are not the only zero-curvature points. The meridian itself has inflection points, at which its principal curvature vanishes. Setting and , their positive squared coordinates satisfyBesides interchanging and , the solution is approximatelyEach corresponding meridian inflection point sweeps out another circle on , so does not exhaust the zero set of the Gaussian curvature.
An analytic branch of a square root determined by the branch isIf and are two such branches, their ratio is analytic and satisfies . Since a domain is connected and takes values in the discrete set , is constant. Thus throughout or throughout .
For , the principal square root isOn , one may instead takeThe respective removed half-axes are their branch cuts.
On , defineIt is analytic there, its square is , andso it is the required branch. Substitution gives, for ,The binomial series yieldshence the first three terms of the Laurent series are
Sinceits residue at zero is . Under the change of variable , the two orientation reversals cancel, and the residue theorem gives
In polar coordinates,With the change of radial coordinate , the detection functional becomesIt is therefore times ordinary path length in the -plane. The shortest path is the line segment from to , soReturning to gives the logarithmic spiralIts minimum detection probability isThe functional depends only on the geometric path and not its parametrization, so tiptoeing and running give the same probability.
For the improved sensor, omit the irrelevant positive factor and use the LagrangianThe coordinate is cyclic, so its conjugate momentum is conserved. Equivalently,is constant. Because has no explicit time dependence, the associated conservation of energy gives the constantMultiplying by and using gives the required equation
Expand in its Fourier sine seriesBy separation of variables, the decaying solution of Laplace equation in each half-strip has th mode proportional to . Continuity at and integration of the equation across the Dirac delta function require the normal-derivative jumpThe jump of is , so
For , its Fourier coefficients areThusTranslation in gives the Dirichlet Green function for an infinite strip with source :
A stationary state has the formFor a time-independent quantum observable , the global phases cancel in the expectation value:It is therefore independent of time.
For the infinite square well,The possible energy measurement results arewith respective Born rule probabilities and . Normalization gives .
The electric potential of a point charge at the origin isFor the two charges forming the dipole,The first-order Taylor expansion at large isand therefore, with the electric dipole moment ,to leading order. Taking the interaction of a second dipole with the corresponding electric field gives the stated electric dipole-dipole interaction
Let the lattice spacing be and write the central dipole asIts two horizontal neighbours have moment . For either one, the expression in parentheses, after extracting , isIts two vertical neighbours have moment , and each contributes insteadAdding all four nearest-neighbour interactions and using the Pythagorean trigonometric identity givesThe angle has cancelled, so the energy is independent of .
For a velocity potential, . The incompressible flow condition therefore becomes Laplace equation . The Laplace equation in polar coordinates givesso positivity of and requiresThe velocity components areThe no-penetration boundary condition on both walls says at and , hence . If , changes sign inside the wedge. The stated sign condition therefore selects , and
A streamline satisfiesIntegration givesThe radius is smallest on the wedge bisector , where . Labelling that radius by therefore givesEvery streamline arrives from infinity along one wall, reaches its closest point on the bisector, and returns to infinity along the other wall:
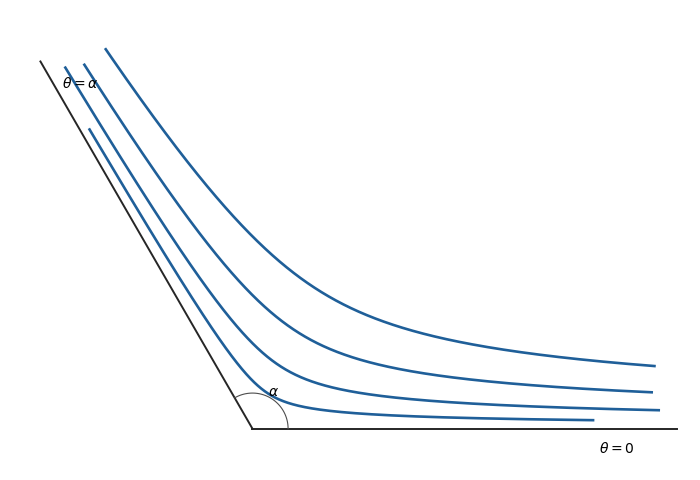
Using and the Pythagorean trigonometric identity,so the speed is independent of . Since ,and the speed tends to zero at the vertex. The steady irrotational Bernoulli equation givesThus the fluid pressure is also independent of , withIn particular, the pressure difference between the vertex and is
Define the cardinal polynomialsThey satisfy . Hence evaluating the proposed polynomial interpolation formula at gives , so the required coefficients areThe polynomial has degree at most and takes every prescribed value. Its uniqueness follows because the difference of two such polynomials would have distinct roots while having degree at most .
For fixed interpolation nodes , interpolate any asIntegrating shows that the unique weights making the quadrature rule exact through degree are
Now let the nodes be the zeros of the degree- orthogonal polynomial . Given any , polynomial division givesOrthogonality gives , while makes the quadrature sum for vanish. The rule is already exact on , so it is exact on . This is the defining precision property of Gaussian quadrature.
The displayed Rodrigues formula gives the Legendre polynomialA four-node Gaussian rule is exact through degree . Solving first for gives the four nodesThe rule is not exact for every polynomial of degree eight: its quadrature value on is zero because every node is a root of , whereas
Let . The likelihood function isOn its feasible range , this is decreasing in . Therefore the maximum likelihood estimator is
A statistic is sufficient for if the conditional distribution of the full sample given does not depend on . It is minimal sufficient if it is a function of every sufficient statistic.
The likelihood factors asso the Fisher-Neyman factorization theorem shows that , and hence its one-to-one transform , is sufficient. Moreover, for two samples and , the ratio is independent of exactly when their maxima agree. The likelihood-ratio criterion for minimal sufficiency therefore shows that and are minimal sufficient.
For , the sample mean is not sufficient: two samples can have the same mean but different maxima, and their likelihood ratio then depends on through the support indicators. It is consequently not minimal sufficient. For the degenerate special case , the sample mean and maximum coincide and both conclusions reverse.
The scaled maximumhas cumulative distribution function for . ThusThe mean squared error of the maximum likelihood estimator is therefore
Each from the uniform distribution on has mean and variance . The sample mean is unbiased and has variance , hence
Because , for fixed and sufficiently large ,ThereforeEquivalently, converges in distribution to an exponential distribution of rate one.
Put . The limiting probabilityand the certain inequality suggest the approximate confidence intervalSince , its expected length isas required.
A random time is a stopping time for the natural filtration of a Markov chain when for every . The Strong Markov property says that, conditionally on and , the process after is a fresh copy of the chain started from , independent of the pre- history.
Before capture define the half-separationFor , independence of the two moves gives the transition probabilitiesIgnore the holding steps. The resulting embedded chain is a biased random walk that moves left with probability and right with probability . Its expected number of moves needed to descend one level is ; this follows either from first-step analysis or from its drift . A non-holding move occurs with probability at each time, so its mean waiting time is two. Hence, for every , the expected time to go from separation to is
Let be the expected capture time starting from , so . The Strong Markov property at successive first passages to lower levels and part (a) giveAt , the next state is zero with probability , one with probability , and two with probability . First-step analysis therefore givesorSolving,Substituting now yieldswhich is the required expected capture time.
Fix . If , then normality of givesThus the transitive group action of permutes the orbits of a group action of , so all -orbits have the same cardinality . They partition the prime-sized set , hence divides . The only possibilities are and . The first would make every element of fix every point, contrary to the assumption that acts nontrivially. Therefore and
Now suppose . Define the orbit mapIt is surjective by transitivity of . If , then , so ; hence is bijective. For ,Thus is an equivariant map: conjugation by on corresponds exactly to the given action of on .
Write . The zero and constant-one polynomials give and . Also,so is closed under finite intersections. Every nonzero one-variable complex polynomial has only finitely many roots, and every finite subset is the zero set of . Consequently is exactly the cofinite topology: its open sets are the empty set and the complements of finite sets. An arbitrary union of such sets is again empty or has finite complement, so is a topology.
The product topology on is the topology with basisThe proposed complement need not be open. TakeThen is the diagonal. If its complement were open, a point such as would have a basic neighbourhood contained in that complement. But and are nonempty cofinite subsets of , so . For , the point belongs both to and to the diagonal, a contradiction. Hence
Because the constraint determinesthe constrained function isIts stationary points satisfyWhen , these equations giveWhen , subtracting the two bracketed equations gives , and substitution then giveswith the two signs chosen independently. These are exactly the constrained stationary points; equivalently they follow from the Lagrange multiplier equations.
Under the additional restriction , the constraint gives the compact elliptical disc . On its boundary , the objective is zero. At the four nonzero interior stationary points,with the sign determined by . Therefore
The convolution theorem states, for this convention, thatSince , it follows thatagain interpreted continuously at , where .
Let be distance from the common centre. By Gauss's law, the electric field is radial and equalsTaking the electric potential to vanish at infinity and requiring continuity across each shell gives
The electrostatic energy is the integral of the electric-field energy density:Only the two nonzero-field regions contribute, soTherefore
Let the upper plate in flow A move at speed , with the lower plate fixed. The Couette flow profile isso its mid-plane speed is and its total viscous dissipation per unit plate area is
Write for the constant pressure-gradient magnitude in flow B. The plane Poiseuille flow profile isEquality of the mid-plane speeds givesSince ,Hence
SetConditioning on gives the affine recurrenceIts fixed point is the first component of the stationary distribution,Thus , and gives
Starting instead from state two gives the same recurrence with initial value zero. Therefore
An endomorphism is a projection onto its image precisely when it is the identity on and kills a complementary subspace. If , thenso is the identity on its image. Moreover,and . Henceand is the projection onto its image along its kernel. Conversely, every projection is the identity after one application, so applying it twice has the same effect: .
Statement (i) is false. On a two-dimensional vector space, take the nonzero nilpotent endomorphismThen , but , so is not idempotent.
Statement (ii) is false. The condition is necessary for an idempotent, but it is not sufficient. For example,satisfies , hence , whileover, for example, .
Statement (iii) is false over an arbitrary field. Expanding the assumed idempotence givesMultiplying this relation on the left and right by showsThus , so the conclusion would be true in characteristic different from two. In characteristic two, however, take . Then , , and are idempotent, but .
Statement (iv) is false because need not imply . For example, over any field takeBoth maps are idempotent and , butConsequently
Gauss lemma for polynomials states that the product of two primitive polynomials over a unique factorization domain is primitive. In particular, a primitive polynomial in is reducible over exactly when it is reducible over .
Eisenstein criterion says that a primitive polynomialis irreducible over if there is a prime such that , for every , and . To prove it, suppose with both factors of positive degree. After removing contents, Gauss's lemma lets us take primitive. Reduction modulo givesso both reduced factors are monomials of positive degree. Their constant terms are therefore divisible by , making divide , a contradiction.
An algebraic integer is a complex number satisfying a monic polynomial in . Let be one and let be its monic minimal polynomial. The usual proof using polynomial content shows that . The setis the kernel of the polynomial-evaluation ring homomorphism, hence an ideal. Every is divisible by in . Because is monic, polynomial division of by takes place in , and the remainder must vanish by minimality. Thereforewhere is monic and irreducible.
Fortranslation givesThis is Eisenstein at , so and therefore are irreducible over . HenceIrreducibility and Gauss's lemma also show that is a prime ideal of , soIt is not a field. The class of is nonzero but not a unit: reducing further modulo gives a nonzero quotientin which the image of is zero, whereas a unit must remain a unit under every unital quotient map. Thus
HereThe L1 norm and uniform norm satisfyso the identity from the metric to the metric is one-Lipschitz and therefore continuous. The two metrics do not induce the same topology on all of . Forone has but . Thus convergence need not imply uniform convergence.
Choose distinct and defineThe Vandermonde determinant is nonzero, so is a bijection. It is one-Lipschitz for the two uniform metrics. If are the associated Lagrange cardinal polynomials, thenand henceThus is also Lipschitz.
Let be the polynomials whose values lie in . Its image under lies in the bounded cube . It is closed: if , then the Lipschitz inverse gives uniform convergence , and passing to the limit pointwise preserves . By the Heine-Borel theorem, is compact, and the continuous inverse carries compactness back to . Therefore
The identity mapis a continuous bijection by . Its domain is compact by part (i), and its codomain is a Hausdorff space because every metric space is Hausdorff. The compact-to-Hausdorff continuous bijection theorem therefore makes the identity a homeomorphism. Consequently
For a continuously differentiable curve in the Poincare half-plane model, its hyperbolic length isThe hyperbolic lines are the geodesics: vertical Euclidean lines and Euclidean semicircles whose centres lie on the real axis.
The unique hyperbolic line through distinct can be carried by an upper-half-plane Möbius transformation to the imaginary axis. Such transformations are isometries by hypothesis, so it is enough to consider endpoints and . Every joining curve satisfiesEquality holds for the monotone vertical parametrizationThus the appropriately parametrized hyperbolic-line segment attains the infimum defining .
Now let have positive infimum distance. They neither intersect nor share an ideal endpoint: an intersection would give distance zero directly, while lines sharing an ideal endpoint approach one another arbitrarily closely near that endpoint. Hence they are ultraparallel. An upper-half-plane isometry puts them into the formThis is the normal form underlying the common perpendicular of ultraparallel hyperbolic lines. Put . Sincethe metric becomesEvery path from to therefore hasEquality requires and monotone , so it is attained on the imaginary axis, which meets both semicircles orthogonally. Its intersection points and realize the distance
For a nonattained example, take the vertical lines and . They share the ideal endpoint at infinity. The horizontal segment at height has hyperbolic length , so their infimum distance is zero, but distinct points of always have positive distance. Hence the infimum is not attained.
Articles were limited to the first 100 out of 146 total.
Articles by others on the same topic
There are currently no matching articles.