How much information about a shape do we need to keep? Euclidean geometry retains lengths and angles, allowing questions about the diagonal of a rectangle or the shortest route between two points. Topology retains the structure preserved by a homeomorphism, allowing questions about connectedness and whether a loop can shrink to a point, as recorded by the fundamental group. These are different levels of description of the same object.
For example, stretching a circle horizontally produces an ellipse. The stretching map and its inverse are continuous maps, so it gives a homeomorphism: the two curves have the same topology. It changes some Euclidean distances, however, so it is not an isometry. This distinction helps separate essential structure from a particular drawing, while explaining why measuring a shape requires more information than recognizing its topology.
The choice of geometry matters too. A Euclidean geometry triangle has interior angles summing to , but a spherical triangle can have three right angles. Spherical geometry turns this apparent surprise into a measurement: the excess of the angle sum over determines the area. Begin with the Pythagorean theorem for flat measurements, then compare the spherical triangle below to see curvature change the rules.
The initial table of content was limited to the first level because it is larger than 1000 articles. There are 5615 articles in total. Expand a branch to load its children.
A component function of a local coordinate chart on a smooth manifold. Its differential belongs to the coordinate cotangent space basis.
A cylinder is generated by translating a plane curve along parallel lines transverse to its plane. A circular cylinder uses a circle as its generating plane curve; it is right when the generators are perpendicular to that plane. The term can denote the lateral surface or, for a bounded portion with end caps, the enclosed solid. The circular cylinder curvature formulas describe the smooth lateral surface.
For a smooth surface obtained by translating the plane graph along the direction, the induced metric is . The transverse arc length coordinate makes it . This is a local isometry to the Euclidean plane, extending the intrinsic flatness of a circular cylinder to arbitrary smooth generating graphs.
Its geodesics therefore lift to straight lines in coordinates. Those that are graphs over satisfy , while the additional family cannot be written as . The same graph formula follows from the Beltrami identity for the arc-length integrand . These straight lines are locally minimizing; on cylinders with a closed generating curve, global identifications can create several different winding paths between two points.
A closed circular cylinder of radius and length has volume and total surface area , including both end disks. At fixed area , Lagrange multipliers for maximizing the volume give , henceEquivalently, eliminate and maximize on . The derivative changes from positive to negative at the displayed radius, and the volume tends to zero at both ends.
For a cylinder inscribed in a sphere of radius , the constraint is . Maximizing by Lagrange multipliers gives , so the positive aspect ratio is . It is independent of . With , the area is ; differentiating this expression confirms the unique maximum on .
A parametric equation expresses coordinates as functions of one or more independent parameters. For example, , describes a circle; multiple parameters describe surfaces. A smooth curve is a differentiable single-parameter realization. A reparametrization changes the parameter without changing the geometric image.
The domain of a function used by a parametrization is its parameter domain. A parametrized surface may require several such domains, and duplicated images must be accounted for in a surface integral.
An embedding identifies one mathematical structure with a structure-preserving copy inside another. In topology it is a homeomorphism onto its image with the subspace topology; an algebraic embedding is an injective homomorphism. A smooth embedding additionally has injective differential everywhere, so its image is an embedded submanifold.
A pencil is a one-parameter linear family of geometric objects. For linearly independent homogeneous polynomials of equal degree, , indexed by , is a pencil of plane curves or hypersurfaces. Lines through a fixed point give a simple example; a pencil of plane curves specializes the general construction.
Spherical geometry studies lengths and angles measured along the surface of a sphere, rather than through its interior. It is a useful model whenever travel is constrained to a round surface. Its straightest paths are great circle arcs: they are geodesics, even though they appear curved in the surrounding Euclidean space. Two distinct great circles meet at an antipodal pair, so the parallel-line picture of Euclidean geometry does not apply.
For a sphere of radius , write two positions as , with unit vectors. Their shorter surface route has great-circle distancewhere the dot product gives the central angle in radians. The straight chord through the surrounding Euclidean space instead has length . For a quarter-circle separation these are and : specifying which distance we mean has a measurable effect. On the unit sphere, and great-circle distance equals the central angle.
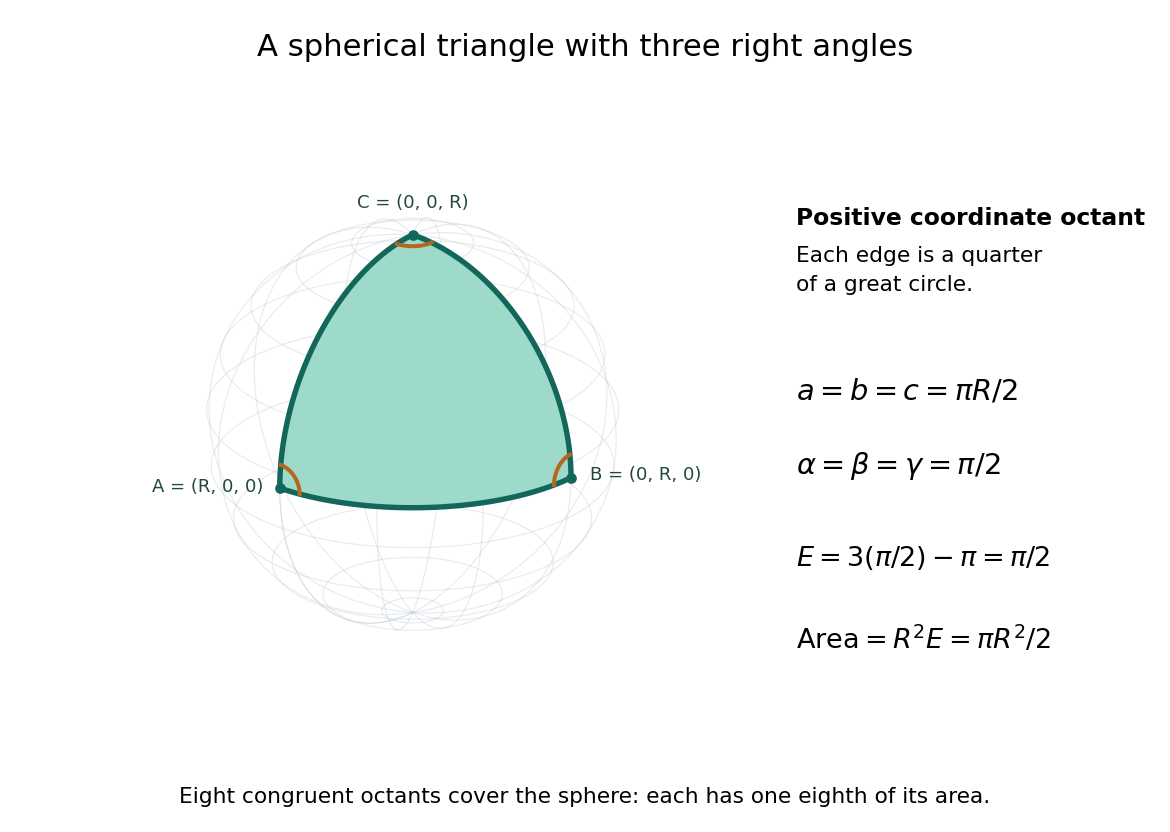
Consider the spherical triangle with vertices , and , joined by the shorter great circle arcs. Each side has length . At each vertex the two outgoing tangent vectors point along the other coordinate axes and are orthogonal, so all three interior angles are . This is the positive coordinate octant of the sphere, not a flat triangle drawn inside it.
For a convex minor spherical triangle with interior angles in radians, the spherical excess formula statesOur octant therefore has area . Independently, eight congruent octants partition the sphere, giving again. Thus angles alone determine area when is fixed, unlike Euclidean geometry, where similar triangles can have arbitrarily different areas. The Gauss-Bonnet theorem explains the connection: the sphere's constant Gaussian curvature times the area equals this excess. For spherical triangles whose area is small compared with , the excess is small, recovering the familiar flat picture.
A nondegenerate convex regular spherical -gon contained in an open hemisphere has equal interior angles in the displayed interval. The spherical excess formula gives area . Conversely, put equally spaced vertices at colatitude around a pole. Dividing each central triangle in half gives by the spherical law of cosines. As increases, the angle ranges continuously from the Euclidean limiting angle to .
On a sphere of radius , a spherical circle of radius is the locus at spherical distance from its center. Its polar angle about that center is , so parametrization by longitude has speed . Its circumference is therefore . For small , this is , with the deficit determined by the sphere's positive Gaussian curvature.
A spherical lune is the region between two great semicircles joining antipodal points. On a unit sphere a lune of opening angle has area , obtained by integrating area over longitude width . Lune area counting yields the spherical excess formula.
For points on a sphere of radius , write their position vectors relative to the centre as with unit vectors. The great-circle distance is the shorter great circle arc length, times its central angle. Hence it equals , including zero for identical points and for antipodal points. At antipodal points the shortest arc is not unique, but its length is.
Spherical trigonometry calculates the sides and interior angles of spherical triangles using trigonometric functions. Its sides must be shorter great circle arcs, which are geodesics on a round sphere. A curve at constant nonzero latitude does not qualify. The spherical law of sines and spherical law of cosines play the roles of the familiar flat-triangle rules, but account for the sphere's curvature.
Use uppercase both for the vertices and for their interior angles, and lowercase for the opposite angular sides. For example, is the central angle subtended by the arc from to . On a sphere of radius , its physical arc length is when is in radians; similarly and . Only on the unit sphere do the angular and physical side lengths have the same numerical values. See J. B. Tatum, Celestial Mechanics, chapter 3, section 3.5: great-circle sides and angular units.
One useful application of spherical trigonometry is finding great-circle distance from spherical coordinates. Write a unit vector as , where is latitude and is the equatorial azimuth, or longitude, measured from a chosen reference direction. The dot product of two such unit vectors givesHere is the central angle and is the great-circle distance. The same identity follows from the spherical law of cosines by adding the north pole as the third vertex, with angular sides and . This connects spherical geometry to position calculations in astronomy and to navigation on a spherical model of Earth. Choosing the surface model matters: Paula Neeley and Anthony Narkawicz, Map Projection Induced Variations in Locations of Polygon Geofence Edges, NASA/TM-2017-219675 (2017), sections 2-3 distinguishes spherical and ellipsoidal geodesics and gives this coordinate identity.
For a toy example, put two points at latitude , with equatorial azimuths and . The great-circle distance and the arc length along constant latitude areThe great circle takes a shorter route by bending towards the pole in these spherical coordinates. To locate its highest latitude, the endpoint unit vectors are and . Their great circle lies in the plane through the origin with . On its shorter arc, the maximum latitude occurs at and is . Thus a geodesic can change latitude substantially even when its endpoints have equal latitude. These are lengths on an ideal sphere; the example illustrates the geometry rather than specifying an actual flight route.
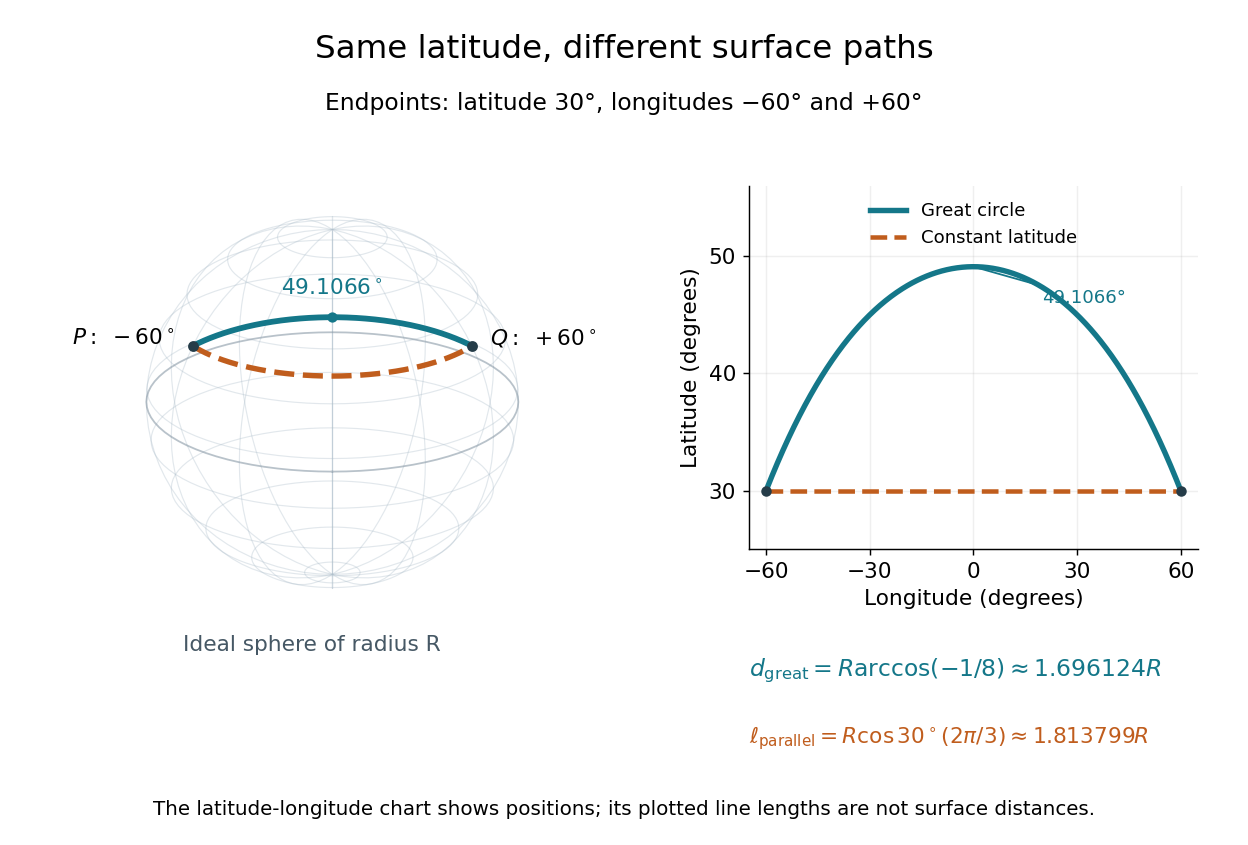
On an ideal sphere, two points at latitude and longitudes are joined by a shorter great-circle arc reaching latitude
. Details. Historically, spherical trigonometry was prominent in teaching as well as in astronomy. John Conway and Alex Ryba note its presence in early twentieth-century school textbooks in Remembering spherical trigonometry, The Mathematical Gazette 100(547), March 2016, pages 1-8, DOI 10.1017/mag.2016.3. Their introductory observation documents that teaching history; it does not identify a single inventor of the spherical law of sines or spherical law of cosines.
For a nondegenerate convex minor spherical triangle, with angular sides opposite interior angles , the spherical law of sines statesThe sines of sides refer to central angles, so a physical side length on a sphere of radius must enter as . All six angles lie in , and the denominators are positive. The reciprocal form, , is equivalent. This is Tatum's sine formula, equation 3.5.1, in Celestial Mechanics, section 3.5: spherical sine and cosine formulas.
A short proof explains the symmetry of the spherical law of sines. Let be the vertex unit vectors at . At , the outgoing unit tangent vectors towards are and . Their angle is , so the magnitude of their cross product is . Since both tangent vectors are orthogonal to , the scalar triple product obeysDividing by proves the spherical law of sines. Its beauty is that the same three-dimensional scalar triple product can be calculated at any vertex, producing all three ratios at once.
For the spherical triangle worked out under the spherical law of cosines, , and . Hence , and the spherical law of sines givesThe inverse sine gives , but the supplementary angle has the same sine. The spherical law of sines alone therefore leaves two candidates for this angle. The spherical law of cosines, using the known three sides, gives and selects ; likewise . When only two sides and an opposite angle are given, two distinct valid spherical triangles can remain. A cosine relation resolves an inverse sine branch only when enough additional data are known; it does not make every ambiguous data set unique.
For a nondegenerate convex minor spherical triangle, the spherical law of cosines relates two angular sides , their included interior angle , and the opposite angular side :Relabelling the vertices gives the corresponding formulas for and . As with the spherical law of sines, physical side lengths must first be divided by the sphere's radius. The spherical law of cosines determines uniquely from when the data describe such a spherical triangle. It also recovers each interior angle from three sides, for exampleUsing the cosine and the range selects a unique angle, avoiding the supplementary-angle ambiguity of an inverse sine calculation.
To derive the spherical law of cosines, let be the vertex unit vectors at , so , and . The outgoing unit tangent vectors at are and . Their dot product is both and , proving the identity. This gives a geometric explanation: spherical trigonometry compares angles in the tangent plane using vectors in the surrounding Euclidean space.
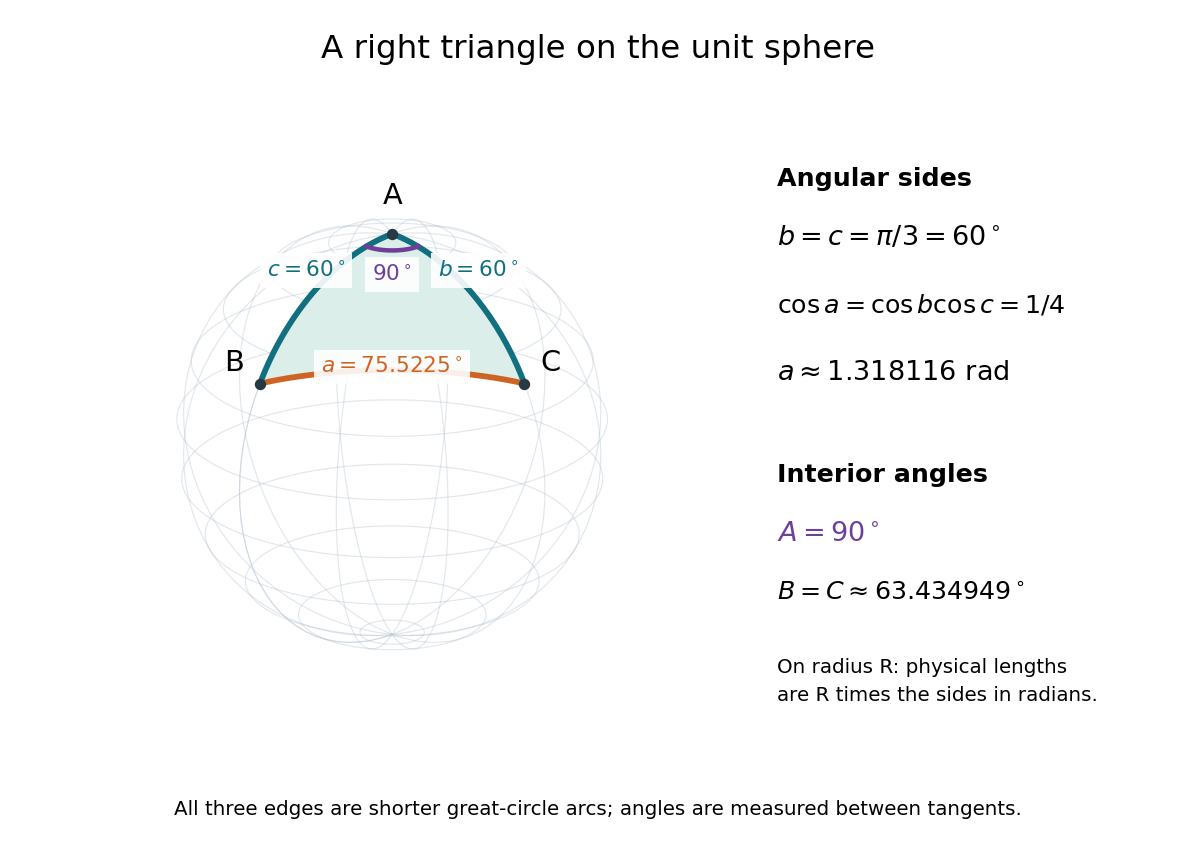
For a worked example on the unit sphere, take the verticesAt , the outgoing unit tangent vectors are and , so the interior angle is a right angle. The vertex dot products give . The spherical law of cosines then reduces to the right-angle identity , givingTo find , use the relabelled spherical law of cosines:The physical side lengths on a sphere of radius are and . For example, on a toy sphere with metres they are approximately , and metres; the interior angles stay the same. Applying the planar Pythagorean theorem directly to the angular sides would instead give . That flat right triangle calculation does not give the great-circle distance between and .
The familiar law of cosines reappears as a local approximation. With all small in radians, substitute the small-angle approximations and into the spherical law of cosines and keep terms through second order:Multiplication by gives the planar law of cosines for the physical side lengths. For a fixed small surface triangle on a progressively larger sphere, the angular sides shrink and this approximation improves. Thus the curved and flat formulas fit together: the Pythagorean theorem is recovered locally when is a right angle.
A spherical triangle is bounded by three great circle arcs. For the usual convex minor spherical triangle, the vertices are neither antipodal nor on one great circle, and its angular sides and interior angles lie in . An interior angle is measured between outgoing tangent vectors to the two sides at a vertex, rather than between straight chords inside the sphere. The spherical law of sines and spherical law of cosines determine its side-angle relations; the spherical excess formula determines its area.
Reflections in the sides of a spherical triangle of angles generate a finite group when its images tessellate the sphere. The triangle area is by the spherical excess formula. Label its three vertex types and continue those labels across each reflected side; they are consistent around every vertex and, because the sphere is simply connected, globally. The generated group preserves these labels, so a chamber stabilizer fixes all three vertices and is trivial. Dividing sphere area by chamber area gives its order. Up to permutation the possibilities are for , and , of orders .
The study of convex sets, their convex hulls, supporting closed half-spaces, and inequalities for their sizes.
The Minkowski sum of subsets of a vector space collects the result of vector addition for every possible pair:Think of fixing a point of , making a translation of the whole of by , and then taking the union of these copies over every . The points of specify displacement vectors; they need not be the centre of a shape. Minkowski addition applies to nonconvex sets too. It is different from set union: for on the real line, but .
For axis-aligned rectangles in the Euclidean plane, the coordinate intervals add separately:Every coordinate between and can be split into one coordinate in and another in , and likewise for the vertical coordinate. Thus a rectangle plus a rectangle gives a square of area , although the two input areas total only . The Minkowski sum adds possible displacements, so its area need not be the sum of input areas.
For closed Euclidean disks centred at the origin, the triangle inequality gives . Conversely, if , split any as . Therefore , including the case . Disks of radii and give a disk of radius , with areas . For disks with centres , the resulting centre is . These two examples lead to the root-of-area comparison in the Brunn-Minkowski theorem.
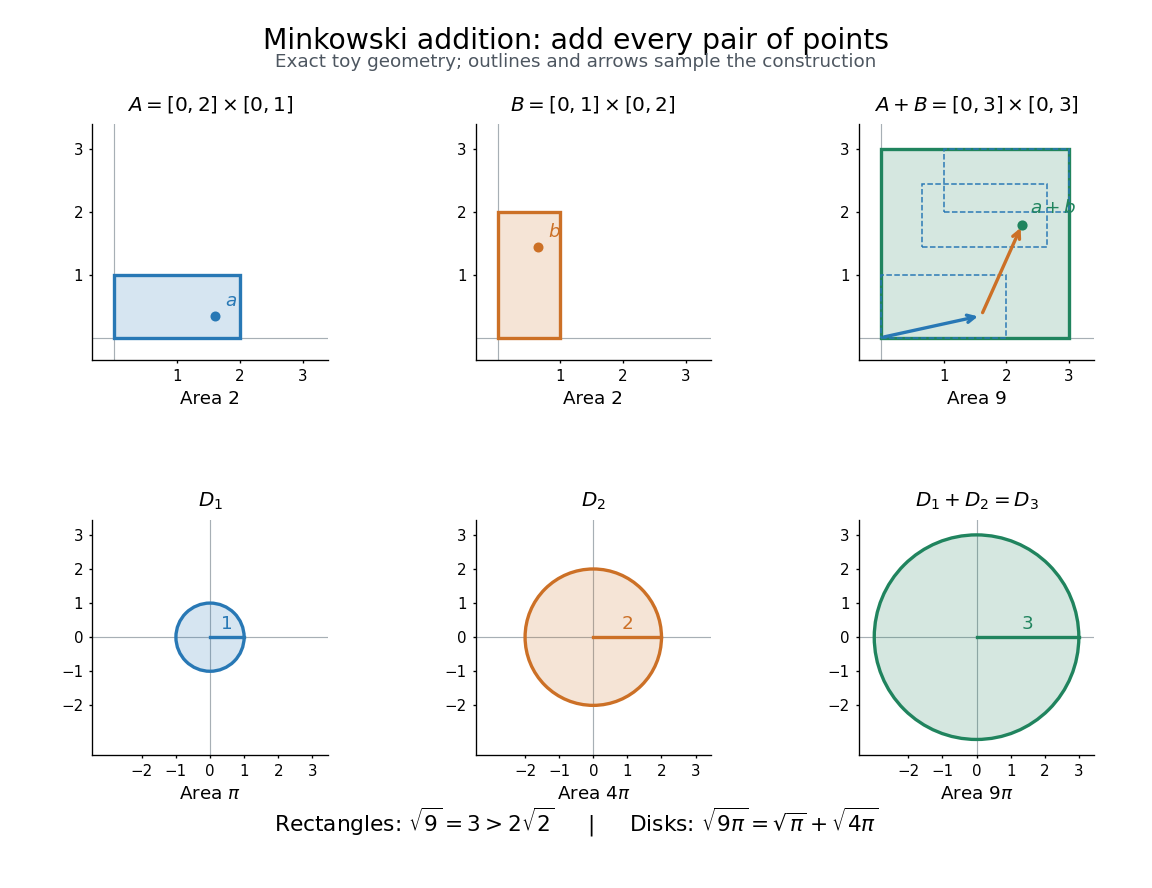
Minkowski addition of two rectangles and of two closed disks: exact toy shapes, sample displacement arrows, and the square-root-of-area comparison
. Details. Minkowski addition is commutative and associative because vector addition is. Its identity is the singleton , and . For displacement vectors and , translations and uniform dilations satisfywhere uses scalar multiplication. A Minkowski sum of convex sets is convex: a line segment between and is obtained by adding the corresponding points of the line segments in and . Closure requires care; see sum of two closed sets need not be closed and sum of a compact set and a closed set.
Suppose a robot occupies a closed set relative to its chosen reference point, and a closed obstacle occupies . Keep the robot's orientation fixed and allow only translations. At reference position , its occupied set is . If touching counts as collision, the forbidden positions in this configuration space are exactlyThe minus sign reflects the robot through its reference origin: solving gives . Thus collision checking for a moving shape becomes checking whether one point lies in a fixed Minkowski sum. Steven M. LaValle derives this translational configuration space construction in Planning Algorithms, section 4.3.2, equation 4.37 and Example 4.13.
For a concrete toy example, take the robot rectangle with its reference point at the lower-left corner, and obstacle rectangle . Their collision region is the rectangleFor example, is forbidden: meets in , of area . At there is just corner contact, which our convention also forbids. Using instead would wrongly miss both reference positions. Only when , as for an origin-centred disk, does the reflection leave the robot set unchanged.
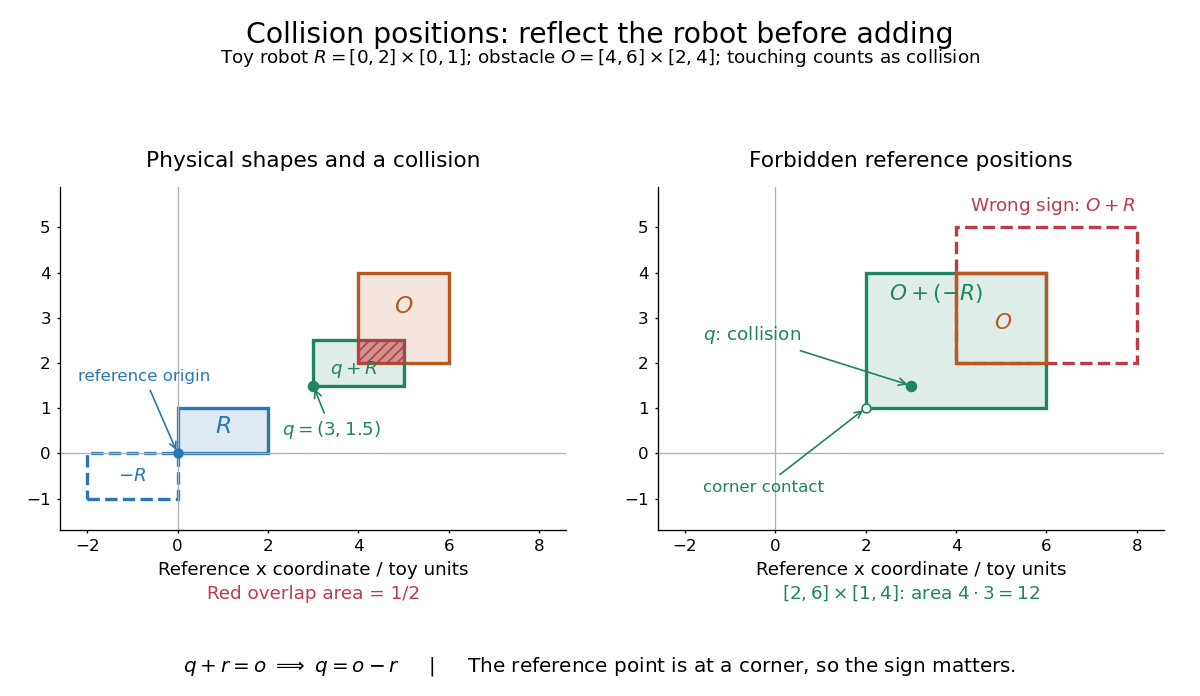
Toy translational collision geometry: a corner-referenced robot requires , of area , and its positive Minkowski sum puts forbidden positions on the wrong side
. Details. The same calculation handles bounded additive uncertainty. If the actual reference position is for any , the union of possible occupied sets is . There exists an allowed error causing contact exactly whenConsequently avoiding this set guarantees avoidance for every in this model. For , the example's forbidden region becomes , with area . Here because the error bounds are symmetric; a one-sided error set must still be negated. This is a worst-case geometric bound, not a probability of collision. Rotating the robot requires an orientation-dependent Minkowski sum for each orientation.
In , the sets and are closed because their points have no finite accumulation point. Their Minkowski sum contains but does not contain zero, since has no positive-integer solution. Compactness of one summand is a useful sufficient condition missing from this counterexample.
In Euclidean space, a Minkowski sum of a compact set and a closed set is closed. From any convergent sequence , extract a convergent subsequence of using compactness. The corresponding then converges to the difference of the two limits, which lies in . If is also bounded, the sum is bounded and therefore compact.
Let and let be nonempty Lebesgue measurable sets with finite Lebesgue measures. Assume that is also a Lebesgue measurable set; its measure may be infinite. ThenHere denotes -dimensional Lebesgue measure in Euclidean space. Nonempty compact sets and nonempty open sets of finite measure satisfy the measurability assumptions. Measurability of arbitrary summands alone does not guarantee measurability of their Minkowski sum. The theorem does not require convexity. See R. J. Gardner, The Brunn-Minkowski Inequality (2002), Theorem 4.1 and the following remarks.
The th root converts a volume into a quantity that scales like a length: uniform dilation gives for . In the Euclidean plane the theorem compares square roots of areas, not the areas themselves. For the two rectangles above it reads . Equivalently their sum has area . For the two disks, it reads , an equality. These are exact geometric examples, not measured data.
Applying the theorem to the scaled sets gives, whenever that sum is a Lebesgue measurable set,For convex bodies, this means the root-volume of the interpolated shape lies above the straight line between the input root-volumes. In fact is a concave function on : convexity gives for , so interpolating two intermediate shapes gives another intermediate shape and the same inequality applies. The beauty is that no particular boundary shape appears in the bound: possible pointwise displacements force a minimum amount of space.
For convex bodies , equality holds exactly when they are homothetic convex bodies, meaning for some vector and . This equality qualification is part of the Brunn-Minkowski theorem for convex bodies. [ref]
https://sites.stat.washington.edu/jaw/COURSES/520s/523/HO.523.20/Gardner.BullAMS.02.pdf. Gardner (2002), introduction, equation 2 and its equality condition
For positive-sided axis-aligned rectangles, the comparison can be checked directly:Equality requires : the rectangles must have the same aspect ratio. Our and rectangles do not. All positive-radius disks are homothetic convex bodies, explaining their equality.Do not apply that equality criterion without its hypotheses. If , its Lebesgue measure is zero and is a translation of , so equality holds even for nonconvex . Also, changing a summand on a null set can change the measure of its Minkowski sum: in one dimension, and both have measure , but has measure . Removing the single extra point restores equality with sum measure . Thus merely being equal almost everywhere to homothetic convex bodies is not a sufficient equality test for arbitrary sets.
The Brunn-Minkowski theorem also bounds the collision-region volume: for positive-volume compact sets , reflection preserves Lebesgue measure, so . In the toy collision example this gives area at least , compared with the exact area . A lower bound alone does not identify safe reference positions; the actual Minkowski sum supplies those.
A convex body in is a compact convex set with nonempty interior in the ambient Euclidean space. It consequently has positive finite Lebesgue measure. A filled rectangle with positive side lengths and a closed positive-radius Euclidean disk are planar convex bodies. A line segment in has empty ambient interior and is not a convex body under this convention. This is the convention used in the Brunn-Minkowski theorem. [ref]
https://sites.stat.washington.edu/jaw/COURSES/520s/523/HO.523.20/Gardner.BullAMS.02.pdf. Gardner (2002), introduction
Two convex bodies are homothetic convex bodies if one is a translation of a positive uniform dilation of the other. Their lengths scale by and their volumes by . Closed disks of positive radii are homothetic convex bodies; axis-aligned positive-sided rectangles are homothetic convex bodies exactly when their aspect ratios agree. The Brunn-Minkowski theorem characterizes this relation by equality of root-volumes in Minkowski addition.
The geometry of affine spaces, studying incidence and parallelism without choosing an origin or a metric.
A nonempty set equipped with a group action of the additive group of a vector space , such that for every there is a unique with . There is no distinguished origin. Choosing one identifies with ; changing it gives a translation.
Choosing a new origin in a vector space transports its operations along . Since and , every vector space axiom transfers through this bijection. The new additive identity is and the additive inverse of is . This illustrates why an affine space has no preferred origin even though choosing one produces a vector space.
Points in an affine space are affinely independent if the only affine dependence displayed above has all coefficients zero, using any choice of origin to read the vector equation. Since the coefficients sum to zero, replacing the origin leaves that equation unchanged. Substituting shows that this condition is equivalent to linear independence of . It also says that an affine combination of the points has unique coefficients. In , at most points can be affinely independent; such points span a full-dimensional simplex.
An affine dependence of points is a nonzero coefficient family satisfying the displayed identities. Equivalently, the augmented vectors are linearly dependent. Both identities are independent of the chosen origin. The absence of an affine dependence is affine independence.
The points with integer coordinates in a real d-dimensional affine space with a chosen origin and coordinate basis. Translations by integer vectors and dilations by positive integers preserve this set. The Gallai theorem for an integer lattice concerns finite colourings of these points and homothetic copies of finite configurations of them.
A translation and positive uniform scaling of a finite configuration in a real vector space. It preserves the ratios and directions of differences between its points. In an integer lattice, the Gallai theorem for an integer lattice guarantees a monochromatic homothetic copy of every finite pattern in any finite colouring, with positive integer scaling factor.
An affine combination is a weighted point with . The coefficients can be negative. The sum is meaningful in an affine space without selecting a preferred origin: relative to any point , it means . Affine maps preserve these weighted points. [ref]
For an original example in the Euclidean plane, take , and . Then lies inside their triangle. Its coefficients are nonnegative, making it a convex combination. In contrast, is beyond : it is an affine combination but not a convex combination of these three points. Negative weights allow extrapolation, rather than only interpolation inside the convex hull.
For the affine map , the same weights produce from , and produce from . Thus one can compute a weighted point before transforming the vertices or afterwards, obtaining exactly the same point.
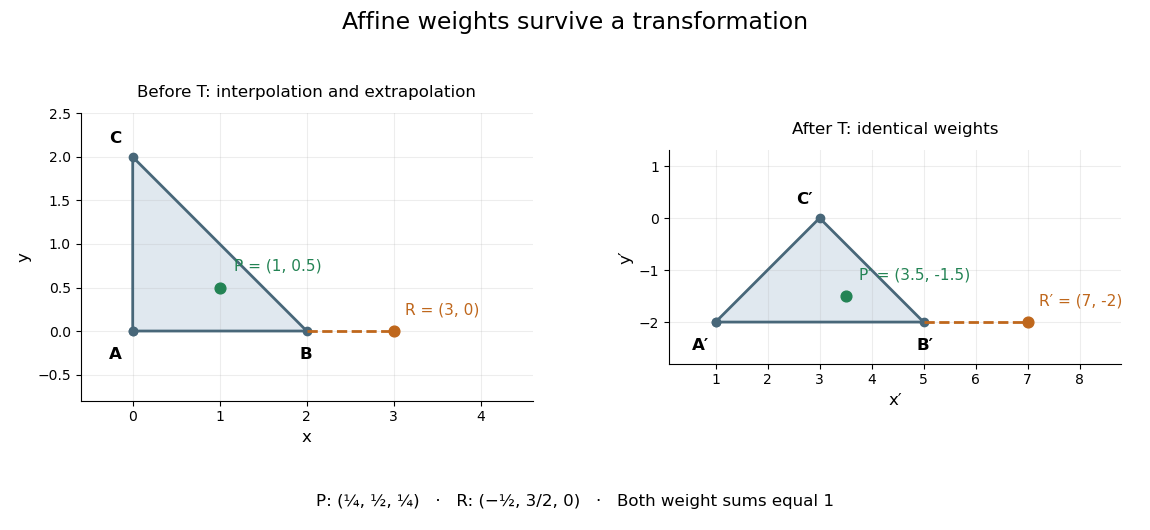
This is useful whenever an object is built from weighted control points: its construction commutes with an affine map, so transforming the control points transforms the constructed object as well. The sum of the weights is the essential condition; no assumption about lengths or angles is needed.
Keep the basis fixed and replace the origin by a point with old coordinates . Each point's coordinates change from to . For coefficients with sum one, the weighted coordinates becomeAdding the new origin gives the original point. This proves origin independence rather than asserting that the coordinate tuples themselves stay unchanged.
The requirement cannot be omitted. In the example , , blindly treating as a point gives in the old coordinates. If the new origin is , the two coordinates become and ; adding them and restoring instead gives . The coefficients sum to two, so this procedure has no origin-independent interpretation as a weighted point.
An affine map combines a linear map with a translation. After choosing coordinate origins, it has the form , , where the matrix is its linear part of an affine map and is a fixed vector. Equivalently, it preserves every affine combination. [ref]
Curves and Surfaces in Geometric Modeling: Theory and Algorithms by Jean Gallier. §2.7, Definition 2.7.1 and linear-map construction, pp. 37–38
An original planar example isIt stretches horizontally, applies a shear mapping, and then translates. The vertices , and become , and . A square grid becomes a grid of parallelograms; straight edges and their weighted points still fit together.
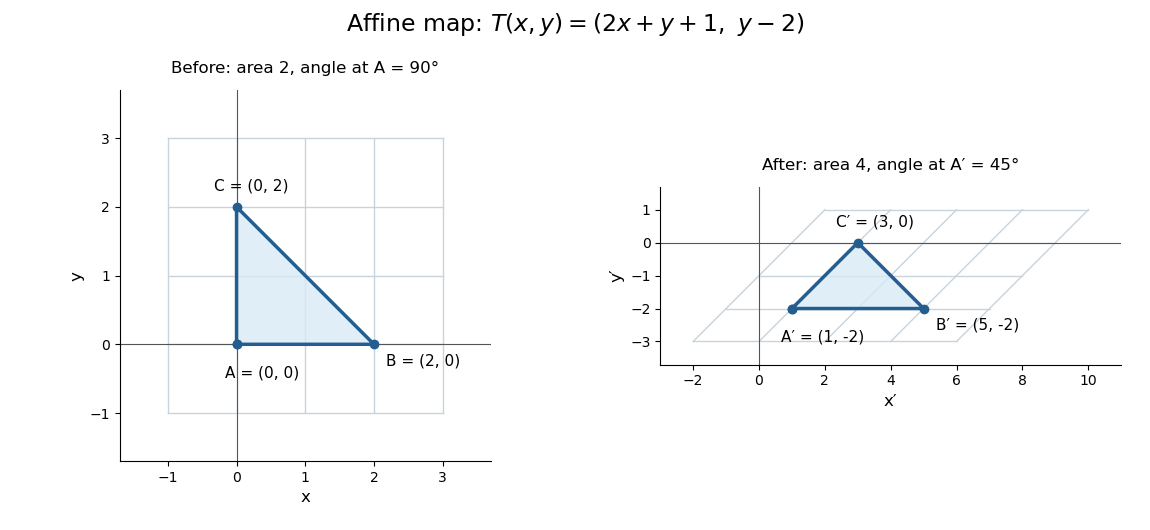
This map is not a linear map with respect to the displayed origins, because rather than zero. It also is not a Euclidean similarity: has length and has length , while the right angle at becomes . Its determinant is , so it doubles planar area. These metric changes explain why affine geometry studies straightness, incidence and weighted points rather than treating every transformation as an isometry.
The linear part is an invertible matrix, giving the concise inverse . More generally an affine map is bijective exactly when its linear part of an affine map is bijective. Between equal finite-dimensional spaces, this means an invertible matrix; the translation cannot repair a loss of rank of a linear map.
If and , their function composition is , again an affine map. With column-vector homogeneous coordinates, its matrix is the product of the matrix for with that for , so the rightmost factor acts first.
For coefficients with sum one, the defining identity follows from linearity:The translation appears once on both sides precisely because . In particular, midpoints map to midpoints, and a parameterized line segment , , maps to . A whole line has the same formula with ; its image is a line if , and a single point otherwise.
An affine map need not be injective. For , the direction belongs to the kernel of its linear part of an affine map. Consequently the whole line maps to , and every parallel line maps to . These are collapsed lines, not images with a surviving direction. Assertions that an affine map preserves distinct parallel lines require the appropriate noncollapse or injectivity hypothesis.
A Euclidean similarity is a map satisfying for a fixed . It has the form with orthogonal: after subtracting and dividing by , the map fixes zero and preserves distances, hence inner products by polarization, so it is a linear orthogonal map. It is a contraction if . Contracting Euclidean similarities define self-similar compact sets; the open set condition is a useful separation hypothesis for computing their Hausdorff dimension.
The map associated with an affine map ; it is independent of the translation . An affine Euclidean isometry has an orthogonal linear part, and an isometry between flat tori has a lift whose linear part carries one Euclidean lattice onto the other.
A closed half-space consists of a hyperplane and one of its two sides in a real affine space. Replacing the weak inequality by a strict inequality gives an open half-space. Half-spaces are convex sets, and finite intersections of closed half-spaces are linear polyhedra.
A half-plane is a half-space in a two-dimensional Euclidean space, consisting of points on one side of a line. For distinct centroids, each of the two Voronoi cells defined by their Euclidean distances is a closed half-plane bounded by their perpendicular bisector, with an explicit convention needed to assign boundary ties.
On an affine space modeled on a vector space, the map for a fixed vector . Its derivative is the identity, and . Changes between flat coordinates on a translation surface have this form.
A space parametrizing isomorphism classes of geometric objects. Its topology and possible stabilizers are part of the definition; a moduli space of Riemann surfaces forgets the marking retained by Teichmüller space.
The punctured torus retracts onto two circles, so its flat gauge-orbit space is under simultaneous conjugation. Write unit quaternions as and . Complete orbit invariants are with . Adding to the third coordinate identifies this space with the compact convex set of positive-semidefinite real correlation matrices, a closed three-ball. The dense open subset is a closed disk times an open interval; its complement is two disjoint intervals.
// Destination: geometry-and-topology.bigb
The moduli space of unmarked compact genus- Riemann surfaces. For it is the quotient of Teichmüller space by the mapping class group, with its quotient topology. The thick subsets are compact by Mumford's compactness theorem.
For stable compact Riemann surfaces with distinct labelled marked points, where , the displayed complex dimension counts independent conformal shapes and positions after conformal automorphisms are removed. On the sphere it is , since three points fix a Möbius transformation. On a torus it is : one shape modulus and positions, less one translation. For genus , the unmarked shape dimension is and continuous conformal automorphisms vanish. The shape dimension also follows from the Riemann-Roch theorem applied to holomorphic quadratic differentials.
The subset of the unmarked moduli space of Riemann surfaces with hyperbolic systole at least is compact for fixed genus . Use a Bers pants decomposition theorem bound, finitely many topological decomposition types and Dehn twists to place representatives in finitely many compact boxes in Fenchel–Nielsen coordinates.
A foliation decomposes a topological manifold into connected leaves which locally look like parallel slices in product coordinate charts.
For a cooriented integrable codimension-one distribution, choose a nonvanishing defining form and an auxiliary form with . Changing the auxiliary form to changes by . Replacing by changes the auxiliary form by , changing the three-form by the exact differential . Stokes' theorem proves invariance on a closed oriented three-manifold. For the weak stable foliation of a curvature-minus-one surface geodesic flow, take , to obtain in the positive base/fibre orientation.
A leaf is a maximal connected integral manifold of the smooth constant-rank integrable distribution defining a regular foliation. It carries its intrinsic manifold topology and is immersed in the ambient manifold. It need not be embedded or closed. Local Frobenius theorem coordinates make each leaf segment a plaque with constant transverse coordinates; global confinement to an immersed leaf follows by joining such plaques along tangent curves.
A codimension-one foliation of a closed three-manifold is taut if every leaf meets a closed transverse curve. In particular, the fibers of a bundle over form a taut foliation.
A closed transversal is a closed curve everywhere transverse to the leaves of a foliation. A single such curve meeting every leaf proves that the foliation is a taut foliation.
The orbifold fundamental group records loops together with their local isotropy relations, so a loop around a cone point of order has its th power trivial rather than being trivial itself. For an oriented closed surface of genus with cone orders , its presentation is . A torsion-free finite-index subgroup of a hyperbolic surface orbifold gives a smooth locally isometric surface cover. The absence of torsion means that the subgroup meets no nonidentity local cone stabilizer.
Pair the edges of an oriented hyperbolic polygon by length-preserving identifications reversing their boundary directions. Label the pairs by generating elements of a finite group . Glue the corresponding edge of a copy labelled to its mate in the copy labelled . Left multiplication of labels defines the action. A vertex cycle of a paired polygon has angle sum and accumulated gluing word of order ; above it lie vertices, each of cone angle . The action is free away from vertices, and the vertex stabilizers are conjugates of . If the base cone has integer order and , this is an orbifold covering, with lifted cone order . The lift is smooth exactly when .
In the paired-polygon construction of finite surface covers, a subgroup acts freely precisely when the displayed intersection is trivial for every vertex word and every . The quotient map is then a normal covering map with deck group and . Normality of in is instead the criterion for the intermediate orbifold cover to be normal. These are different covering maps.
For a paired -gon with base vertex cycles of a paired polygon, there are one face, edges and vertices on the base, so . The full finite-group construction has faces, edges and vertices, giving the displayed ordinary Euler characteristic. If all lifted angles are , the orbifold Euler characteristic formula gives equivalently .
A vertex cycle of a paired polygon is an equivalence class of vertices under the edge identifications. Its angle sum is the total angle at the resulting point of the quotient surface. Recording the edge labels encountered around that point gives a group word, whose order determines the number of turns required to close a lifted cycle. This explains the angle multiplier and lifted vertex count in the paired-polygon construction of finite surface covers.
Over a cone point of order , a cycle of length in the monodromy on sheets has ramification degree and residual cone angle . The lifted inherited hyperbolic metric is smooth precisely when every such cycle has length . Equivalently the subgroup defining the cover meets no conjugate of a nonidentity power of a cone generator.
For a compact topological surface with cone-point orders , the orbifold Euler characteristic is . An orbifold covering multiplies this quantity by its degree.
An -sheeted surface cover of an orbifold of underlying genus with cone points has the displayed ordinary Euler characteristic, where is the number of cycles of the th cone monodromy permutation. The ramification deficit over that point is , so the formula follows by counting lifted vertices, edges and faces, or by the Riemann-Hurwitz formula. If every cone cycle has its full prescribed length, this equals .
For a projective variety over the complex numbers, analytification gives an equivalence between algebraic and analytic coherent sheaves, preserves their cohomology, and is fully faithful on their morphisms. In particular, a holomorphic isomorphism between algebraic line bundles is algebraic. This allows a complex-torus proof of a line-bundle identity to establish the corresponding algebraic identity on a projective elliptic curve.
A property holds at a very general point of an irreducible complex algebraic parameter space if it holds outside a countable union of proper Zariski-closed subsets. This permits countably many exceptional conditions. Over that complement is nonempty and dense, for example by the Baire category theorem on a local smooth analytic chart.
For a projective scheme and a fixed Hilbert polynomial , the Hilbert scheme parametrizes flat families of closed subschemes of with that polynomial. This turns a family of embedded algebraic curves into an algebraic parameter space.
For a projective scheme over a field , the Hilbert functor assigns to a -scheme the set of closed subschemes which are of finite presentation, proper and flat over . Pullback of families makes it a contravariant functor. After choosing a very ample line bundle, requiring a fixed fibre Hilbert polynomial gives the subfunctor represented by . The unrestricted functor is represented by the disjoint union of these Hilbert schemes.
A first-order embedded deformation of a closed subscheme is a closed subscheme flat over the dual numbers and with special fibre equal to the given embedded . It is a tangent vector of the Hilbert scheme, not a deformation modulo arbitrary automorphisms of the ambient scheme. These deformations are naturally the global sections of the normal sheaf.
For a closed subscheme with ideal sheaf , one has . Locally a flat deformation ideal satisfies . Lifting to gives a well-defined map killing . Conversely the graph condition defines an ideal with flat quotient by the flatness criterion over dual numbers. These operations commute with restriction and are inverse, giving the global identification without a smoothness assumption.
The closed subscheme of the Grassmannian parametrizing projective -planes contained in an embedded projective variety .
The Fano scheme for projective lines. For , it is a closed subscheme of and hence is projective. Requiring the defining homogeneous polynomials of to vanish along a line gives its closed defining conditions.
Cubic forms in four variables form . Lines form the four-dimensional Grassmannian . The incidence pairs with form a projective-space bundle with fibre over , since restriction to a line imposes four independent linear conditions. Hence the incidence variety is irreducible of dimension 19. For , a nearby line written , lies on precisely when all four parameters vanish. This is an isolated point of that fibre. The fiber dimension theorem forces the image to have dimension 19, and projectivity makes the image closed. It is therefore all of , proving geometric existence over an algebraically closed field.
A projective bundle with fibre over the four-dimensional Grassmannian . The condition of containing a fixed line imposes four independent linear conditions on the twenty cubic coefficients. The projection to is proper. The line is an isolated point over ; isolated fibre point forces dominance in equal dimensions then proves that every cubic surface contains a line.
For a line on a degree- smooth surface in , the adjunction formula gives . If , all lines are negative curves, hence there are only countably many by countability of negative curves. Their projective Fano scheme of lines cannot have a positive-dimensional complex component, since such a component has uncountably many points. A zero-dimensional projective scheme of finite type has finitely many points, proving the assertion.
Étale cohomology is sheaf cohomology on the site whose objects are étale morphisms and whose coverings are jointly surjective families of such morphisms. It provides cohomological invariants for algebraic varieties over fields of positive characteristic. In Deligne-Lusztig theory, compactly supported groups with -adic coefficients, for different from the field characteristic, give finite-dimensional representations of the finite groups acting on the varieties.
An algebraic set is a zero locus of polynomial equations, allowing reducible sets. An affine algebraic set uses ordinary polynomial equations; a projective algebraic set uses homogeneous equations in projective coordinates. On affine or projective space, closed sets in the Zariski topology are algebraic sets, and an irreducible algebraic set is an algebraic variety in the classical convention.
An abelian variety of dimension has complex multiplication when its rational endomorphism ring contains a commutative semisimple -algebra of dimension . For an elliptic curve in characteristic zero, this means its geometric endomorphism ring of an elliptic curve is an order in an imaginary quadratic field. The resulting rank-one Tate module representations connect torsion points to class field theory.
A complex CM period compares an algebraic invariant differential on a CM elliptic curve with its analytic lattice coordinate. At an ordinary prime, a -adic CM period compares the same differential with the invariant differential of the multiplicative formal group: an isomorphism is normalized by . Matched periods make normalized critical Hecke L-function values algebraic and give precise p-adic L-function interpolation.
For a complex CM torus and an idele of its CM field, the automorphism corresponding to by Artin reciprocity takes its lattice to and acts on torsion through the adelic scalar . When the curve is defined over a larger field, use the idelic norm to the CM field. Comparison with the original curve gives a scalar in the CM field, producing the Hecke character of a CM elliptic curve.
An elliptic curve with complex multiplication is called a CM elliptic curve. Distinguish geometric endomorphisms from endomorphisms defined over the base field. In characteristic zero, adjoining the imaginary quadratic field selected by the tangent action makes all geometric endomorphisms defined over the base. Good split primes have ordinary reduction; good inert primes have supersingular reduction.
The projective morphism associated to the powers of the ideal sheaf of a closed centre. Off that centre it is an isomorphism. Blowing up a smooth point of an -dimensional smooth variety replaces the point by a projective space , the algebraic exceptional divisor.
For a blowup of an algebraic variety with centre , the strict transform of an algebraic subvariety of a subvariety not contained in is the closure of . It excludes components supported entirely in the algebraic exceptional divisor.
The divisor contracted by a blowup of an algebraic variety to its centre. For the blowup of a smooth point on an -dimensional smooth variety it is . Being a closed projective subvariety of positive dimension, it can obstruct affineness of a fibre containing it.
The Zariski topology on an affine scheme has closed sets for ideals . Its basic open sets are the principal open subschemes .
A Zariski cover of a scheme is a family of open immersions whose images cover its underlying topological space. Such families define the Zariski topology as a Grothendieck topology on the category of schemes; a cover need not be finite.
A subset of an algebraic variety is Zariski dense when its closure in the Zariski topology is the whole variety. For an affine variety, this is equivalent to saying that every regular function vanishing on the subset vanishes on the entire variety.
A presheaf of sets on a topological space is a contravariant functor from the inclusion-ordered category of open subsets to . Its maps for are restriction maps.
Every restriction is the identity. Its stalk at each point is , and its étale space of a presheaf is with discrete. It is generally not a sheaf; in particular its value on the empty open set is . Its sheafification is the constant sheaf of sets.
A natural transformation between presheaves assigns maps commuting with every restriction. For presheaves of abelian groups or modules, those maps preserve the specified algebraic structure.
A sheaf of sets is a presheaf in which compatible sections on any open cover glue to one unique section on the union.
A sheaf may additionally carry abelian group or module structure on its sections, with restriction and gluing preserving that structure. The underlying sheaf of sets retains the same local-to-global axiom.
For inclusion of a point , this is the direct-image sheaf of a set. It is right adjoint to the stalk functor. It uses the singleton terminal set on opens omitting , rather than the zero group used for abelian-group skyscraper sheaves.
The space of germs of a presheaf has basic opens given by the germs of one section over an open set. Projection to its base point is a local homeomorphism. Continuous sections of this projection give sheafification. For the constant presheaf of sets, the basic opens are , giving the ordinary product with a discrete fibre.
The sections are locally constant functions into a discrete set , with ordinary restriction. It is the sheafification of the constant presheaf of sets. Its value on an empty open set is a singleton, even if is empty. For a topological space, this construction is left adjoint to the global sections functor: a map from it to a sheaf is a family of global sections indexed by .
A morphism of sheaves assigns a map on every open set, commuting with all restriction maps. For sheaves of abelian groups, sheaves of rings or sheaves of modules, the maps must also preserve the relevant algebraic structure. It induces maps on every stalk, and equality of sheaf morphisms can be checked there.
For a morphism of sheaves of abelian groups or modules, the cokernel sheaf is the sheafification of the presheaf . Its stalk at is . The presheaf quotient itself need not satisfy the sheaf gluing axiom, which explains why a surjective morphism of sheaves need not be surjective on global sections.
Articles were limited to the first 100 out of 5615 total.



