The two free indices are the row and column indices of a matrix. The Kronecker delta has value one on its diagonal and zero off it, so the answer is the identity matrix .
This is the incorrectly formed expression. In the Einstein summation convention, an index in a term is either free and occurs once, or summed and occurs twice. Here occurs three times in the same product, so it cannot consistently be classified as either. Renaming a dummy index before multiplying would give a valid different expression, such as , but does not make the printed expression valid.
The contracted Kronecker delta is . The other scalar contraction is , while is the th component of the matrix transpose applied to . Hence the resulting vector isBoth terms have the same single free index , as required by the Einstein summation convention.
Compare with . The scalar factors commute, so the answer isThe order of the contracted indices matters because the Levi-Civita symbol is antisymmetric.
Interchange the two dummy indices . The product is symmetric under this interchange, while the Levi-Civita symbol changes sign. Thus the contraction equals its negative and is the zero vector, equivalently .
For the unheaded continuation, write the vector triple product asThe Levi-Civita symbol contraction is . One way to check its sign is to fix distinct : the only nonzero term has the remaining index, and the pairs contribute respectively. When , both sides vanish. Contracting with the vectors now gives both requested notations:If and are orthogonal, then . With the specified , the perpendicularity of the cross product gives . ThereforeThe same answer covers the degenerate case in which one of these two vectors is zero.
Expanding the cross product component by component gives its cross-product matrix:It is a real skew-symmetric matrix and annihilates . By the vector triple product,so for a unit vector . Choose a unit vector and put . Then is an orthonormal basis and , , . Thus the characteristic polynomial is and the cross-product matrix spectrum isOver the complex numbers, corresponding eigenvectors are , , and . Only the zero eigenvalue has real eigenvectors.
For the specified third coordinate axis, direct multiplication givesIts zero eigenspace is , and its eigenspace is the whole plane . Hence the eigenvalues of are , with every nonzero vector in the appropriate eigenspace an eigenvector.
A real number is the supremum of a nonempty set if every satisfies and no smaller real number is an upper bound. Equivalently, for every there is with . A greatest element, or maximum, additionally belongs to .
Let and suppose . Fix . The approximation property gives at least one element of in . If there were only finitely many, they would have a largest value . Every other element of is at most , so would be an upper bound for the whole set. This contradicts the definition of the supremum. Therefore there are infinitely many such elements, the accumulation below an unattained supremum.
For a counterexample when the supremum is attained, take . Its supremum and greatest element are both zero, while every interval contains no elements of .
Suppose, towards a contradiction, that for every , where . Choose a radius strictly between and , and take any with . ThenThe geometric series on the right converges because its ratio lies in . The comparison test for series therefore gives absolute convergence of the power series at , contrary to the defining property of its radius of convergence. Thus is unbounded in whenever . This is the bounded power-series terms force interior absolute convergence principle. The case has no points outside its convergence disk and the assertion is vacuous there.
Every possible radius of convergence is realized by an explicit power series:For the first, consecutive absolute terms have ratio , so at every they eventually grow and do not tend to zero; at zero the series is defined. The middle geometric series converges absolutely exactly for , and outside that disk its terms grow. The last has consecutive-term ratio , so the ratio test gives absolute convergence for every finite . These arguments use the necessary zero-term condition for convergence, the comparison test for series, and absolute convergence of a geometric series with ratio less than one; they do not assume convergence on the boundary.
The complex exponential function factorizes as . HenceThe real exponential multiplies both components; it does not change the argument.
Using and collecting real and imaginary terms gives the complex cosine identity . ThusThe sign follows from the factors and in the two complex exponentials.
For , write with . The complex logarithm has values , . ThereforeFor a specified single-valued branch, choose the corresponding continuous determination of the argument. In particular, the principal value uses ; it is not represented correctly by in every quadrant. The complex logarithm is undefined at zero.
For , rationalizing the denominators gives and . Their imaginary parts cancel, soThis also follows because the summands are complex conjugates.
The cubic terms are the expansion of . Subtracting therefore givesHere the expression is a polynomial in and its complex conjugate, rather than a holomorphic polynomial in alone.
For the unheaded continuation, set in the food equation. The two square roots are , so exponentiating givesBoth values have and hence lie strictly inside the disk. Both also have the indicated principal logarithms. Allowing the multivalued complex logarithm produces no additional points: the only permitted values of are still the two square roots already used.
For drink, the PDF squares only the denominator. Put . Its numerator is and its unsquared denominator is , which is nonzero unless . Multiplying the equation by this denominator squared and equating the real part and imaginary part yieldsthat is and . If , the real equation gives or , and zero is excluded. If , then , but the real equation would require , impossible for real . ThusIt lies on the allowed disk boundary, and direct substitution gives . The denominator-only square matters: squaring the entire quotient would define a different locus.
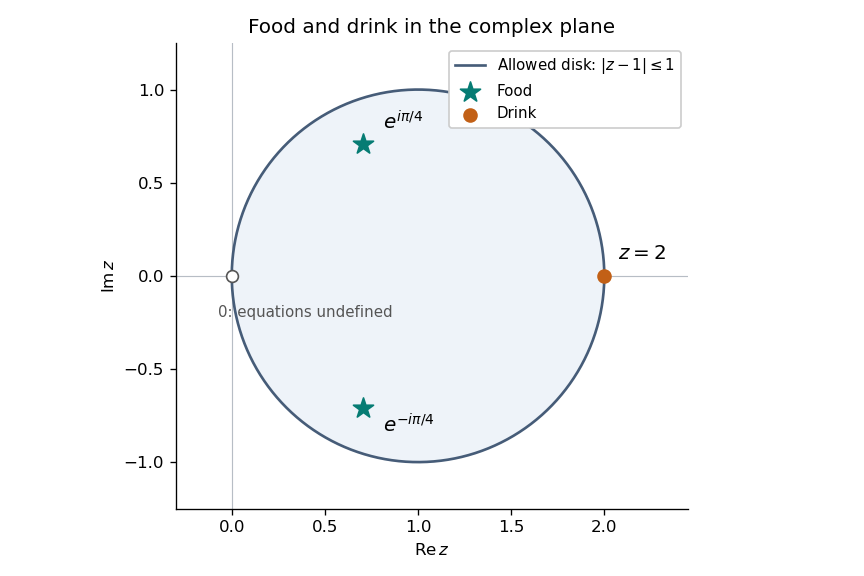
Food points inside the allowed complex disk and the unique drink point on its boundary
. Details. 
The matrix rank is the dimension of its column space, equivalently the dimension of the image of the corresponding linear map. The equation is solvable precisely when , equivalently when the augmented matrix has the same rank as . If is one solution, every solution is with , since subtracting any two solutions gives a kernel element. The rank-nullity theorem gives .
Consequently, for rank three there is one solution for every , namely . For rank two there are no solutions outside the column plane, and an affine solution space of a linear equation of dimension one when consistent. For rank one, consistency requires to lie on the column line and the solution set is an affine plane of dimension two. For rank zero, : the solution set is all of if , and empty otherwise. These descriptions include homogeneous systems, whose solution spaces pass through the origin.
The sphere has normal at the specified point, so its tangent plane isA general straight line through the origin is , , for a fixed nonzero direction . To express the intersection using a matrix, choose independent vectors spanning . The line is exactly the intersection of and , henceThe first two rows have rank two. The third is independent of them exactly when . In that case the rank is three and the unique intersection isGeometrically the line crosses the tangent plane transversely. If , the matrix rank is two: its third row is a linear combination of the first two, but the corresponding right-hand-side combination would be zero rather than two. The system is inconsistent and there is no intersection. The line is parallel to the tangent plane and cannot lie in it, since it contains the origin while the plane does not. Thus no choice of a genuine direction produces an infinite intersection in this particular problem.
For , define the orthogonal projection of onto its span byThe first is parallel or antiparallel to , or zero, and . This proves the decomposition. If as well, comparison with yieldsIndeed shows that the ratio lies in . There is a unique with this cosine. The definition is symmetric in the two vectors, unchanged by orthogonal coordinate changes and positive rescaling, and agrees with ordinary plane geometry in their span: projecting a unit vector onto the other gives its cosine. Parallel, perpendicular and antiparallel directions give respectively. The zero vector has no defined angle; if , the nonzero-axis projection formula itself must not be used.
The vertices of the centered hypercube are sign vectors . A body diagonal identifies and , hence there are such diagonals. If two sign vectors disagree in positions, their dot product is . For odd this integer is odd and cannot be zero. Thus no two body diagonals are perpendicular in odd dimension, by the orthogonality of hypercube body diagonals.
In four dimensions, mutually orthogonal nonzero vectors are linearly independent, so at most four mutually perpendicular diagonals are possible. Four are achieved by the directionsEach has squared norm four and every distinct pair has zero dot product; these are the rows of a Hadamard matrix. Therefore the maximum is four.
For distinct diagonals, the Hamming distance is ; would represent the same line. Oriented vertex directions therefore give cosines . The angles areFor unoriented diagonals, the usual smaller angle between the lines is or ; the supplementary intersection angle also occurs when the two rays are chosen oppositely. Stating this convention avoids counting a line and its reverse as different diagonals.
Use matrix notation and set , , . Contracting the proposed decomposition with and taking its trace, using the stipulated transverse and trace conditions, givesThese relations determine both scalars and the transverse vector uniquely:The last expression obeys directly.
To construct and check the remaining symmetric matrix, use the orthogonal projection matrix onto , and defineBoth terms are symmetric, , andExpand with . The mixed terms are and , while and . Consequentlyand the displayed coefficient equals . This proves existence as well as the axis decomposition of a symmetric matrix formulas.
For the dimension count, choose an orthonormal basis whose third axis is parallel to . The vector has two transverse components. The conditions and symmetry set the third row and column of to zero, leaving a symmetric block. Its zero trace leaves two independent entries, of the form . Together with the two independent scalars , the total is parameters, exactly , the dimension of real symmetric matrices. The recovery formulas also prove uniqueness, so this is an actual parameterization without redundant degrees of freedom.
For , . The upper bound has telescoping partial sums, bounded by one. The positive partial sums of the original series are consequently bounded by two and increasing, so they converge as a monotone bounded sequence. The series converges absolutely. This also supplies the case of a p-series without requiring its exact sum.
For odd , the denominator is ; for even , it is . There is no zero denominator in the printed index range. For all ,The comparison test for series with the convergent p-series gives absolute convergence. In fact the consecutive pair contributes , so the sum is the same as . Positivity justifies this paired reordering; an alternating-sign appearance in the denominator does not make this an alternating series.
Let denote the summand. Its denominator is positive for every : odd gives , while even gives . Dividing numerator and denominator by their highest powers givesThe terms are positive for sufficiently large , so the limit comparison test with the divergent harmonic series gives divergence to . More explicitly, for the numerator is at least and the denominator is at most , giving . Any finitely many early negative terms change partial sums by only a finite constant and cannot prevent divergence of this positive tail.
The PDF has the doubly exponential denominator . For its positive summands, the successive-term ratio isThus the ratio test proves absolute convergence. Concretely, the tail is eventually dominated by a geometric series of ratio ; the polynomial numerator cannot offset the doubly exponential decay.
For a bounded real function on , take a partition . Its lower and upper Darboux sums areThe function is Riemann integrable when ; the common value is its Riemann integral. Equivalently, for every there is a partition with . A continuous function is bounded and Riemann integrable on each compact interval, so all the following integrals exist.
Set for . Strict decrease gives for . Integrating, with strict inequalities because the difference is positive on interior subintervals, givesThe intermediate value theorem produces with , and strict monotonicity makes this point unique. Thus there is exactly one such in .
For the given exponential function, , soThe preceding strict bounds already prove ; no limiting value at zero needs to be included in its domain.
For differentiability, a continuous strictly monotone function has a continuous inverse on its range. If it is differentiable at an interior point with , the inverse is differentiable at , with derivative . Indeed, setting , inverse continuity gives as , andThis one-dimensional inverse result needs no assumption that is continuous. It is enough here that is differentiable and at every positive argument.
The fundamental theorem of calculus and the quotient rule giveNow and , so the inverse derivative formula applies at every relevant point. The monotone mean-value point of an integral average satisfiesBoth numerator and denominator are negative. For the exponential example, this also agrees with , since for .
To prove the required zero-existence statement directly, let and . This set is nonempty and bounded. Continuity and the strict signs at the endpoints give a right neighbourhood of with negative values and a left neighbourhood of with positive values; consequently . If , continuity would give points of to the right of , contradicting its upper-bound property. If , continuity would give an interval immediately to the left of containing no points of , contradicting the approximation property of its supremum. Hence for some , proving this form of the intermediate value theorem.
For the half-interval claim, put on . It is a continuous function andIf either endpoint value is zero, it supplies the answer. Otherwise the signs are opposite, so the intermediate value theorem, applied also to if necessary, gives an interior zero. Thus for some .
For general positive integer , define on . At its grid points,If a sampled value is zero, it is the desired point. If none is zero, not all sampled values can have the same sign, so two have opposite signs; continuity gives a zero between their grid points. This proves the horizontal chord of reciprocal-integer length:For the interval is the single point zero, which works by the endpoint equality itself. The proof does not require a differentiable function or a periodic extension.
If is constant, any interior point works. Otherwise the extreme value theorem gives an attained maximum and minimum on the interval, and at least one of them differs from the common endpoint value. That extremum must occur at an interior point . At an interior maximum, for small positive the difference quotient is nonpositive, while for negative it is nonnegative. Existence of the common derivative forces it to be both nonpositive and nonnegative, hence zero. The same argument with inequalities reversed applies to an interior minimum. This proves Rolle theorem, including the derivative-at-an-extremum step rather than assuming it.
Now let the nonconstant polynomial have distinct real roots , with multiplicities adding to its degree . If and , differentiation givesThe bracket is nonzero at , so its multiplicity as a root of is exactly . These roots already contribute real roots counted with multiplicity. Rolle theorem supplies an additional root of in each of the disjoint intervals . These additional roots are distinct from each other and from all the .
We have therefore exhibited at least real roots counted with multiplicity. The derivative has degree , so there is no room for any additional nonreal roots. Every root of is real. This is the Rolle root count with multiplicities; for the nonzero constant derivative has no roots, as expected.
For failure of the converse, takeThe derivative has only the real root zero, of multiplicity two. But and the quadratic factor has roots , which are nonreal. Thus real-rootedness of the derivative does not imply real-rootedness of the original polynomial.
An integrating factor isMultiplication by this integrating factor turns the first-order linear differential equation into . Integrating from zero to givesThus the initial value problem has the solutionIndeed, direct differentiation gives , which verifies both the differential equation and the initial condition.
Work first on , where the proposed logarithm is defined. Substitution of into the Cauchy-Euler differential equation gives the indicial equationIts distinct indicial roots are . Using and Euler's formula, a real basis of solutions is . Their Wronskian is , so they are linearly independent and span the two-dimensional solution space of a homogeneous linear differential equation. ThereforeFor the requested change of variables, set . The chain rule givesThe transformed second-order linear differential equation is . Its characteristic roots are again , giving . Substituting recovers precisely the previous general solution.
If solutions on are wanted, the same calculation uses and gives independent constants on that interval. Zero is a singular point of a differential equation; the logarithmic oscillations do not define a nonzero continuous solution through it.
Normalize the probability density function using :The corresponding Weibull distribution has survival functionSince the distribution is continuous, the choices and have the same probabilities. The conditional probability is consequentlyFor and , the supplied inequality, applied to , gives . Taking exponentials yieldsThis expresses the increasing hazard function : surviving to a later age shortens the remaining lifetime in this conditional distribution. At equality holds, as expected from the memoryless property of the exponential distribution.
A Poisson distribution with parameter assigns probability mass functionThe exponential series makes these probabilities sum to one. Shifting the indices in the absolutely convergent sums givesHence andFor independent random variables of parameter one, let . Summing their product probability mass function over all nonnegative givesThe final equality follows from the multinomial theorem applied to . Thus has the Poisson distribution of parameter .
Each has expectation and variance one, so the central limit theorem gives convergence in distributionZero is a continuity point of the standard normal cumulative distribution function. ThereforeThe discrete atom at causes no difficulty: the central limit theorem applies to the entire event with threshold zero.
The characteristic equation of a linear recurrence isFor , these characteristic roots are distinct. Two real solutions of the second-order difference equation are and . Their values at form a matrix with determinant , proving linear independence. Consequently they span the two-dimensional vector space of recurrence solutions.
At the two roots coalesce at one. The linear recurrence becomes , so its successive differences are constant. A basis is therefore , and every solution is .
For the specified initial conditions, the zero-angle solution is . For nonzero angle, it is convenient to center the basis at :This gives and , and each summand obeys the linear recurrence. For every fixed integer , the elementary limit givesThe convergence here is for fixed ; it does not assert uniform convergence over all indices.
Substitution of the power series, with termwise differentiation, gives the coefficient identityThus and are arbitrary, and all power series solutions of the Hermite differential equation areAn empty product is one. For a nonterminating branch the ratio of consecutive terms in its own parity subsequence is asymptotic to , hence tends to zero for every fixed . The ratio test proves convergence everywhere; the resulting power series can be differentiated termwise and indeed solve the differential equation. A terminating branch is already a polynomial.
The boundary condition forces ; the solution is odd. Apart from the zero solution, which works for every , a polynomial occurs exactly when an odd index satisfies . Before that index the odd coefficients are nonzero, and after it they vanish. Thus the odd polynomial solutions of the Hermite differential equation haveEquivalently, comparison of leading polynomial coefficients gives , proving that no other nonzero polynomial is possible. Normalizing by , the polynomials of degree below six areEach can be multiplied by an arbitrary nonzero constant; these are normalized odd Hermite polynomials.
Let . The forcing in the final inhomogeneous linear differential equation is precisely the displayed degree-five eigenfunction , with . HenceDirect differentiation gives , and . Among polynomial solutions this choice is unique: a polynomial in the kernel of must be constant, and its value at zero eliminates that constant.
For , the polar coordinates satisfyA positive constant radius must therefore be one. The nonconstant periodic solutions arewith least period and counterclockwise orientation. The origin is also a stationary solution, hence periodic in the degenerate sense of a constant function; it is a point rather than a nontrivial closed orbit. There are no other constant-radius solutions.
For , put . Then , a logistic differential equation. Solving this separable differential equation givesThe denominator is positive for every forward time. When , the radius increases monotonically to one; when , it decreases monotonically to one; and when it stays there. Thus every nonzero orbit approaches the unit circle while continuing to rotate. More precisely, its distance from the phase-matched circular solution tends to zero; its Cartesian coordinates do not converge to a single point. For , the solution stays at the origin.
The origin is the only equilibrium point. Its Jacobian matrix iswhose eigenvalues are . It is an unstable focus. The unit circle is an attracting limit cycle, rather than a curve of equilibria: on it the vector field remains nonzero. Linearizing the radial equation at gives , confirming radial attraction. All other radii are strictly monotone, so there are no additional nontrivial periodic orbits.
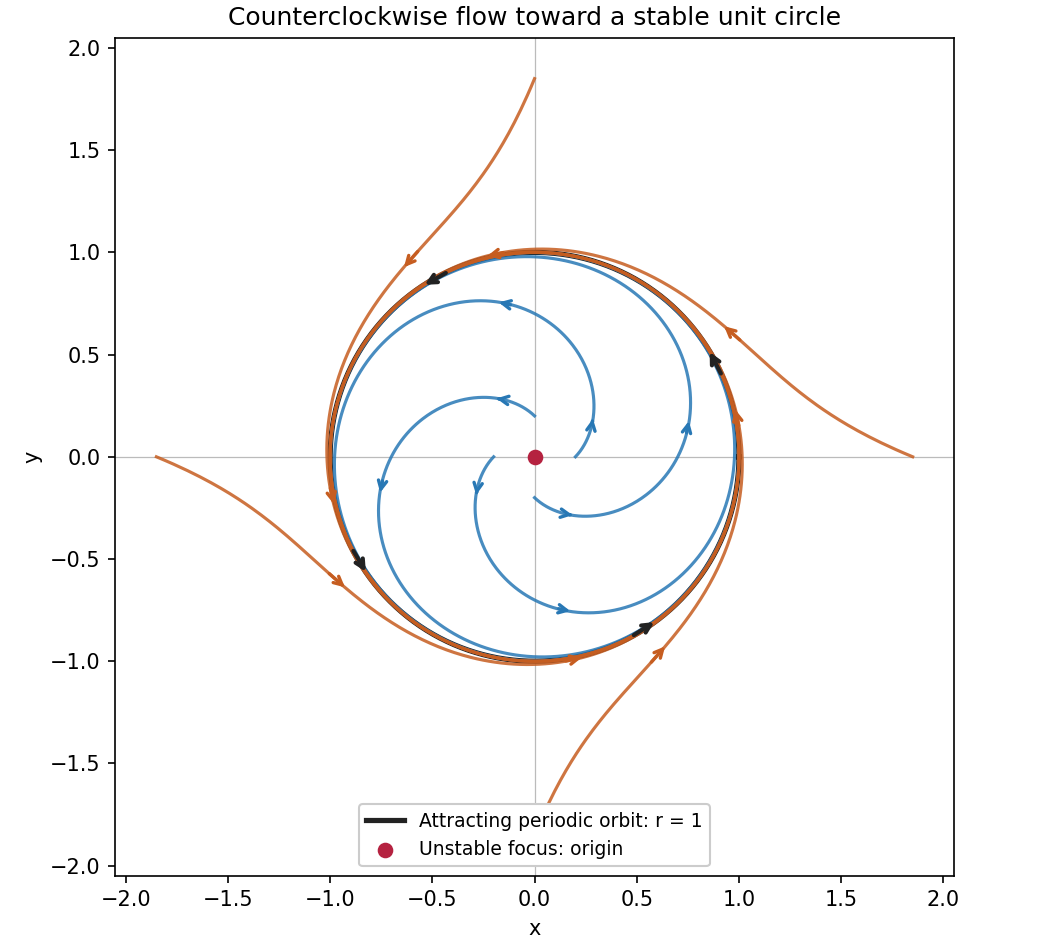
Counterclockwise spirals approach an attracting unit circle around an unstable equilibrium
. Details. 
On an interval where are continuous, define the WronskianUsing the two second-order linear differential equations to eliminate the second derivatives givesThe integrating factor yields the Abel identityThus the Wronskian either vanishes identically or is nonzero everywhere on the interval. If are linearly dependent, it is identically zero. Conversely, if , the two initial-data vectors are dependent, so some nontrivial linear combination has both value and first derivative zero at . The uniqueness theorem for ordinary differential equations makes that combination identically zero. Hence the solutions are linearly independent exactly when their Wronskian is nonzero at one, and therefore every, point. Continuity and the common differential equation are essential to this converse.
For the particular equation, divide by on either interval or . The coefficient of is zero, so its Wronskian is constant there. The proposed satisfies . To construct a second solution by reduction of order, imposeDividing by shows that , givingTaking producesThe nonzero Wronskian proves linear independence; hence the general solution on either nonsingular interval is . Zero is a singular point of a differential equation and is excluded from this construction.
The expectation of a complex random quantity is defined through its real and imaginary parts. Both and are bounded, so all expectations below exist. Expand the addition formulae and apply the expectation of a product of independent random variables identity:Combining real and imaginary parts provesFor the simple symmetric random walk, write , with independent increments satisfying . The usual casino model uses these independent, or conditionally fair, increments. Their characteristic function is , so repeated factorization givesThis is real for real . Equivalently, the distribution of is symmetric, making .
For any integer , Fourier orthogonality givesThe random walk has finite support, so we may interchange its finite expectation with this integral. ThereforeFor even , evenness and reflection symmetry about reduce this toFor odd , has odd parity and cannot be zero, so . As a separate combinatorial check, for the return probability is , since exactly positive increments are required.
Use the intended model of independent random variables with exponential distributions of rates . For , independence gives the survival functionThusThe variance is , obtained from the standard first two exponential moments, and .
For these competing exponential clocks, ties have probability zero. Integrating over Alice's firing time givesLet denote the event that the next shot hits, and use the stated success probability as . Bill's corresponding conditional success probability is one. The law of total probability givesThe Bayes' theorem therefore yields
The printed assumptions specify the two marginal exponential distributions but do not explicitly specify their independence. The answers above require that extra assumption; marginals alone do not determine the race. For a concrete counterexample, take one and set , . These have the required marginals, but ; if , Alice always fires first and . Thus the independence qualification changes actual answers, rather than merely their derivation.
All the following distributions are conditional on the point lying in the unit disk. Initially the joint probability density of is on the square. The disk has area , so the conditioning event has probability . Dividing by this probability gives the constant conditional density on the disk, proving its uniform distribution there.
The polar coordinates have Jacobian determinant . ConsequentlyIntegrating the joint probability density gives and . Since the joint density equals the product of these marginal densities on a product support, and are independent. In particular has the uniform distribution on .
The second change of variables preserves the angle and changes the radius toThe event has probability zero, so arbitrary definitions at that point have no effect on the distribution. For , monotonicity of the logarithm givesSince is a function of , it remains independent of the uniform angle. Hence the new joint probability density isFinally, has polar Jacobian determinant . Dividing the preceding density by gives the Cartesian joint probability densityThis factors into two standard normal distribution densities on . Thus and are independent, each with mean zero and variance one. This derivation is the radial form of the Box-Muller transform.
For each , let be the relative rank of among , with the smallest value assigned rank one. Then . The independent relative ranks of a uniform random permutation can be proved directly: for any choices , insert the index at position in the list of previous indices ordered by their values. After all insertions, assign the values along that list. This is a unique permutation with those relative ranks, and conversely every permutation yields one such insertion sequence.
There are possible insertion sequences, all equally likely because the uniform random permutation is uniform. ThusThe ranks are independent and each is uniform on its possible values. It follows that the independent record indicators haveThe first indicator is the constant one, which is also independent of the others. For , additivity of expectation and variance additivity for independent random variables giveHere is the harmonic number.
Let be the year index of the second record. For , independence givesThe empty product for is one. There is no second record in the first years with probabilityThis exposes a finite-horizon qualification in the final request: a permutation of length alone does not specify when a record outside those years will occur. Under the usual continuation by an infinite sequence of independent, identically distributed observations with a continuous distribution, the same relative-rank argument holds for every finite prefix. Then for every , and . These probabilities sum to one, so the second record occurs almost surely, butThe expected number of additional years after year one, , is also infinite. This is the first-sample case of the waiting time for a new record after a fixed sample.
If instead one asks for the mean year conditional on the second record occurring within the stated years, then, for ,The mean additional wait under that conditioning is this value minus one. These are distinct questions: assigning whenever no second record occurs in the finite horizon also gives an infinite unconditional mean, whereas a censored observation has finite expectation by the tail-sum formula for expectation.
By the spectral theorem for real symmetric matrices, choose an orthonormal eigenbasis with . If , thenThus every point of the ellipsoid has distance at least from the origin. Equality holds precisely whenBoth coefficients are strictly positive, so . The surface equation then gives . ThereforeExactly two points attain the minimum. The strict ordering makes the largest-eigenvalue eigenspace one-dimensional; this is the equality case in nearest points to the origin on a positive-definite ellipsoid.
A cyclic group is a group generated by a single element: there is such that every element is for some integer . For a finite group of prime order , choose . Its cyclic subgroup has order dividing by Lagrange's theorem, and its order is greater than one. Hence , and . Thus every group of prime order is cyclic.
A group homomorphism from is determined by , since . Its image generator must satisfy , so its order of a group element divides . As an element of its order also divides . These integers are coprime, so the only possible order is one. Thus , andThis map is indeed a group homomorphism, so there is exactly one, the trivial homomorphism.
Let . The time equations and the dot product differentiation rule give the local identityThe divergence of a cross product isCombining them yields . On a fixed bounded region with a boundary regular enough for the divergence theorem, differentiating under the integral and applying that theorem givesHere is the outward unit normal, so the sign expresses loss of the interior quadratic quantity by outward flux. No vanishing-boundary assumption is required.
For the unit-speed curve, the unit tangent vector, curvature of a space curve, principal normal vector and binormal vector areDifferentiating gives , so form a positively oriented orthonormal basis. The hypothesis makes the principal normal vector well-defined.
To determine the sign of the torsion of a space curve without relying on a pictorial handedness convention, take , , and use the unit-speed circular helixWriting , direct differentiation gives its Frenet frame:ConsequentlyAt the marked point is , with , , and . For , points opposite to and the torsion of a space curve is positive. Replacing by reflects the circular helix across the horizontal plane and makes the torsion of a space curve negative; then points in the same direction as . The direction of increasing is fixed in both panels.
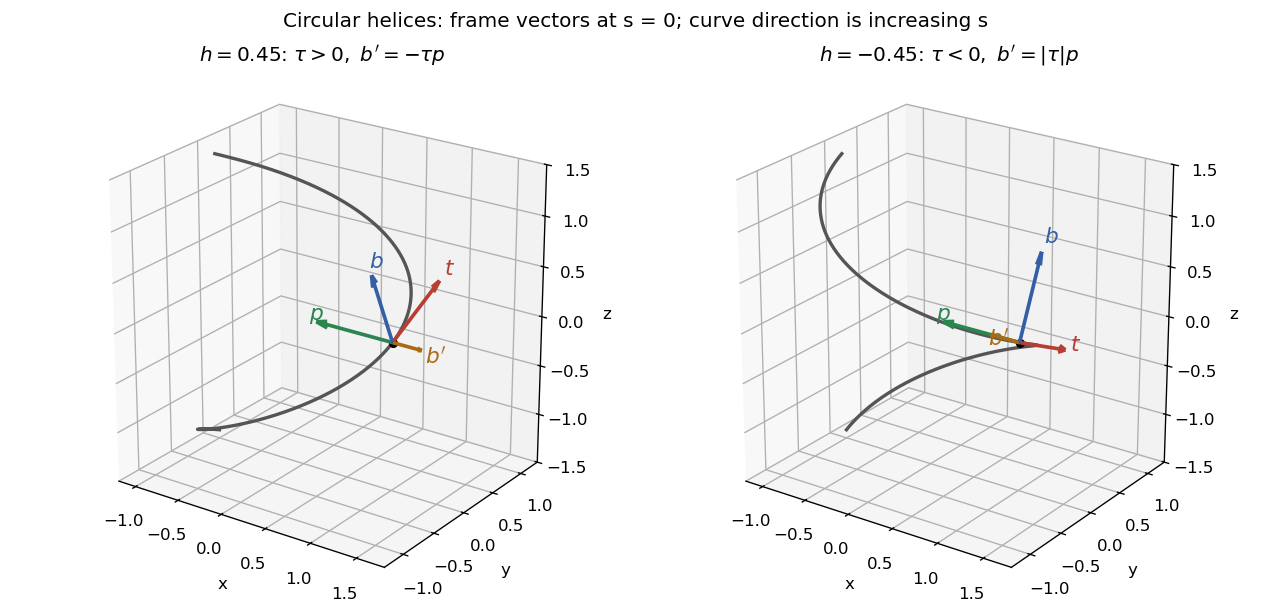
Unit-speed circular helices of opposite torsion, with tangent, principal normal, binormal and binormal derivative at the marked point
. Details. 
A group action is a map from to satisfying and . Define the orbit of a group action and the stabilizer subgroup . The latter is a subgroup: the identity fixes , products of elements fixing fix , and inverses do too.
For finite , the orbit-stabilizer theorem statesTo prove it, send a left coset to . If , then and . Conversely, equality of the two images implies , hence equality of the cosets. Every point of the orbit of a group action has such a preimage. This is therefore a bijection, and each coset has elements, proving the formula.
For the action on subgroups, conjugation maps a subgroup to a subgroup because it preserves products and inverses. Furthermore andThus this is the conjugation action. The stabilizer subgroup of is its normalizer , and since each conjugates onto itself. Hence the number of distinct conjugate subgroups isNow suppose is proper. Put and list the distinct conjugate subgroups as . Each has elements and all contain the same identity. Counting the identity just once, even if other elements overlap, givesThus some element of lies in no conjugate of . This proves conjugates of a proper subgroup do not cover a finite group by an explicit count; it does not require the conjugates to intersect only at the identity.
Represent the Riemann sphere by the complex projective line, with finite represented by and infinity by . An invertible matrix acts by , giving the stated fractional map on finite points. Applying and then is exactly matrix multiplication , including at poles and infinity. Thereforeso is a group homomorphism from the special linear group to the Möbius group.
Every Möbius transformation has an invertible complex matrix representative . Choose with . Such a nonzero square root exists in , and has determinant one while representing the same projective map. This proves surjectivity. If the map is the identity, fixing zero and infinity forces , and fixing one forces . The determinant-one condition gives . Conversely both scalar matrices and act trivially. HenceFor the normal forms, use the fact that a complex matrix has a Jordan normal form: either it is diagonalizable or it has one nontrivial Jordan block. For a determinant-one representative, distinct eigenvalues are . Diagonalizing gives , whose projective action is . Distinctness means , so is neither zero nor one.
If the eigenvalue is repeated, the determinant condition gives . A diagonalizable representative would be and would give the identity, excluded here. A nontrivial Jordan block is similar to , giving . Any invertible conjugating matrix gives a Möbius transformation; rescaling it to determinant one does not change that map. Thus these matrix similarities are genuine conjugacies in the Möbius group, proving the requested Möbius conjugacy normal forms.
Conjugacy preserves fixed points bijectively. A nonidentity scaling has exactly the two fixed points zero and infinity, while either translation has exactly one, infinity. The identity fixes every point. This proves all three possibilities and excludes any further finite number of fixed points.
Finally, suppose , with and . Then for every finite in the topology of the Riemann sphere; infinity remains infinity. Since is continuous on that sphere,This is iteration of a one-fixed-point Möbius transformation. The limiting statement includes the unique fixed point itself and uses spherical convergence, which also handles intermediate iterates equal to infinity.
The identity belongs to the center of a group. If are central, then for every ,so the center is a subgroup. For a central , for every , giving . Thus the center is a normal subgroup.
Write a matrix of the Heisenberg group as . Direct matrix multiplication and inversion giveThe identity is and each matrix has determinant one, so these formulas show closure under products and inverses inside . Hence is a subgroup.
The two products and differ only in their upper-right entries, by . Commutation with every therefore requires for all real . Setting forces ; setting forces . These conditions are also sufficient. ThusDefine the surjective group homomorphism by . The multiplication formula gives , and its kernel of a group homomorphism is precisely . The first isomorphism theorem yieldsThis center quotient of the real Heisenberg group can also be checked directly: two elements have the same coordinates exactly when they differ by multiplication by a central element, and quotient multiplication adds these coordinates.
First is a linear subspace. To prove it is nonzero, use orthogonality and :Hence . If then also implies . For ,so is invariant. If had dimension two, its one-dimensional orthogonal complement would be invariant and would act there as a scalar . The determinant would be , so , forcing . Dimension three also forces . Both contradict the hypothesis. ConsequentlyChoose an orthonormal basis beginning with a unit vector in and followed by a basis of . In this basis the orthogonal matrix has block formThe first column of is some . Its perpendicular unit second column with positive orientation must be . Thus the restriction is the plane rotationTrace invariance gives , provingA Euclidean reflection in fixes that plane pointwise and reverses , so it occurs exactly when . This is equivalent to , hence exactly to . Finally,This exhibits the three-dimensional improper orthogonal transformation as a rotation about the axis composed with Euclidean reflection in .
Assume sufficient smoothness and a regular boundary for the integrations below, with outward. Put , so on . Expanding the Dirichlet energy givesBy Green's first identity, the middle integral isThus the Dirichlet principle follows with an explicit remainder:Equality means is constant on each connected component; its zero boundary value forces that constant to be zero.
Now let solve the heat equation and set . Differentiation followed by Green's first identity givesUnder time-independent Dirichlet boundary conditions, on , while in . ThereforeIf equality holds at a particular time, continuity makes throughout at that time. Its boundary values are still , so uniqueness of the Dirichlet problem implies . Conversely has and gives equality. This proves the full equality criterion for Dirichlet energy dissipation for the heat equation.
For the dynamic boundary condition for the heat equation, substitute directly into the boundary term. The interior equation is unchanged, soThis is Dirichlet energy dissipation with a dynamic heat boundary condition. It remains valid when vanishes, because no division by is used. The last part preserves energy monotonicity; its stationary states need not have the earlier prescribed Dirichlet data. For example, with strictly positive on a connected boundary, a stationary harmonic state has zero outward normal derivative and is constant, as follows by applying Green's first identity to that state itself.
For an oriented piecewise smooth surface and a continuously differentiable vector field, Stokes theorem stateswhere the boundary orientation is induced by through the right-hand rule. Choose the upward orientation of the elliptic paraboloid. Its band has cylindrical radius , and a parametrization isIts oriented surface element and scalar area element areThe requested sketch shows the open band, not a capped solid.
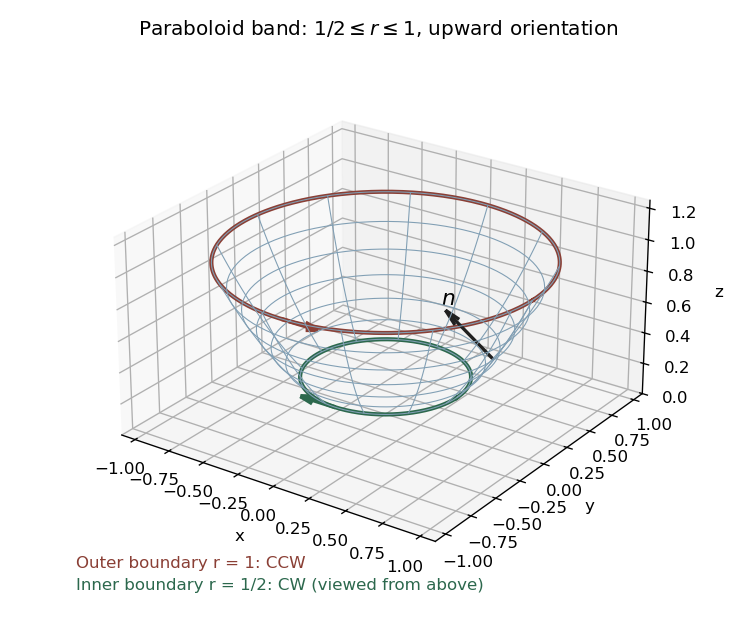
Upward-oriented annular paraboloid band, with counterclockwise outer boundary and clockwise inner boundary
. Details. 
For the specified vector field, direct differentiation gives . HenceTo check this by Stokes theorem, parametrize a counterclockwise circle of radius at height by . Along it , andUsing gives . The induced outer circle is counterclockwise as viewed from above, and the inner circle is clockwise. ThereforeThis verifies the direct surface integral and the Stokes flux through an annular paraboloid. Reversing the chosen surface orientation reverses the final sign.
At a critical point of a twice continuously differentiable real function, and the Taylor expansion isThe real symmetric Hessian matrix has an orthonormal eigenbasis, so writing gives . If every eigenvalue is positive, this quadratic form is at least , and the remainder cannot change its sign for sufficiently small nonzero . Thus is a strict local minimum. If every eigenvalue is negative, the analogous argument gives a strict local maximum. If positive and negative eigenvalues both occur, displacement along the corresponding eigenvectors gives values above and below , so is a saddle point of a scalar function.
The second-derivative test can be inconclusive when the Hessian matrix is singular and semidefinite: higher-order terms along directions in the kernel of a linear map matter. For example and have the same Hessian at zero, but the first has a strict minimum and the second a saddle point of a scalar function. A zero eigenvalue does not prevent a saddle conclusion if other eigenvalues already have both signs.
For the given function write . Its first derivatives areThe origin is a critical point for every real , withIts eigenvalues are , so it is always a saddle point of a scalar function. If one coordinate at a critical point is zero, the other must also be zero. If both are nonzero, the derivative equations force , possible only for . Hence for the origin is the only critical point.
For there are four additional critical points,At such a point,Thus the two equal-sign points are strict maxima, and the two opposite-sign points are strict minima. They are global: implieswhere the last maximum occurs at and equality also requires .
As , the four nonzero critical points have distance from the origin and escape to infinity, rather than merging with the origin. Their values diverge as . As from below there are no extra critical points, while the origin stays a saddle throughout. This is critical points escaping to infinity in a Gaussian-weighted bilinear function.
Articles were limited to the first 100 out of 127 total.
Articles by others on the same topic
There are currently no matching articles.