An integral adds up contributions of a function across a domain of integration. For a continuous function on , the Riemann integral is the common limit of its Riemann sums as the largest subinterval width tends to zero:Each product combines a value with the width over which it acts. When is nonnegative, the result is the area beneath its graph; values below the horizontal axis contribute with the opposite sign. The signed area under a graph can therefore vanish even when the graph encloses nonzero geometric area.
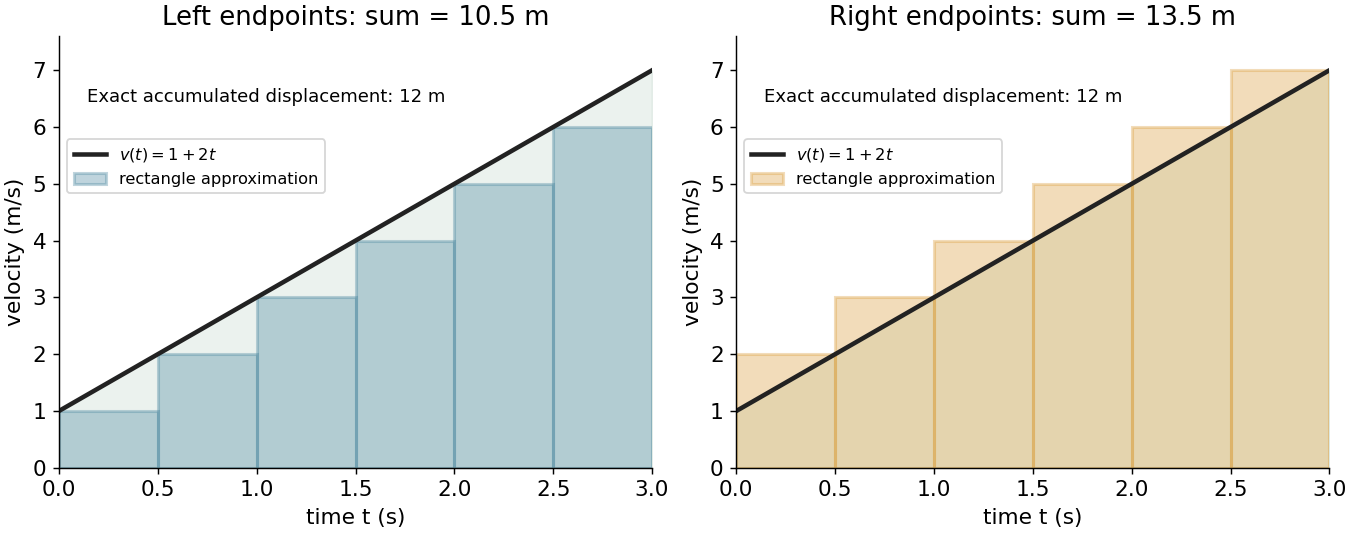
For a velocity on , use equal time steps. The left and right Riemann sums areBecause the function is increasing, they bound the integral. With six steps they give and ; with sixty steps they give and . Both approach the same total, . This is accumulation made exact by refining finite measurements.
An integral retains units: velocity times time gives displacement, and a probability density function integrated over an interval gives a probability. Weighting a density by a function gives its expectation. The same operation serves different subjects because it expresses a common pattern, value multiplied by extent, then accumulated.
The fundamental theorem of calculus often evaluates a definite integral by finding an antiderivative, but a finite sum or a numerical approximation is still useful when no convenient antiderivative is available. An indefinite integral denotes a family of antiderivatives; a definite integral denotes an accumulated value between specified endpoints. More general constructions, including Lebesgue integration, extend the class of functions and domains that can be handled.
On , the power rule for derivatives and the fundamental theorem of calculus give the displayed antiderivative. In particular for , understood as an improper integral when needed. At , the antiderivative on is the natural logarithm .
An integral over the boundary of a region, such as a line integral around a planar region or a surface integral over the boundary of a three-dimensional region. Green's identities convert certain volume integrals into boundary integrals.
The two identities areTo prove them, expand in its exponential series. Since on , the Weierstrass M-test justifies termwise integration. Substituting gives through the gamma function. Inserting these moments into the series and shifting proves both formulas. Each resulting numerical series has absolute convergence.
If measurable functions satisfy almost everywhere and is nonnegative and Lebesgue integrable, then is Lebesgue integrable and . This follows from monotonicity of the Lebesgue integral. Conversely, with rules out Lebesgue integrability of . For nonnegative improper integrals, the same comparison applies after taking increasing finite-interval limits.
The domain of integration is the set over which an integral is taken. For a multiple integral, inequalities or parameter ranges specify which points belong to ; a change of variables transforms both these bounds and the integration element through its Jacobian determinant. For example, a polar region exists only at angles where .
The set over which an integral is taken. For a double integral, boundary inequalities describe the allowed coordinate pairs, and slices of this set determine the limits in an iterated integral. The domain need not be a rectangle or connected. A change of variables transforms both the integrand and this set.
If and is differentiable, the chain rule gives . Taking antiderivatives gives the substitution ruleWriting and records this chain rule in reverse. For a continuous function and continuously differentiable , the fundamental theorem of calculus gives the corresponding definite integral identityThe order of the transformed endpoints determines the sign. For example, . If the substitution is used in the opposite direction by solving as a function of , one must restrict to a suitable inverse branch; the tangent half-angle substitution illustrates why separate branches can be necessary even when the original integrand is smooth. The general change of variables formula extends substitution to higher dimensions.
A trigonometric substitution is integration by substitution using a trigonometric function to simplify an integrand, especially a square root. For example, , with and , changes to and to . The interval restriction fixes the sign of the square root. Similarly simplifies . The transformed integral must include the differential and, for a definite integral, the new limits.
For an integrable function on an interval of positive finite length, its average value is the integral divided by that length:If is constant on equal-length subintervals, this is their values' arithmetic mean; unequal lengths require a weighted mean. For example, values and on two equal halves give average value , whereas value on the first quarter and on the remaining three quarters give . The integral measures total contribution; the average value of a function divides out the interval length.
For the function on , the average value of a function is . Replacing it by the constant preserves its integral on this interval. This is why the Haar projection uses cell averages to obtain a coarser description while retaining each cell's total contribution.
For integrable real-valued functions on a measure space and fixed real numbers , their linear combination is integrable, and the Lebesgue integral satisfiesThe same rule applies to any finite summation: for integrable functions and fixed scalars . Finite signed values matter: integrability ensures all these integrals are finite, so no undefined occurs.
This is the distributive property of finite summation carried into integration: a fixed factor can be pulled out, and a finite sum can be integrated term by term. For simple functions, distribute the finite sums of value times measure; approximation extends additivity to nonnegative measurable functions, and splitting into a positive part and negative part gives the integrable signed case. See Lecture 12: Lebesgue Integrable Functions, the Lebesgue Integral and the Dominated Convergence Theorem (Proposition 122: linearity for integrable functions). For example, . With a probability measure, linearity of integration gives linearity of expectation.
For and a real-valued function with a finite Riemann integral or Lebesgue integral on , the signed area under a graph is its definite integral: geometric area above the horizontal axis contributes positively, and geometric area below it contributes negatively. If these two nonnegative areas are and , thenThe second expression is the total geometric area under a graph. Taking the absolute value of the first expression does not usually give the second: cancellation has already removed information about how much area lies on each side.[ref]
For an exact example, take the polynomial function on . Its polynomial roots are and : it is negative between them and positive on the two outer intervals. An antiderivative is , so the fundamental theorem of calculus givesThus and . The signed area under a graph is , whereas the total geometric area under a graph is . To compute the latter with antiderivatives, split at each sign-changing polynomial root and reverse the sign of the negative contribution.
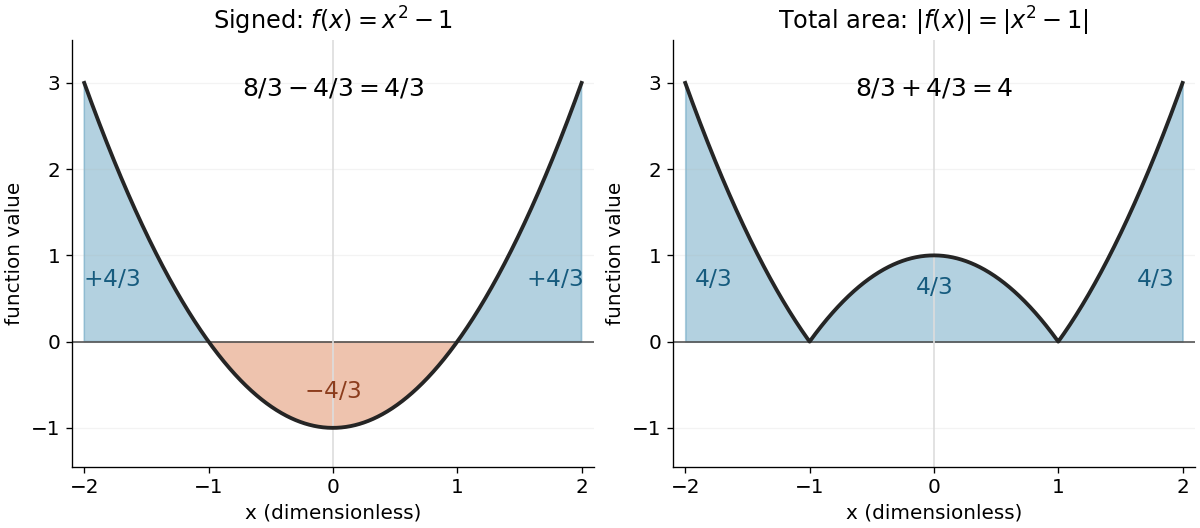
The polynomial x squared minus one has signed integral 4/3 and total geometric area 4 on the interval from minus two to two
. Details. Cancellation is useful information when the integrand represents a signed contribution. For the polynomial function on , the two triangular areas give , although . Zero net signed area therefore means balanced positive and negative contributions, rather than an empty region.
The short algebraic justification uses the positive part and negative part : and . Their integrals give and , and linearity of integration gives the difference and sum formulas. For Lebesgue integration, require both contributions to be finite to avoid the undefined subtraction .[ref]
A definite integral accumulates an integrand between specified endpoints, retaining the sign of each contribution. For a real-valued function on a finite real interval, a finite definite integral is a scalar; an indefinite integral describes a family of antiderivatives. The lower and upper limits of integration specify where accumulation starts and ends. The integration variable is a placeholder: .
This is useful whenever a varying rate must be converted into a total change. For motion along a straight line with continuous velocity and position satisfying , the fundamental theorem of calculus gives displacement, while accumulating speed gives the distance traveled from velocity:Negative velocity reduces displacement while adding to the distance traveled from velocity. The physical dimension of a definite integral is the product of the integrand's physical dimension and the integration variable's physical dimension: here . An area on a rate graph need not be a spatial area.[ref]
5.4 Integration Formulas and the Net Change Theorem. Theorem 5.6 and the displacement and total-distance discussion
As an explicitly synthetic motion model, let for , with . Using numerical values in seconds and metres, an antiderivative gives . The velocity changes sign at : the model first moves m in the negative direction, then m in the positive direction. Its displacement is m, and its distance traveled from velocity is m. The initial position fixes the constant of integration, but does not change either accumulated quantity.
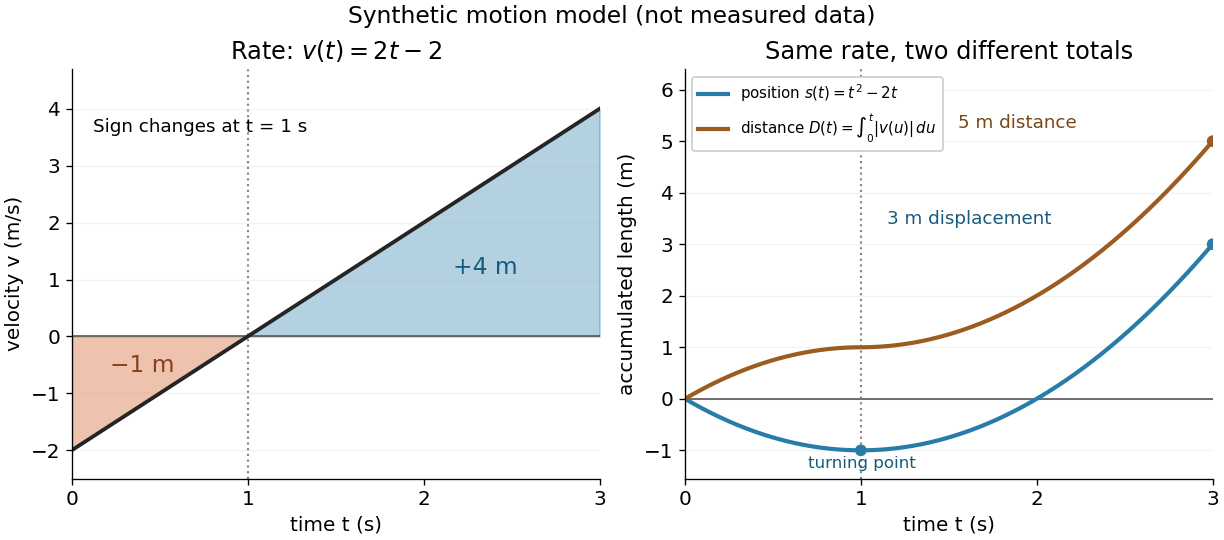
Synthetic variable velocity model with displacement 3 metres and distance traveled 5 metres over three seconds
. Details. Orientation matters independently of whether the integrand is positive or negative. For a function integrable on the interval containing the endpoints, use the conventionsFor the preceding velocity model, accumulation from seconds back to seconds gives m. Reversing the bounds of the speed integral gives m, which is an oriented integral, not a negative distance traveled from velocity; physical elapsed-time totals use the earlier endpoint first. The splitting rule holds even when is outside the interval between and , provided integrability holds on the interval containing all three endpoints.[ref]
Existence needs hypotheses. For a bounded function on with , a finite Riemann integral exists when every tagged Riemann sum approaches the same value as the largest cell width tends to zero:The limit must be independent of both the partition of an interval and the tags. Merely making the number of cells large can leave a wide cell unresolved. On a finite closed interval, every continuous function, and every bounded function that is continuous except at finitely many points, is Riemann integrable.[ref] Boundedness alone is insufficient: the Dirichlet function on is on the rational numbers and on the irrational numbers. Tags can all be chosen rational or all irrational, giving Riemann sums of or at arbitrarily small cell widths.[ref]
For a finite signed Lebesgue integral, the condition is instead that be a measurable function for Lebesgue measure and . A measurable function for Lebesgue measure that is also a bounded function on a finite interval satisfies this condition since gives . The Dirichlet function therefore has Lebesgue integral zero: the rational numbers form a null set, so it equals zero Lebesgue almost everywhere. The Riemann integral and Lebesgue integral agree for the continuous functions used in the diagrams.[ref]
Lecture 12: Lebesgue Integrable Functions, the Lebesgue Integral and the Dominated Convergence Theorem. Definition 120, Proposition 123(2), Remark 124 and Theorem 126
An unbounded integrand or infinite endpoint requires further analysis, for example the limits defining an improper integral; the notation alone does not establish convergence.The lower and upper integration limits specify the ordered endpoints of a definite integral . Interchanging the integration limits reverses its sign: .
The Wallis integrals are for integers . Integration by parts gives for , with , . HenceBecause in the integration interval, for . Combining this with the recurrence gives , proving that the ratio tends to one and yielding the Wallis product.
Here , and . The identity holds where the segment of source points , , avoids the observation point and the denominator is nonzero. Differentiating the right side with respect to gives the integrand and its value at is zero. Dotting with a current dipole moment evaluates a continuous line of dipole electric potentials.
In , the function is the integrand. It is distinct from the integration variable, the bounds and the resulting integral. In contour integration, the transformed integrand includes the parametrization derivative.
A multiple integral accumulates a function over a region with several coordinates. The Fubini theorem and Tonelli theorem give conditions under which it equals successive one-dimensional integrals. A change of variables formula expresses it in new coordinates using the absolute Jacobian determinant.
A triple integral is a multiple integral over a three-dimensional region. For a mass density , gives the total mass, while gives its volume. Iterated one-dimensional integration is justified by Fubini's theorem under absolute integrability, and a change of variables includes the absolute Jacobian determinant in the volume element.
Under a smooth locally invertible coordinate map into Euclidean space, the positive volume element in a multiple integral is multiplied by the absolute Jacobian determinant. In three-dimensional spherical coordinates, ; in cylindrical coordinates, . The absolute value distinguishes positive integration measure from a signed orientation convention.
An iterated integral performs successive one-variable integrals. In the displayed expression, is held fixed during the inner integration over , and the result is then integrated over . The inner bounds may depend on that fixed outer variable. By contrast, an inner bound depending on an already integrated variable does not specify such a nested operation without further interpretation. For example, the triangle , gives , or, in the other order, . Fubini's theorem and Tonelli's theorem supply conditions under which these iterated expressions equal the same multiple integral.
The sequence in which variables are integrated in an iterated integral. Reversing the order changes the slicing of the domain of integration, often requiring more than one integral. Fubini's theorem permits interchange for absolutely integrable functions, while Tonelli's theorem permits nonnegative measurable integrands even when the integral is infinite. Conditional convergence requires additional care; geometric reversal alone is not a general justification for interchanging improper integrals.
If a region is invariant under one coordinate reflection and an integrable function changes sign under that reflection, its multiple integral is zero. Apply the change of variables formula to the reflection, whose absolute Jacobian determinant is one: the integral equals its negative. This applies to odd coordinate powers in symmetric volumes and to the off-diagonal entries of an inertia tensor when the mass density shares the coordinate-reflection symmetries.
An integral representation expresses a function through an integral of specified data and an integral kernel. Green-function representations solve differential equations this way, while the Bromwich inversion formula reconstructs a function from its Laplace transform.
The sine and cosine integrals accumulate and , with different normalizations at zero and infinity. They arise in oscillatory integrals, Fourier transforms of singular kernels and Fourier series of logarithmic profiles.
For real , its small-argument expansion is . Integrating separates the logarithm from the regular correction. Its conventional constant is the Euler--Mascheroni constant; the primary series normalization is dlmf.nist.gov/6.6.E6 .
For real , the sine integral approaches . Exponential damping gives , so the limiting constant follows by letting . Integration by parts of the tail gives .
Lebesgue integration constructs an integral from the measure of level sets or from approximation by simple functions. It is linear on integrable functions and is stable under the principal convergence theorems of measure theory.
If and nonnegative measurable functions satisfy for all , then their Lebesgue integrals obeyThe quantile derivative identity and monotone substitution inequality prove the one-dimensional case; Tonelli theorem extends it by induction. It implies the Brunn–Minkowski inequality.
If , then for every there is such that whenever the measure of is below . In particular, integrals over a sequence of shrinking measurable sets tend to zero.
A time integral accumulates an integrand over a time coordinate. In perturbation theory it commonly sums the effect of an interaction over all possible vertex times.
A double integral integrates a function over a two-dimensional region. A change of variables formula can replace the region and area element using a Jacobian determinant.
It is a multiple integral with two integration variables.
An antiderivative recovers a function from its local rate of change. For a real-valued function on an open subset of the real line, a differentiable function is an antiderivative whenFor example, has the antiderivatives for every real additive constant . Their derivatives agree, while their values can differ. On an interval, the constant of integration describes the entire freedom in the answer. [ref]
https://openstax.org/books/calculus-volume-1/pages/4-10-antiderivatives. OpenStax Calculus 1, §4.10: antiderivatives and their families
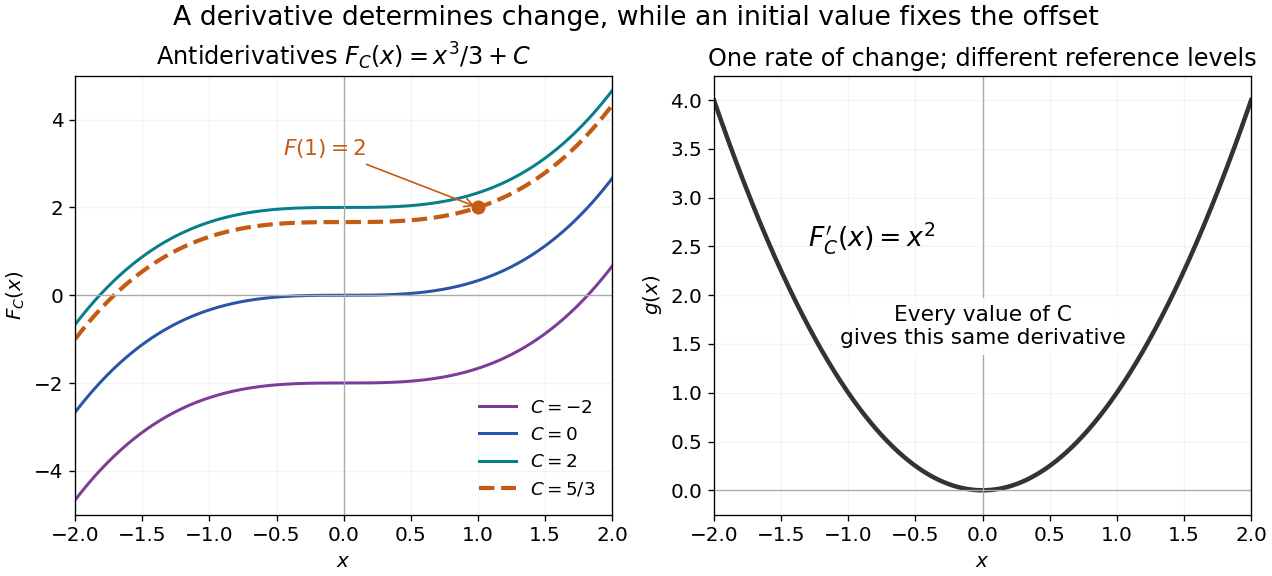
The indefinite-integral notation records this family on an interval. For the illustrated family, the extra condition selects . Thus reversing differentiation requires both a rate and a reference value if a unique function is wanted.
The fundamental theorem of calculus supplies a construction when is continuous on an interval . Choose and set ; then . Integrability alone does not guarantee a classical antiderivative. The Heaviside step function is Riemann integrable on bounded intervals, but cannot be a derivative throughout an interval containing its jump: Darboux theorem for derivatives requires every intermediate value. [ref]
https://www.jirka.org/ra/html/sec_mvt.html. Lebl, Basic Analysis I, §4.2.5: the intermediate-value property of derivatives
A holomorphic function on a domain with complex derivative . Its contour integral satisfies by the chain rule along each smooth contour segment. In particular every closed contour has integral zero. Having local complex antiderivatives need not provide a single one on a domain with holes.
On a connected open interval, if , every antiderivative of has the form , where is a constant function. Indeed, two solutions satisfy : the zero derivative on a connected open set principle makes their difference constant. In one dimension, the mean value theorem proves this on any closed subinterval. [ref]
https://www.jirka.org/ra/html/sec_mvt.html. Lebl, Basic Analysis I, Proposition 4.2.6: zero derivative on an interval
An initial condition or boundary condition can determine . If a particular antiderivative is and , thenFor , and , this gives . Without that reference value, choosing simply selects one member of the family.
The freedom has a physical meaning in a simple kinematic model. A velocity , with constant acceleration , determines position only as . The initial condition selects ; changing the starting position does not change the prescribed velocity.
For the differential equation on , the antiderivative is . The boundary condition gives . Discarding the constant of integration therefore needs a specified condition or an approximation that quantifies its effect. On a domain with several connected components, the freedom is larger: antiderivatives on disconnected domains require a separate constant on each component.
Let be an open subset of the real line, and let be antiderivatives of the same function on . Each connected component is an open interval. On that component, , so the mean value theorem gives . The constants on different components are independent: there is no subinterval inside joining them. Conversely, adding any chosen constant on each component preserves the derivative everywhere on .
For example, the domain of is . Every antiderivative on this domain has the formwith arbitrary real . The logarithm of the absolute value differentiates to on each side. The function with and is therefore a valid antiderivative, although it cannot be written as with one global constant.
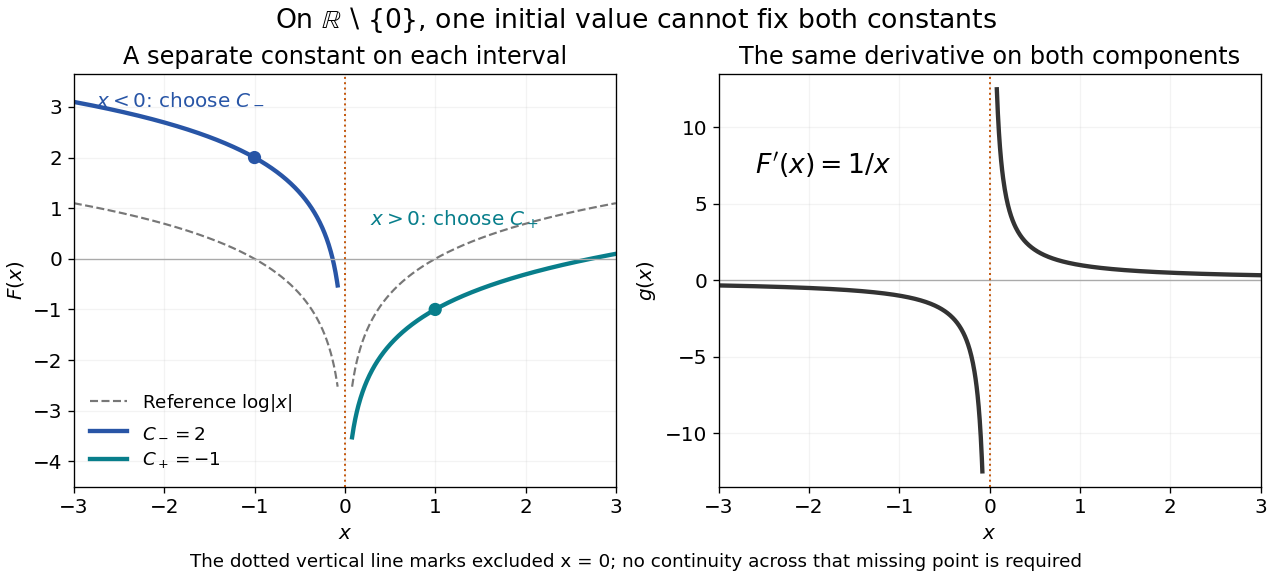
Two disconnected intervals allow independent constants while the derivative stays the same
. Details. An initial condition at fixes and leaves free. Fixing both constants requires one reference value in each connected component, or additional conditions that couple the components. The locally constant function captures this remaining freedom.
A constant added to a function changes its reference level without changing its derivative:Geometrically, it is a vertical translation of the graph. For , changing moves every plotted value by the same amount while preserving every tangent slope. This is the geometric reason that antiderivatives form a family.
When represents a physical quantity, the physical dimension of must match that of . When position is obtained from velocity, is a position offset. An unknown starting position remains unknown even when the rate of change is known exactly.
When describing the family of antiderivatives on an interval, the arbitrary additive constant is the constant of integration. On a disconnected open domain, the corresponding freedom is a locally constant function, as in antiderivatives on disconnected domains, rather than necessarily one constant on the whole domain.
The Gaussian integral gives the exact area under a Gaussian function. For a positive real number ,This is a finite improper integral over the whole real line. For example, and . Increasing from one to four narrows the curve and halves its area, while its height at zero stays one. The change of variables explains the factor .
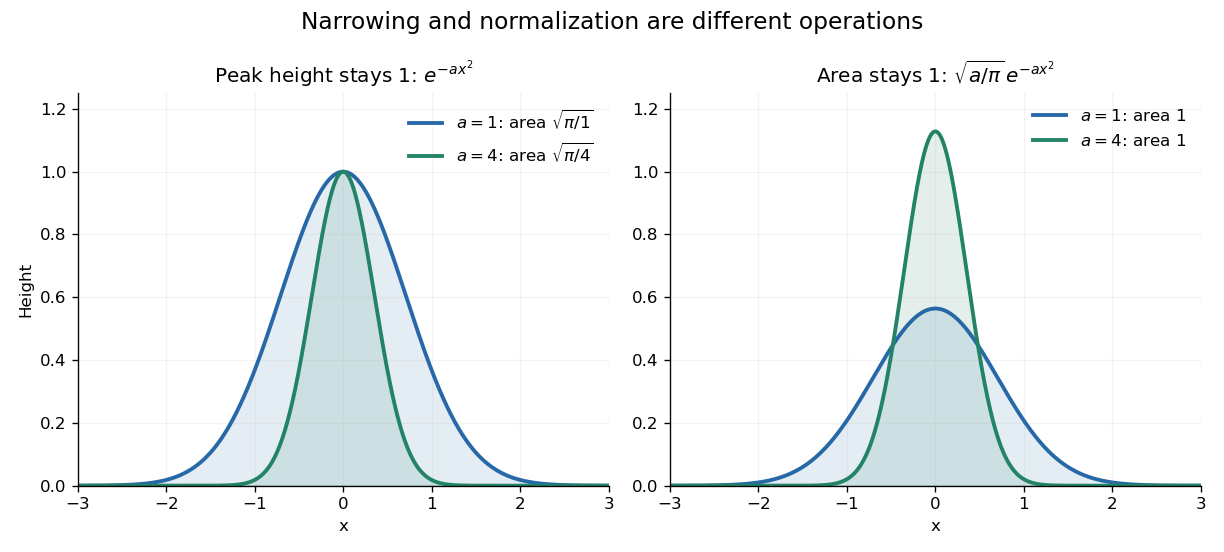
The useful consequence is an exact normalization. For and any real center ,This is a probability density function for a normal distribution with expected value and variance . A narrower probability density function must be taller to keep total probability one. In the usual notation , the prefactor is , where is the standard deviation.
The same area calculation makes the one-dimensional heat kernelintegrate to one in , with the diffusion coefficient. A spreading Gaussian function can therefore preserve total mass while its height falls. This links the Gaussian integral with both the normal distribution and the diffusion equation.
Finite intervals lead to the error function, rather than this single constant:The complementary tail is described by the complementary error function. These definitions and their real-axis limits are given in the NIST reference. [ref]
The polar-coordinate proof of the Gaussian integral explains why appears in an integral of a function defined on a line: squaring its area creates a rotationally symmetric integral on a plane. Substitution also gives , connecting the result with the gamma function.
For , the real integrand is symmetric under , so the ordered domain contributes half the full plane. The result is , using the Fourier transform of a Gaussian function. The imaginary part is not generally zero and must not be discarded before pairing conjugate harmonics in a real response.
For , the integrand is even and integrable at zero and infinity. On the positive half-axis the change of variables maps bijectively onto and satisfies . Solving the quadratic for the positive root givesAfter doubling this half-axis integral, the odd part of the transformed integrand integrates to zero and the remaining Gaussian integral yields the formula. The reciprocal substitution also givesThe positive parameters ensure that the substitutions and improper integrals are valid; the second identity can also be recovered by differentiating the first in under the integral sign.
For integers , integration by parts givesThe boundary term vanishes because at zero and Gaussian decay dominates every power at infinity. The initial values are , the half-line Gaussian integral, and by the substitution rule . More generally, for real , that substitution gives , linking the recurrence to the Gamma function.
For and a nonnegative integer , substitute . Then , so the integral reduces to the gamma function value . This proves the formula. The corresponding whole-line integral is zero by odd symmetry, and both integrals converge absolutely. A half-line integral of an odd function need not vanish.
For integer , integration by parts gives . The boundary term vanishes at both infinities because Gaussian decay dominates every power. The full-line initial values are and , the latter by odd symmetry. HenceUnlike the half-line Gaussian moment recurrence, full-line odd moments vanish and even moments are twice their half-line values. The domain of integration must be retained when transferring a recurrence between the two settings.
Put . The nonnegative integrand allows Tonelli's theorem to write the square as a double integral:In polar coordinates, , , and the Jacobian determinant supplies the area factor :Since , take the positive square root to get . The computation proves finiteness as well as the value. For an explicit limiting argument, first integrate over disks of radius ; their integrals are , which increase to as . [ref]
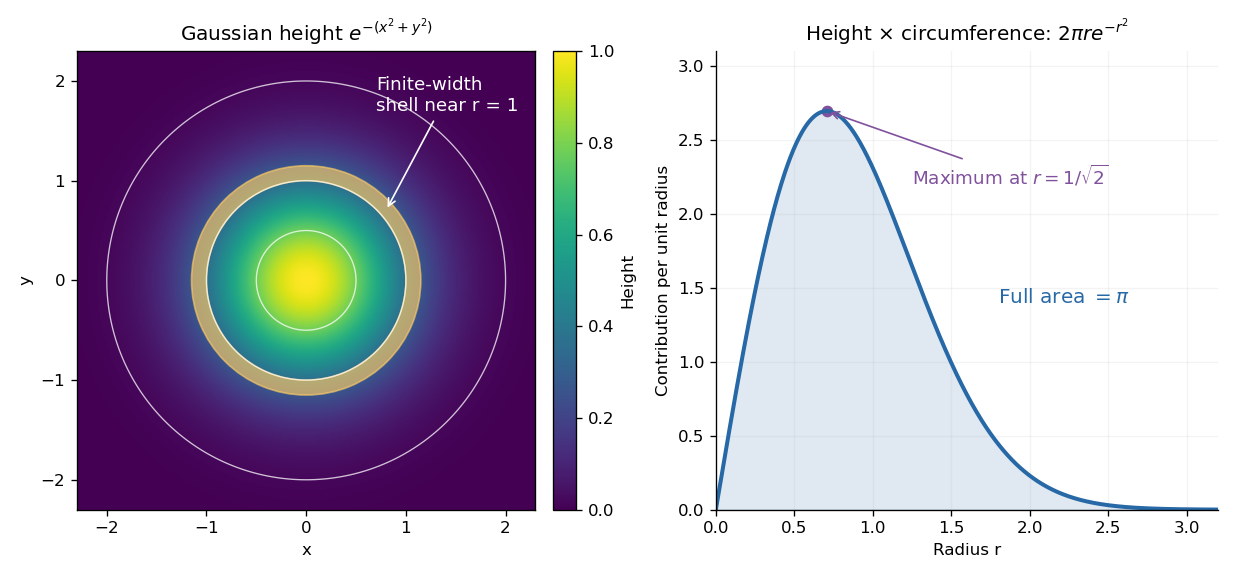
The geometric surprise is that radial shells get longer as increases, even while the Gaussian function gets smaller. Its central height is largest at zero, but the radial contribution vanishes there and peaks at . Differentiating gives , which changes sign at that radius. Keeping the Jacobian determinant is what makes the one-dimensional integral and the plane geometry agree.
For real symmetric positive-definite , complete the square with . Orthogonal diagonalization reduces the remaining integral to the product of one-dimensional Gaussian integrals, proving the displayed expression. Positivity ensures convergence and the positive determinant square root. Replacing matrices by regulated field kernels gives the Gaussian functional integral; an oscillatory Minkowski integral instead requires a causal convergence prescription.
The Dawson function obeys by differentiation. Its large-real-argument asymptotic expansion begins . This inverse-power behavior contrasts with the separate exponentially growing factors in its definition.
Define and . They satisfy and . The first is an even function, the second an odd function, and their real tails are respectively and . Their derivatives have inverse-linear tails, explaining the logarithmic matching constants in a singular perturbation.
The error function records the signed area under a Gaussian function between zero and a variable endpoint:For a negative real number , reversing the integration limits makes this integral negative. The normalization uses the Gaussian integral: the full area of is , so its positive half contributes one after multiplication by . The same definition extends to a complex number along any path from zero to , giving an entire function.[ref]
For example, , , and . A finite positive endpoint captures only part of the positive Gaussian integral; approaches one as but never reaches it at a finite real .
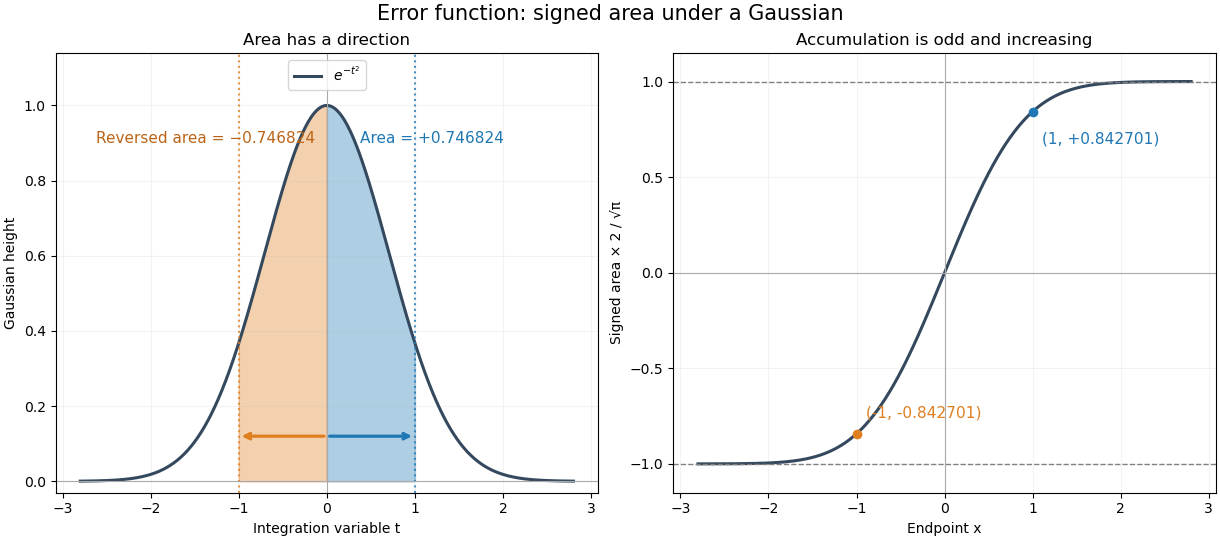
The useful idea is to name a recurring integral once instead of carrying it through every calculation. The error function and the normal distribution express probabilities and quantiles through this area, while an error-function diffusion front describes how diffusion smooths a sharp jump. The complementary error function retains the small area left in the tail.
The fundamental theorem of calculus givesThus the real-axis error function is strictly increasing, with values in . Its integrand is an even function, so the error function is an odd function, . The derivative also gives : the curve is concave for and convex for . These real-axis properties do not imply boundedness throughout the complex plane; the existing quadrant asymptotics of the error function describe a different behavior in other directions.
For a standard normal random variable , its standard normal distribution function isThe change of variables and the symmetric distribution of the standard normal random variable give the second expression. For with , standardization of a normal random variable then givesIn particular, the intervals within one, two, and three standard deviations have calculated probabilities about , , and . These values depend on a normal distribution; they are not universal coverage guarantees for an arbitrary random variable. This is the direct connection between a Gaussian function area and the familiar central intervals.
For a small upper-tail probability, use the complementary error function directly:Computing this as instead can lose the tail to catastrophic cancellation. The Gaussian tail bound gives another useful estimate without requiring an exact error function value.
Because the real error function is strictly increasing from to , its real inverse function maps onto the real line. For , the standard normal quantile is thereforeMore generally, the -quantile of a normal distribution with expected value and positive standard deviation is . This reverses the area calculation: instead of asking how much probability lies below an endpoint, a quantile asks which endpoint encloses a specified probability. The domain restriction matters; and correspond to infinite endpoints, rather than finite real values of the inverse error function.
Consider the one-dimensional diffusion equation on the whole real line,with initial value one for and zero for . This is an idealized Heaviside step function profile, not a measured material or an apparatus specification. The heat kernel gives a convolution with the initial profile:The change of variables turns the convolution into a Gaussian integral tail. The resulting similarity variable shows that the transition width grows like : multiplying elapsed time by four doubles every fixed-profile distance from the original interface.
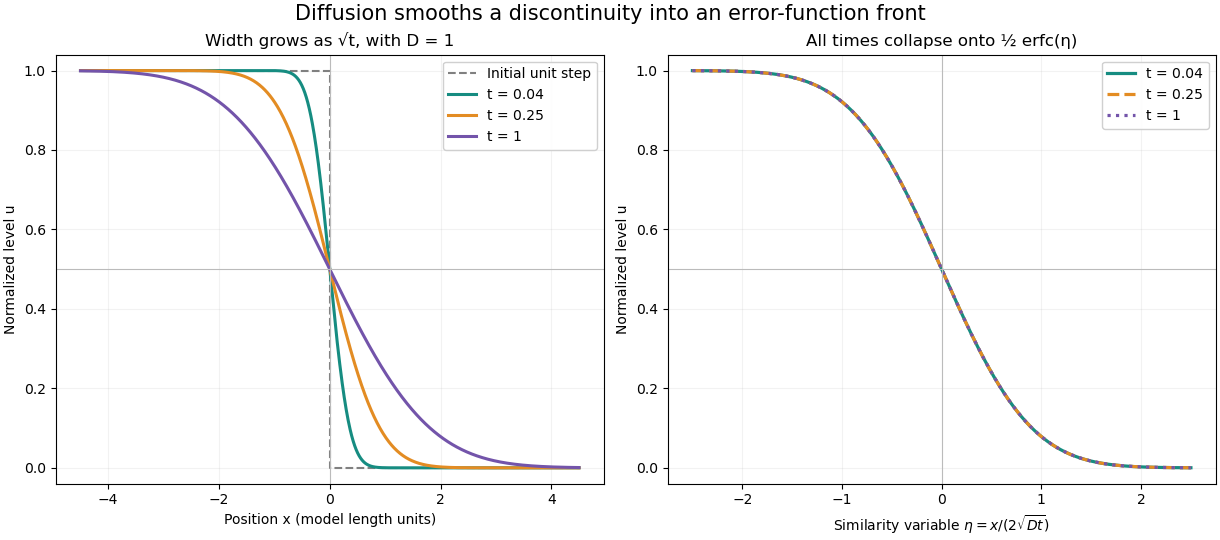
At every positive time, , while as and as . For every fixed , the limit as returns the specified initial value. The value assigned at the single initial discontinuity does not change this convolution. The error function therefore explains smoothing without pretending that a discontinuous initial profile remains sharp.
Direct differentiation checks the partial differential equation. Writing givesThe model assumes constant diffusion coefficient, no advection, and no finite-domain boundary effects. For an interpretation as heat conduction, the heat equation applies to a normalized temperature difference under its own material assumptions.
For with fixed , a horizontal tail gives . The constant dominates through ; above that angle the exponential endpoint dominates. At the boundary angle its modulus is only , so the constant remains leading. On the imaginary axis the integral is purely imaginary and grows as . The approximation is not a determination of exponentially subdominant constants in that growing sector.
The complementary error function describes the Gaussian integral area remaining beyond the endpoint. For a real ,It is an entire function for complex arguments when defined by . On the real line it decreases from two to zero, with and .[ref]
For example, is a sizeable tail, whereas is extremely small. In the tested floating-point arithmetic, a direct evaluation of gives zero because the computed error function has already rounded to one. Evaluating the complementary error function directly preserves this tail. It is the useful quantity in an upper-tail normal distribution probability and in the decaying side of an error-function diffusion front.
For large positive real , the leading asymptotic expansion isThe first corrections are multiplying the leading term. This is an asymptotic expansion, not an assertion that summing arbitrarily many terms converges at a fixed .[ref] The complementary error function tail bound provides finite- inequalities instead.
For every real ,For a short proof, put . Integration by parts givesThe last integral is positive and strictly smaller than . Using these two inequalities gives the upper and lower bounds after multiplication by . Dividing both bounds by also proves the leading asymptotic equivalence by the squeeze theorem. For small positive , the bounds remain true but can be loose; they are especially useful when the Gaussian integral tail is already small.
The Faddeeva function is an entire function built from the complementary error function. Its integral representation for is , as normalized in NIST's integral representation. Its reflection identity is , directly from the odd function property of the error function.
For a pole off the real axis, substitution into the Faddeeva function integral gives when , and when . The difference of boundary values is the residue theorem jump . In particular, for a lower-half-plane pole, , which packages a crossed residue and a nearby saddle into one smooth expression.